
Will At Home Leqembi Approval Change Eisai Stock's Narrative
- Eisai and BioArctic’s partner update shows that Japan has now approved Leqembi’s subcutaneous autoinjector for early Alzheimer’s. This adds a once weekly at home option that complements the existing IV regimen and is supported by Phase 3 Clarity AD data showing comparable exposure and safety.
- The shift toward self administered Leqembi treatments matters for Eisai’s operating reality because it can reshape treatment logistics, potentially ease hospital capacity pressure, and make the Alzheimer’s franchise more accessible to patients and caregivers who struggle with frequent infusion visits.
- We will now examine how Eisai’s investment narrative could be affected by broader access through weekly at home Leqembi injections.
Scan beyond Eisai and compare this Alzheimer’s update with other healthcare stocks that have passed our quality filters in the list of solid balance sheet and fundamentals (20 results).
Eisai Investment Narrative Recap
An investor in Eisai needs to believe that the Alzheimer’s portfolio, especially Leqembi, can justify the current premium P/E multiple and offset pressure on older products. The key near term swing factor is how quickly eligible patients start and stay on therapy across regions. The fresh approvals for weekly at home injections speak directly to that adoption question.
The biggest risk still sits in pricing and policy. Japan is already pushing for cuts to Leqembi, and broader pressure on drug costs could squeeze revenue even if volumes improve. Any new safety, reimbursement or competitive setback in Alzheimer’s would affect Eisai’s earnings profile and test that rich valuation.
The recent approval of the Leqembi Pen in Japan is particularly relevant here. It brings a self administered, once weekly subcutaneous option that aims to cut treatment time and ease hospital load compared with IV infusions. For Eisai, this can influence how efficiently it uses sales forces, infusion infrastructure and patient support resources in its home market.
Operationally, weekly injections at home can make initiation and continuation less dependent on infusion capacity. This ties into the main catalyst for the stock: broader access to Leqembi. It also interacts with the central risk. If healthcare systems push back on pricing while expecting easier access and more monitoring for ARIA, Eisai must execute cleanly to manage margins and support further rollout.
Eisai's current analyst narrative points to forecast 2029 revenues of ¥965.8b and earnings of ¥66.4b, built on assumed yearly top line growth of 5.4% and an earnings uplift of ¥27.8b from earnings today of ¥38.6b.
Uncover why Eisai's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
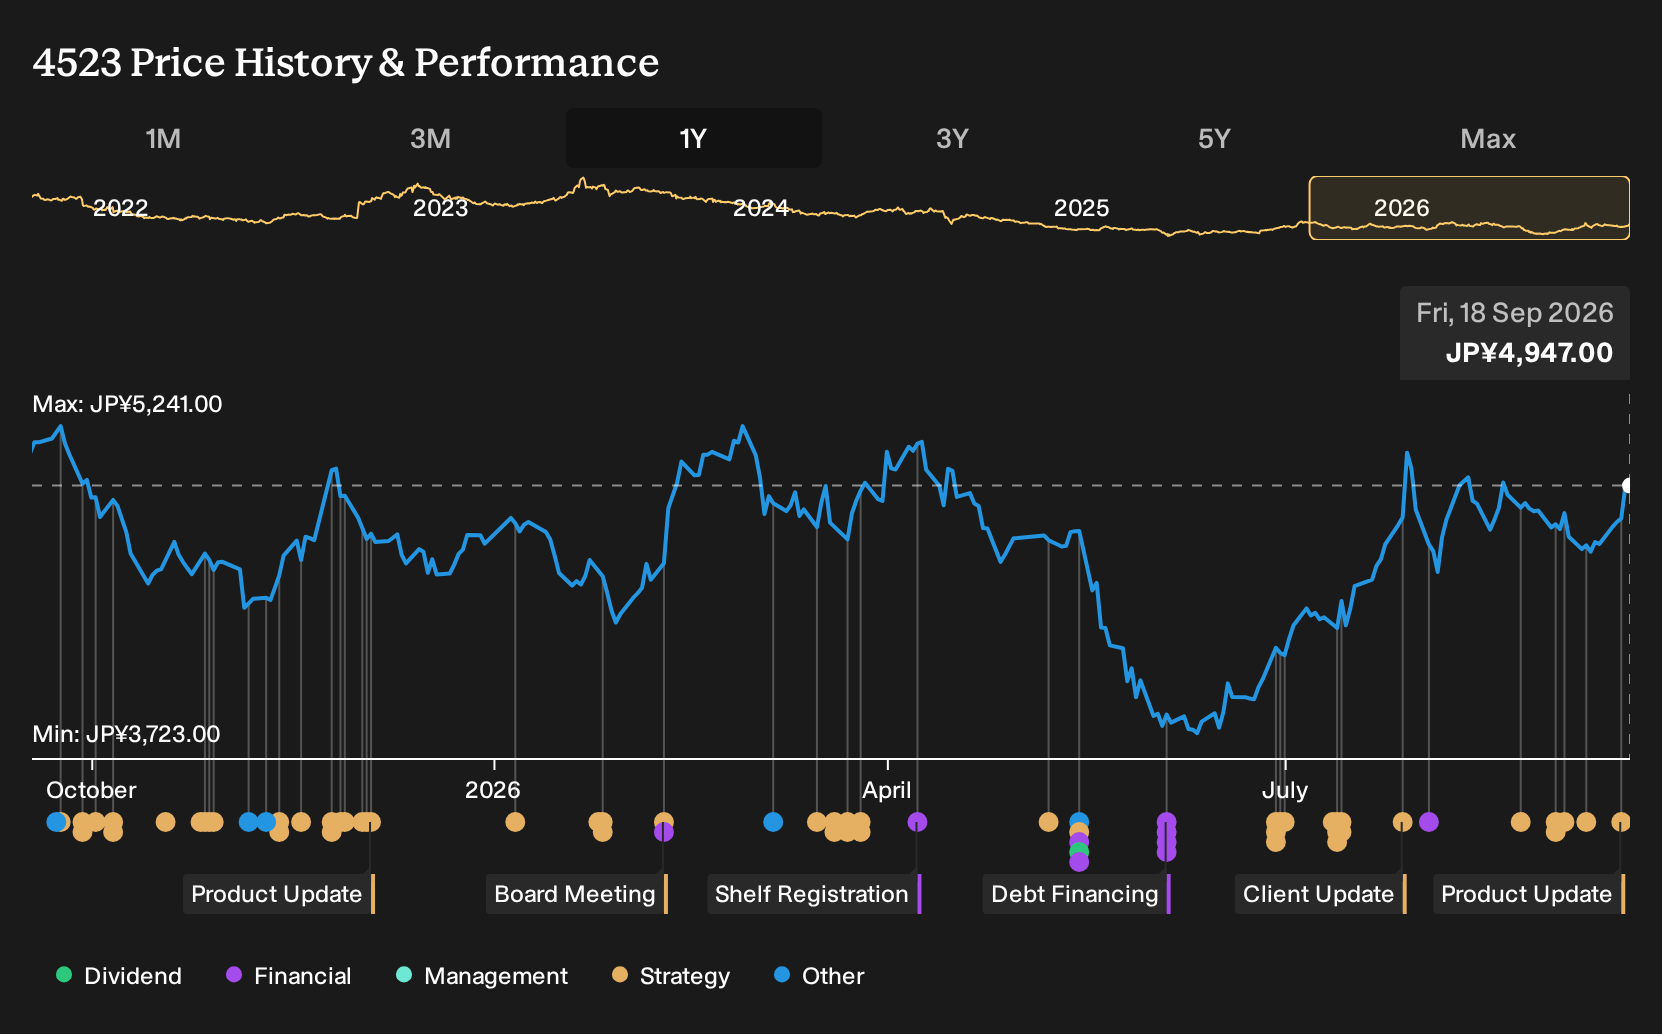
Exploring Other Perspectives
One alternate view on Eisai leans heavily on pricing risk. The most cautious analysts were only penciling in 2029 earnings of ¥43.6b on revenue of ¥829.6b, with a price target around ¥3,200. That is far below the consensus story you saw earlier. As this new Leqembi Pen approval settles in, those assumptions may shift. It therefore helps to compare both narratives yourself.
Explore 2 other Eisai fair value estimates, including one that suggests there could be as much as 9% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eisai research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eisai. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eisai's overall financial health at a glance.
Looking For More Investment Ideas Beyond Eisai?
Once you have a view on Eisai, it can help to broaden the watchlist with other opportunities that fit different roles in your portfolio, from potential mispricing to resilience or income.
- If you want to focus on value and quality together, start with companies that pass strict balance sheet and fundamentals checks using the list of solid balance sheet and fundamentals (20 results).
- For those searching for mispriced opportunities with room for a better entry point, scan through our collection of 17 high quality undervalued stocks and see which ones deserve a closer look next.
- Income oriented investors who care about stability as much as yield can target potential "paycheck" stocks by screening for 14 dividend fortresses that meet your own risk tolerance and return needs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com