
Brinker Stock Buyback Plan Resets The Long Term Bull Case
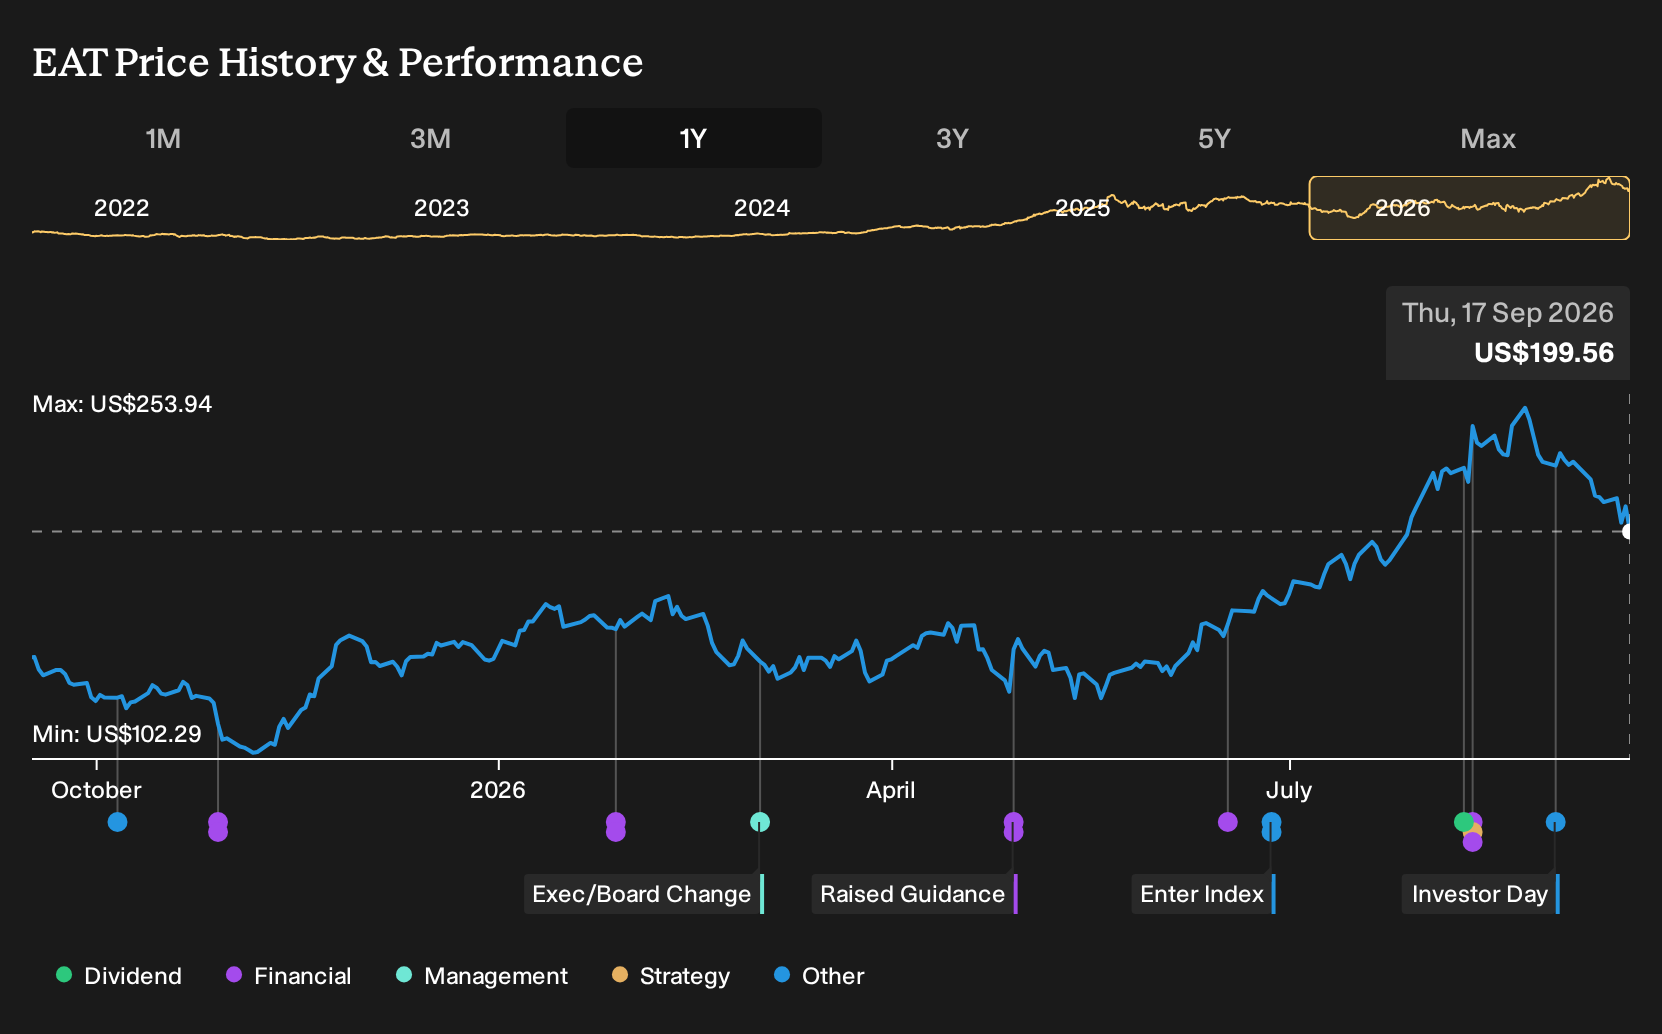
- Brinker International recently outlined long-term goals at its 2026 Investor Day, highlighting efficiency efforts, debt reduction plans, and a targeted US$400 million in share repurchases for fiscal 2026.
- The new multiyear framework ties menu, operations, and digital upgrades directly to capital returns, giving investors a clearer link between Chili’s turnaround work and Brinker International’s commitment to ongoing buybacks through fiscal 2029.
- The next step is to assess how Brinker International’s refreshed capital return plans might reshape its investment narrative and its long-term expectations.
Brinker International Investment Narrative Recap
To own Brinker International, you need to believe the Chili’s and Maggiano’s refresh can keep customer traffic and margins healthy through menu work, digital ordering, and tighter operations. The recent 5.25% share price drop and short term EPS estimate revisions do not change the main near term swing factor: how consistently restaurants convert traffic into profitable checks.
The biggest immediate risk still sits in cost pressure and staffing. Labor inflation, food input volatility, and a dine in heavy model can squeeze profitability if value focused guests trade down or shift further to off premise options. That risk is ongoing rather than specific to this week’s move.
The clearest announcement to focus on is Brinker International’s US$400 million share repurchase target for fiscal 2026, paired with revenue growth of 8% in that year and an explicit plan to keep buybacks running through fiscal 2029. That framework ties the turnaround story directly to cash generation, leverage, and share count.
For catalysts, this buyback plan works only if the restaurants stay efficient enough to fund both debt reduction and capital returns without overstretching a balance sheet that already carries a high level of debt. Execution on data driven efficiency, digital initiatives, and menu mix will likely matter more for the story than short term stock volatility.
Brinker International's narrative projects US$6.7b revenue and US$588.6 million earnings by 2029. This assumes 5.0% yearly revenue growth and an earnings increase of about US$101.6 million from US$487.0 million today.
Uncover why Brinker International's fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Brinker International analysts lean hard into a different risk. They worry that slower 4.1% revenue growth and earnings of about US$545.1 million by 2029 point to pressure from health focused, fast casual rivals. Those forecasts were set before this buyback news. Opinions may change as new data is released.
Explore 2 other Brinker International fair value estimates, including one that suggests as much as 10% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Brinker International research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Brinker International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brinker International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Brinker International?
If the refreshed Brinker International story has you thinking about portfolio upgrades, it can help to line it up against other stocks that match different goals, from income resilience to balance sheet strength or future upside potential.
- For investors who value dependable income and want to stress test yield against quality, take a look at our screener focused on 6 dividend fortresses.
- If capital preservation and steadier risk profiles matter most to you, filter the market using the screener that highlights 30 resilient stocks with low risk scores.
- For those hunting for future leaders that are still under the radar, the screener built around 16 high quality undiscovered gems can surface ideas that the wider market may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com