
Salesforce (CRM) Stock Looks Undervalued As It Jumps 24% In A Month
Salesforce has just delivered a sharp 23.8% gain over the past month, which puts fresh attention on whether the current share price lines up with what its earnings can reasonably support. With the stock last closing at US$242.85, investors are asking how much of the recent AI and product news is already embedded in that earnings picture.
- The 23.8% rise over the past 30 days puts recent optimism under the microscope and raises the bar for what Salesforce’s earnings need to justify.
- New AI products such as the Koa reasoning model and the AIforce platform, together with acquisitions like Fin, can shape expectations for future profitability and the timing of cash generation that underpins earnings based valuation work.
- There is a second opinion on Salesforce worth weighing. See what analysts think Salesforce's shares could be worth.
The stock's next move may depend on whether Salesforce’s current earnings profile is strong enough to support today’s valuation after this recent run.
AI headlines can move Salesforce quickly. If you want a broader starting point for research, consider a focused screen of 89 AI infrastructure stocks.
Is Salesforce Still Cheap on Earnings?
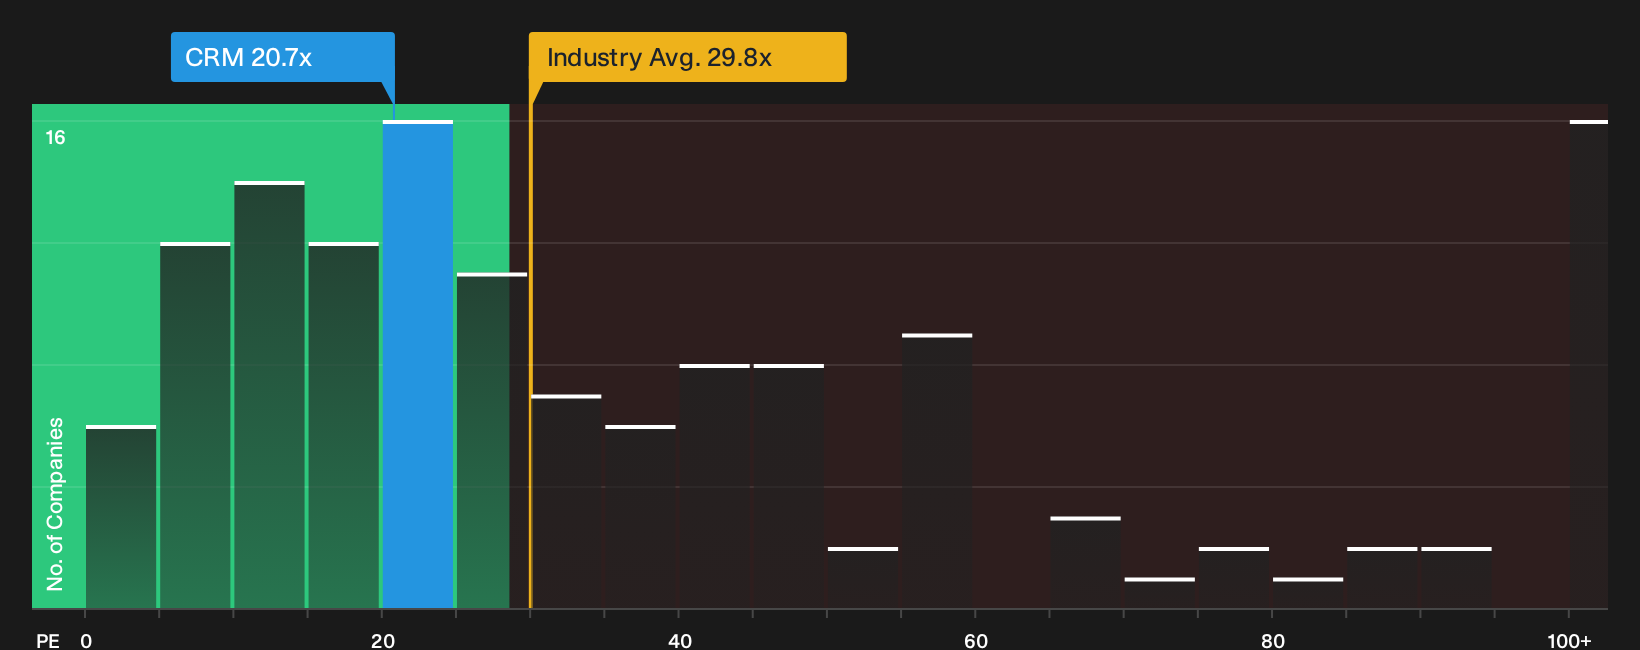
The P/E ratio fits Salesforce because earnings remain a key reference point for a mature software platform that still invests heavily in new products like Koa and AIforce. On this lens, Salesforce trades on a P/E of 20.7x, compared with a broader software industry average of 29.8x and a peer group around 39.0x. That places the stock at a discount to both the wider sector and closer peers that investors often treat as its reference set.
The fair multiple that reflects Salesforce’s size, margins and sector risk sits above the current 20.7x, so the stock appears undervalued on this framework. Because the recent AI announcements are already visible in headlines and in the price, that discount suggests the market is not fully aligning Salesforce with higher rated software and AI platforms on earnings yet. Despite the Koa launch with NVIDIA and the broader AIforce push raising the profile of its AI efforts, the P/E still comes in below what this valuation model implies could be justified. Explore the numbers behind Salesforce's P/E valuation.
The Salesforce Narrative: What Would Justify Today's Price?
Salesforce Narratives on Simply Wall St pick up where the P/E puzzle leaves off by explaining which combinations of future growth, profitability and earnings power would need to occur for the stock to be worth materially more or less than it is today. Each narrative links its number to a clear stance on how Salesforce's revenue profile, margins and risk picture might evolve, which you can revisit as fresh results and product updates are released.
Salesforce draws two very different community readouts today, with one group leaning into the AI ramp and another fixated on execution and cRPO strain.
Bull case: 12% undervalued
"Salesforce's ongoing integration of AI and agent-based automation (Agentforce, Data Cloud) into its product suite is driving rapid adoption, evidenced by 40% of new agentic bookings coming from existing customers expanding usage…"
Discover why this Narrative puts Salesforce at 12% undervalued.
Bear case: 52% overvalued
"The growing maturity of the core CRM and workflow automation market means Salesforce faces obstructed organic growth and greater dependence on expensive, high-risk acquisitions to sustain headline revenue growth…"
Explore why this Narrative puts Salesforce at 52% overvalued.
Salesforce’s valuation is only half the puzzle
Price and earnings tell you what the market thinks of Salesforce today, but the people choosing priorities, incentives and trade offs on your behalf can tilt the whole risk reward profile. See who runs Salesforce and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com