
Is Airbnb (ABNB) Still Trading At A Discount After New Housing Moves?
Airbnb has delivered a 32.2% gain over the past year, even after recent share price weakness. This puts a fresh spotlight on a simple question for investors: Is the current US$165.93 price tag adequately supported by the cash the business is expected to generate over time?
- The 32.2% one year return has materially changed the entry price for new buyers. The key issue is whether that move matches the strength and durability of Airbnb's cash flows.
- The new US$250m Housing Accelerator fund and potential EU rental restrictions both touch Airbnb's core model, which can influence how quickly cash flows arrive and how much capital the company may need to commit to housing related initiatives.
- Prefer to judge Airbnb on earnings? See why Airbnb's 36.4x P/E tells a different valuation story.
The issue now is whether Airbnb's current share price is in line with what its cash flows suggest when run through a Discounted Cash Flow (DCF) lens.
If you are weighing whether Airbnb's cash flows justify its current price, you might also want to scan a wider field of companies using our screener of 29 high quality undervalued stocks
Is Airbnb a Bargain on Cash Flow?
The Discounted Cash Flow model used here takes Airbnb’s expected future cash generation and brings it back to today’s dollars. In this view, the business is being judged on the cash it can return to shareholders over time rather than on near term headlines.
Airbnb is currently producing last twelve month free cash flow of about $4.9b, and the 2 Stage Free Cash Flow to Equity model assumes this owner earnings base continues growing over the coming decade. Those projections reach into the $8.4b range by 2030 before a slower second stage, which is more in line with a mature platform that is still expanding rather than a cash hungry early stage venture.
The DCF output suggests Airbnb’s estimated intrinsic value sits substantially above the current US$165.93 share price. The new $250m Housing Accelerator fund, while it means extra capital is earmarked for housing projects, effectively treats that spending as part of the cash flow story rather than a side bet. This helps explain why the model can still see a gap between value and price. Find out what Airbnb could be worth using our Discounted Cash Flow (DCF) estimate.
The Airbnb Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle leaves off for Airbnb by mapping out which combinations of future growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than today's quote on the Community page. Each Narrative treats Airbnb's implied fair value as a thesis about the business that can be tracked over time, so you can see how the underlying story holds up as new information arrives.
On Airbnb, the community split is less about extremes and more about how much upside is left from here.
Bull case: 9% undervalued
"They’ve launched long-term rentals, made over 500 product improvements, and are going all in on AI to make the platform smoother..."
Discover why this Narrative puts Airbnb at 9% undervalued.
Bear case: roughly fairly valued
"Major cities have introduced regulations limiting short-term rentals, capping listings, or imposing compliance requirements on hosts..."
Explore why this Narrative puts Airbnb at roughly fairly valued.
One more piece of the Airbnb story worth checking
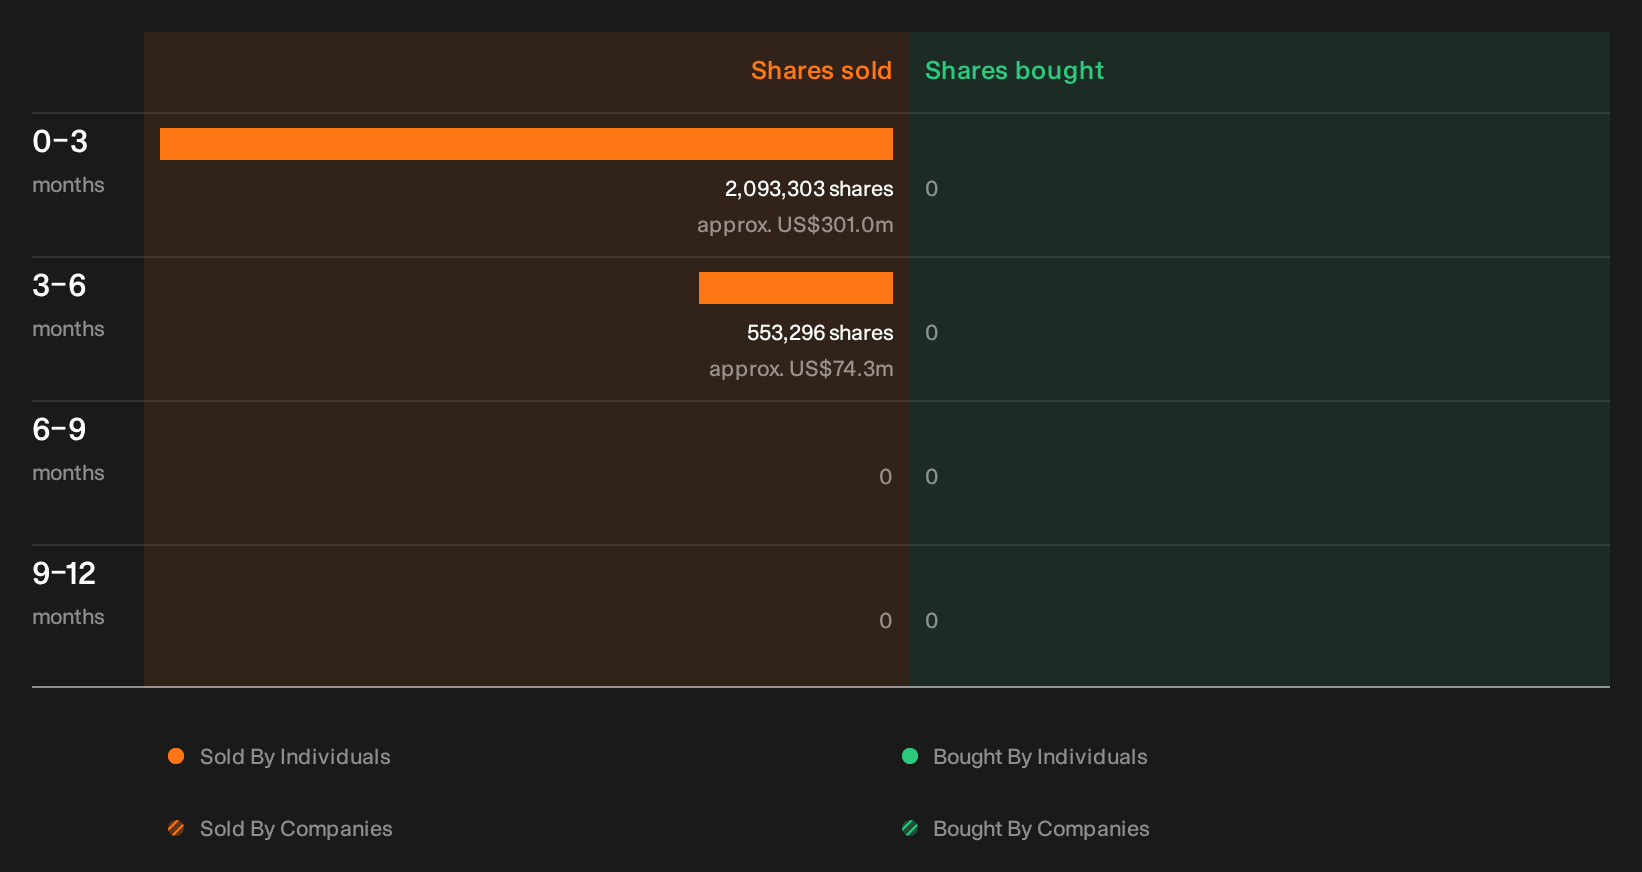
Before closing the book on Airbnb, it is worth knowing that recent trading by people inside the business has been flagged by our checks, and the sellers, sizes and possible signals are all there for you to review. See the recent insider selling flagged for Airbnb.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com