
Dave (DAVE) Shares Moved, So What Is Driving Attention Now?
Attention on Dave (DAVE) has picked up as investors focus on the upcoming CashAI v5.5 rollout, which is expected to influence credit performance, advance sizes, loss rates, and overall profitability for the platform.
Recent trading reflects that optimism. Dave’s 1 month share price return of 7.01% and 90 day share price return of 13.37% sit alongside a 62.42% year to date share price gain, while the 3 year total shareholder return is very large, which points to strong momentum built over several years.
Scan what other fintech and AI powered credit platforms are doing by comparing Dave’s setup with a hand picked group of 16 high quality undiscovered gems that may be flying under most radars.
The recent surge in Dave raises a simple tension. Has the CashAI v5.5 story already been priced in, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 18% Undervalued
On the most followed view of Dave, the fair value estimate of $436.58 sits well above the last close of $356.49, so the current CashAI v5.5 optimism is being measured directly against a richer earnings path and lower discount rate assumptions.
Anticipated gains from CashAI v5.5, which leverages deeper transaction data analytics and more variables for risk segmentation, are likely to improve credit performance, enable larger and more frequent ExtraCash advances, and reduce credit losses, thereby supporting higher net margins and gross profit.
See why 44 investors see Dave as 18% undervalued.
Result: Fair Value of $436.58 (UNDERVALUED)
Still, the Dave story can be knocked off course if regulators clamp down on fee-based products, or if rising competition forces higher marketing spend and weaker unit economics.
Find out about the key risks to this Dave narrative.
Another View: Dave’s P/E Signals A Richer Price
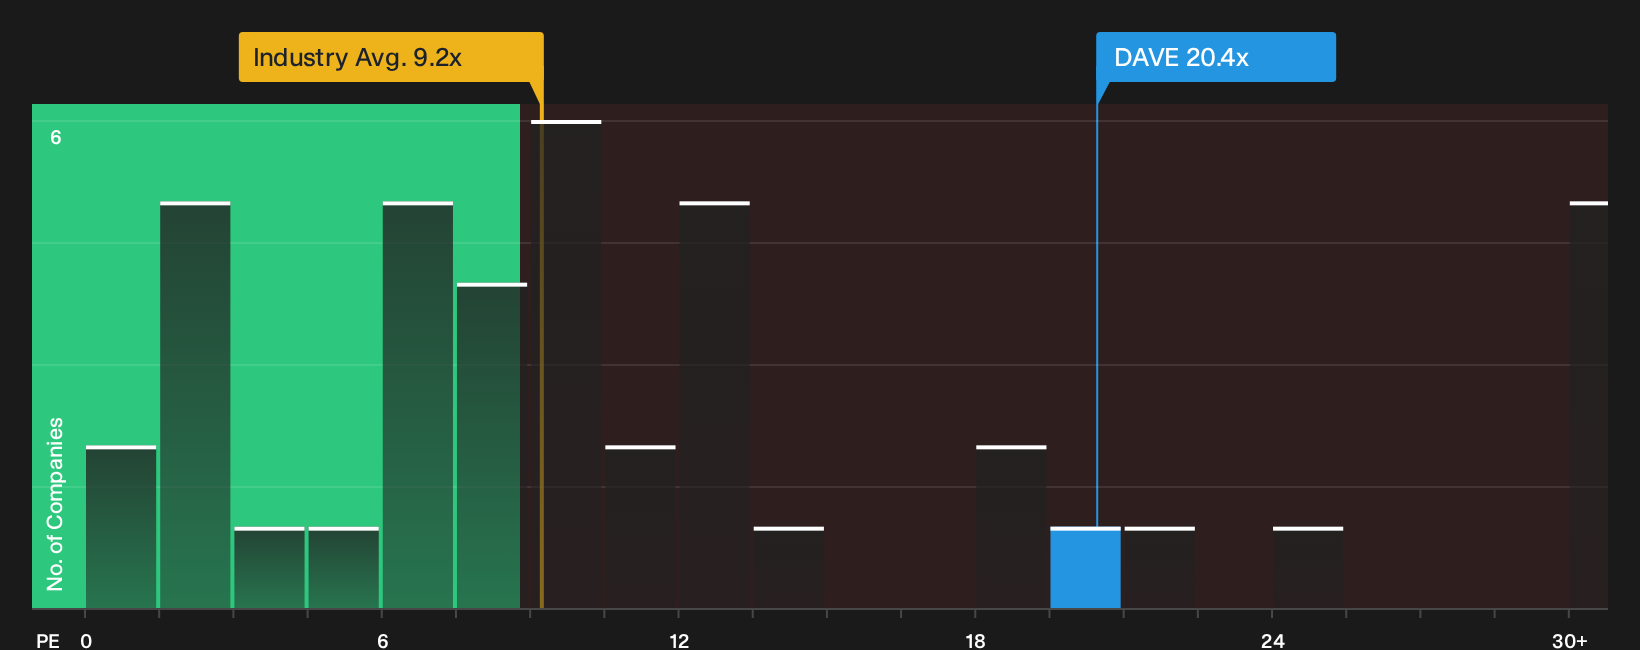
The first valuation narrative paints Dave as 18% undervalued against a fair value of $436.58. A simple cross check using the P/E ratio tells a different story. Dave trades on 20.4x earnings, which is higher than both the US Consumer Finance sector at 9.2x and its peer group at 18.5x. Yet that same figure sits just under an estimated fair ratio of 21.9x, so the market is already pricing in strong execution with only a small cushion. The key question is whether you are comfortable paying close to that fair ratio for a business so tied to fee based lending and higher risk funding.
For a closer look at how these earnings multiples stack up against detailed valuation work, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sense that the Dave story is skewing bullish so far and want to test that for yourself before the crowd moves on? Take a closer look at the full set of potential bright spots through the 3 key rewards.
Looking for more investing ideas beyond Dave?
Do not stop with Dave if you want a fuller watchlist. Fresh ideas often show up where other investors are not looking yet, and that is where edges start.
- Target resilience by focusing on businesses with strong cash buffers and healthy debt profiles through the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispricings by scanning companies that combine quality fundamentals with lower valuations using the 29 high quality undervalued stocks.
- Prioritize stability and income by zeroing in on companies offering higher yields and sturdy payout records through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com