
Does Earnings Turnaround Change The Bull Case For Westlake (WLK)?
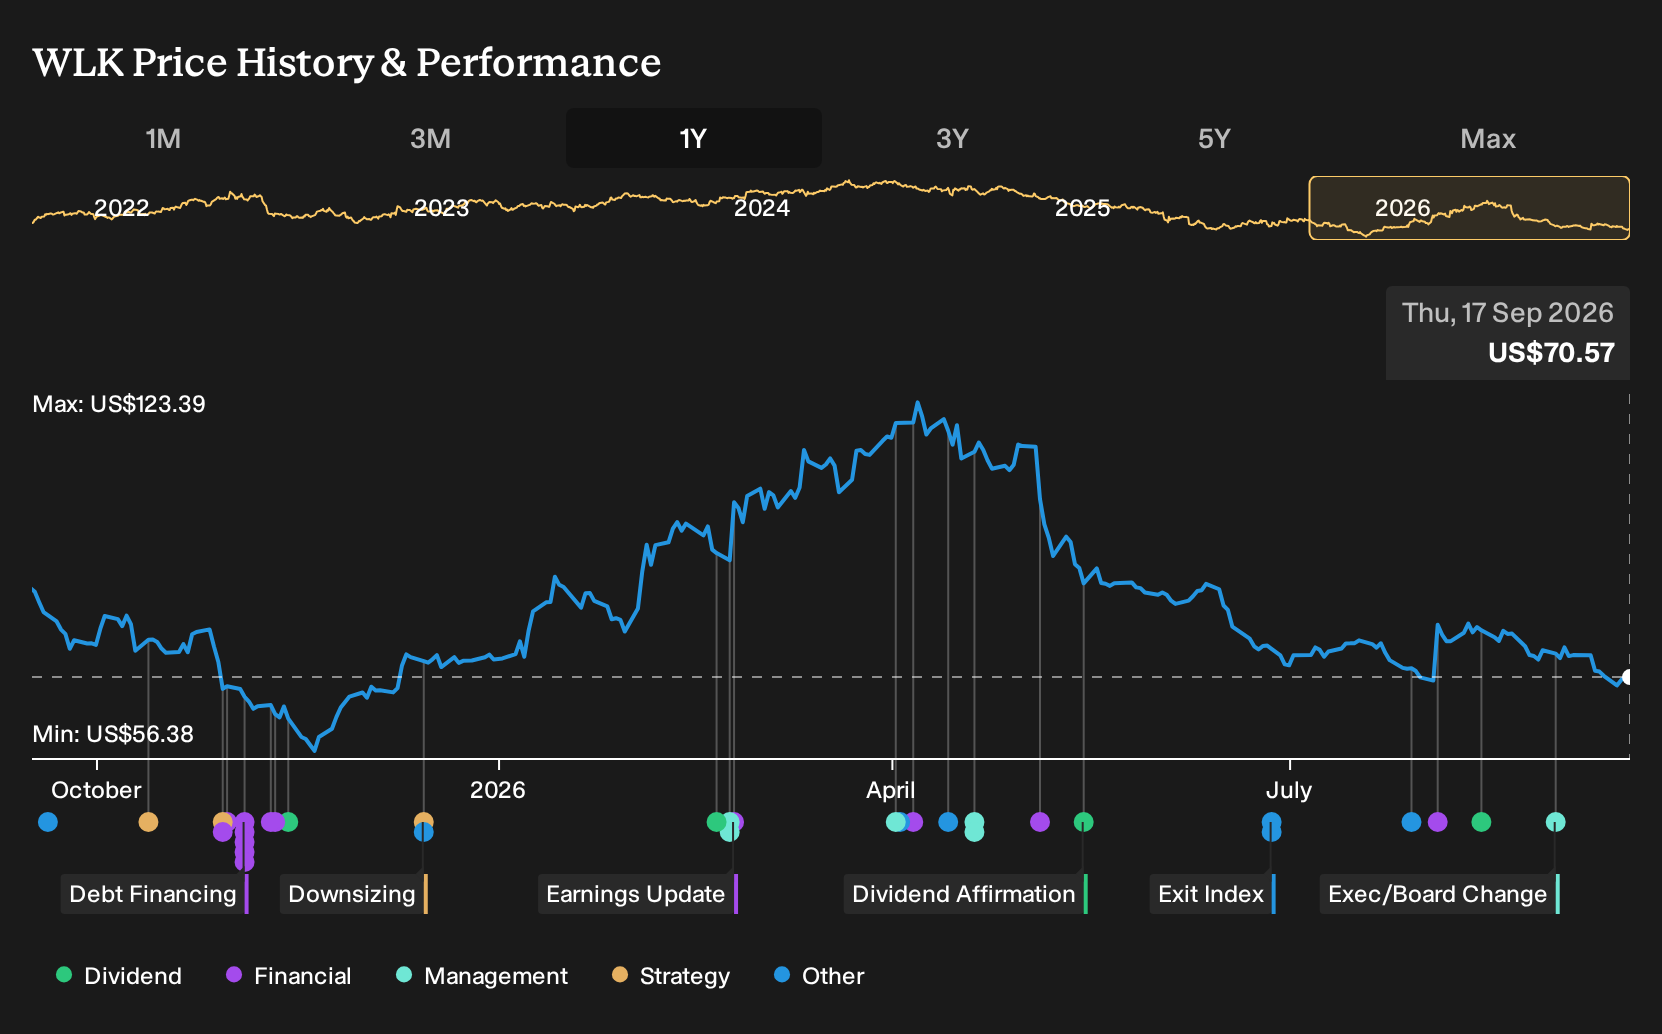
- Westlake Corporation reported a second quarter turnaround, generating net income of US$260 million and shifting its Performance and Essential Materials segment from a US$318 million operating loss to US$185 million in operating income, supported by a 14% year over year rise in average sales prices.
- The group also reduced debt by US$500 million and returned US$99 million through dividends and buybacks, which highlights how Westlake is using the earnings recovery to clean up its balance sheet while still sharing cash with investors.
- We will now look at how Westlake's investment narrative could be influenced by this earnings rebound and balance sheet progress.
Scan how Westlake's recovery compares with other cash generative, balance sheet focused companies using our hand picked screener of list of solid balance sheet and fundamentals (23 results).
Westlake Investment Narrative Recap
To own Westlake, you need to believe the chemicals cycle and construction demand can support a healthier earnings base across both Performance and Essential Materials and Housing and Infrastructure Products. The latest quarter showed a swing back to profit, with pricing helping PEM, which gives some near term validation that the cost work and footprint changes are gaining traction.
The key short term catalyst is whether this earnings rebound can hold as global supply, energy costs, and industrial demand remain mixed. The biggest risk is that pricing pressure in core chemical chains and higher feedstock costs return, which could quickly compress margins again and keep asset utilization weaker than investors might like.
The second quarter update matters most because it intersects directly with Westlake's cost reduction and footprint plans in PEM and the long running push to lean on more stable Housing and Infrastructure Products demand. Management reported US$500 million of debt reduction alongside US$99 million of dividends and buybacks, so free cash flow is clearly being directed at both balance sheet repair and shareholder returns.
For you as an investor, that combination makes execution on further cost saves and capacity discipline especially important. If global oversupply in chemicals persists or energy costs rise again, sustaining the dividend and continuing buybacks could conflict with funding ongoing restructuring and growth projects. This keeps capital allocation a central catalyst and risk to watch from here.
Westlake's narrative projects US$12.8b revenue and US$710.2 million earnings by 2029. This implies 4.3% yearly revenue growth and an earnings increase of about US$1.9b from current earnings of a US$1.2b loss.
Uncover why Westlake's fair value indicates a 33% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some analysts saw Westlake very differently before this quarter. The most bearish group expected revenue to reach about US$12.0b by 2029 and earnings of only US$223.0 million, with PEM margins stuck near low single digits. That is a far more cautious story. Use this update to test which narrative you find more convincing.
Explore 2 other Westlake fair value estimates, including one that suggests as much as 31% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Westlake research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Westlake. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Westlake's overall financial profile at a glance.
Looking for more Westlake style investment ideas?
If the Westlake story has sharpened your thinking about balance sheets, earnings power, and capital discipline, use that same framework to hunt for other opportunities on the Simply Wall St Screener. It is an efficient way to surface stocks that fit the specific risk and return profile you care about, rather than scrolling through tickers at random.
- For investors who want potential mispricing with solid fundamentals, consider a curated set of opportunities in our 29 high quality undervalued stocks.
- If consistent income is your focus, use the tool that highlights companies with stronger yields and financial resilience through our 6 dividend fortresses.
- If you prefer to keep risk in check while still staying in the market, then filter for steadier operators using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com