
Learn Why The Bull Case For Ambarella (AMBA) Could Change Following Developer Zone Expansion
- Ambarella expanded its Developer Zone, adding a Google Cloud hosted IDE, Gemini Enterprise powered agentic AI tools, and deeper ties with ZEDEDA and Ultralytics to support cloud connected fleets of CVflow based edge devices.
- The build once, deploy across 12 AI SoC families approach, spanning more than 200 supported model architectures and 50 million units in the field, points to a software style scale story layered on top of Ambarella’s chip base.
- The next area of focus is how Ambarella’s expanded cloud to edge developer platform could reshape the existing AI centric investment narrative.
Ambarella Investment Narrative Recap
To own Ambarella, an investor needs to believe that demand for AI at the edge will keep expanding and that its unified CVflow and Cooper software platform can turn that interest into recurring design wins across IoT, automotive and industrial uses. The latest Developer Zone expansion reinforces this cloud to edge story but does not change the reality that the business remains unprofitable and heavily tied to cyclical IoT spending.
The near term catalyst still sits in evidence that edge AI SoCs and software tools can lift revenue while controlling operating costs. The biggest risk is that IoT centric demand, customer concentration and rising R&D spend outpace realized design wins, which would keep margins under pressure and delay any path toward sustained profitability.
The ZEDEDA partnership announced alongside the Developer Zone update feels most relevant to this moment. Running EVE OS on Ambarella N1 devices and orchestrating workloads through ZEDEDA’s Edge Intelligence Platform gives enterprises one control plane for deploying and updating models across fleets, which ties directly into the cloud hosted IDE and live device testing story.
For catalysts, that combination creates a more complete operational stack from cloud based development to field deployment and lifecycle management. Execution risk remains material, since Ambarella still needs customers to scale from pilots to large fleets and to absorb the higher costs of AI SoCs while the company manages margin pressure, competitive chips and its reliance on IoT heavy end markets.
What The Ambarella Consensus Is Pricing In
Ambarella's narrative projects US$666.1 million in revenue and US$132.3 million in earnings by 2029. That setup assumes 16.8% yearly revenue growth and an earnings improvement of about US$188.6 million from a loss of US$56.3 million today.
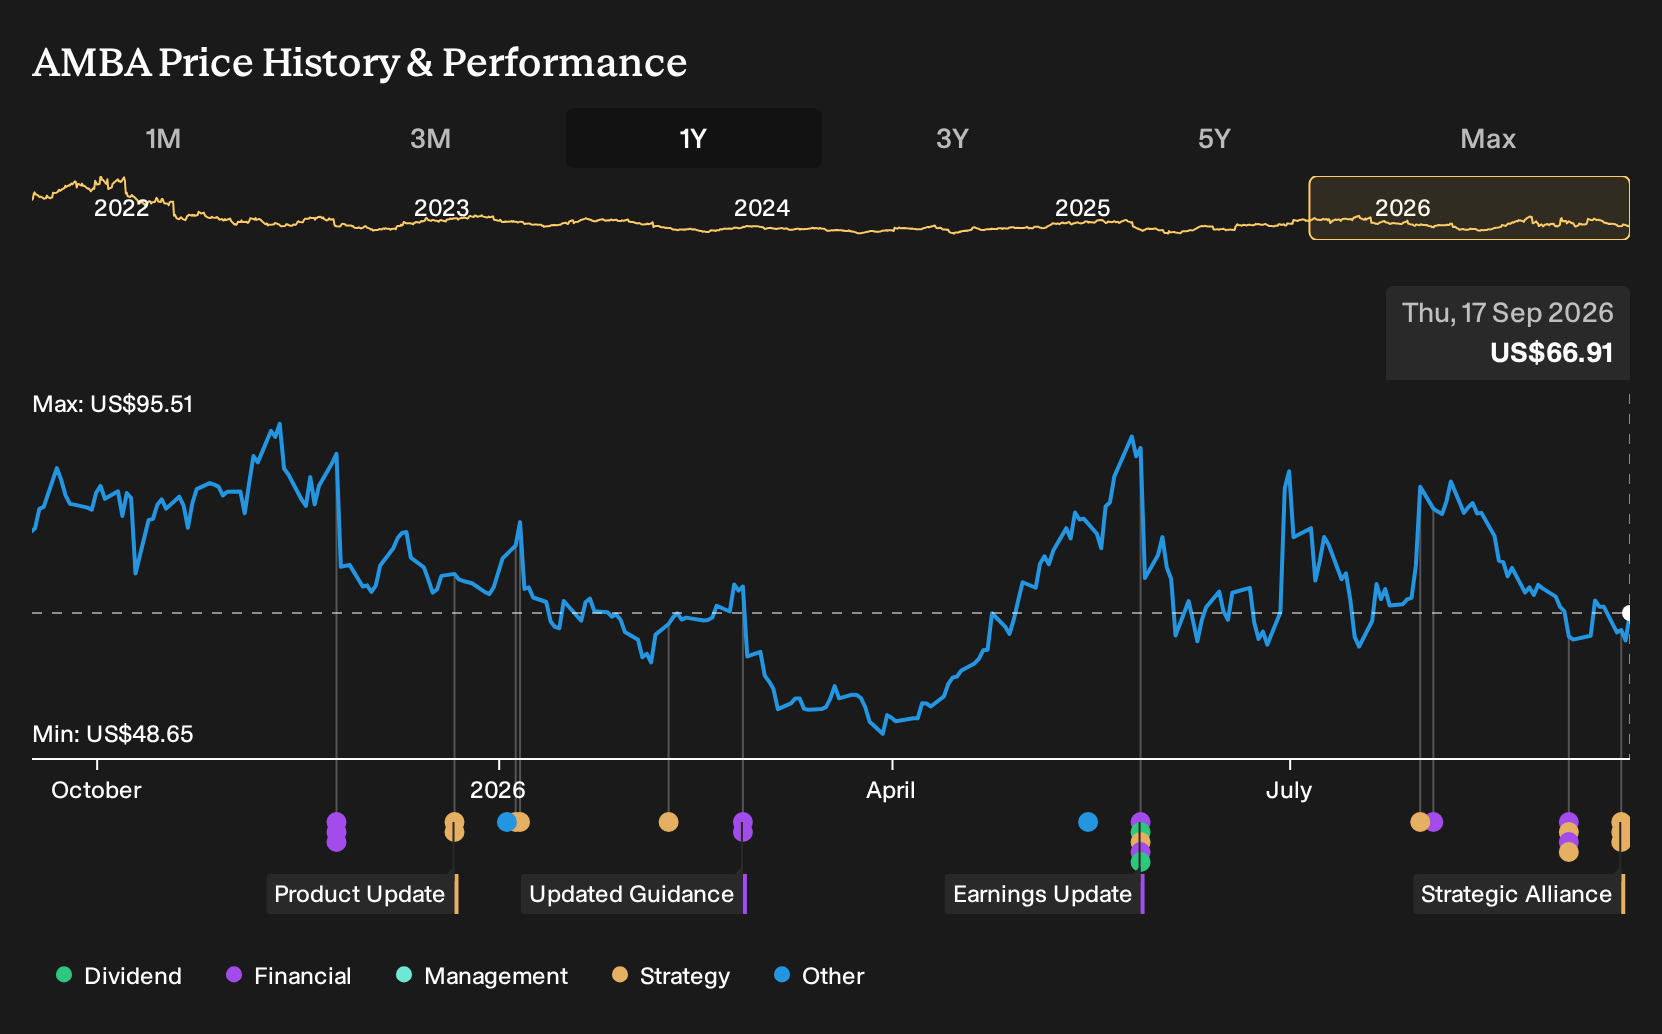
Uncover why Ambarella's fair value indicates a 34% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One optimistic twist in the alternate Ambarella story is how quickly some analysts think the unified platform could snowball. Before this news, the most upbeat forecasts already assumed revenue of about US$650.0 million and earnings of roughly US$109.7 million by 2029 on a 70.4x P/E. You can treat this Developer Zone update as a fresh reason to recheck those expectations, as well as compare several viewpoints side by side.
Explore 5 other Ambarella fair value estimates, including one that suggests there could be as much as 77% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ambarella research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ambarella. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ambarella's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ambarella?
If the Ambarella story has you thinking about where else AI, cash flow quality, or balance sheet strength could matter, it can help to widen the lens and scan a broader list of stocks that fit clear, data driven filters.
- If resilience matters most to you, focus on businesses with steadier risk profiles by checking out 30 resilient stocks with low risk scores that might appeal if you want fewer surprises along the way.
- If value is your starting point, look across a curated universe of companies that pair fundamentals with pricing that screens as attractive by reviewing 29 high quality undervalued stocks that meet those criteria.
- If you want something less crowded, concentrate on quality that has not yet drawn as much attention by scanning a targeted 16 high quality undiscovered gems that could sit earlier in their recognition cycle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com