
Does Earnings Guidance Change The Bull Case For Camtek Stock (CAMT)?
- Camtek has been drawing attention ahead of its upcoming earnings release, with analysts projecting Q3 2026 EPS of US$0.98 and the business guiding to about 20% sequential revenue growth supported by demand for its Hawk and Eagle G5 inspection platforms tied to AI and high bandwidth memory workflows.
- The focus on advanced packaging inspection and metrology for AI and high performance computing applications highlights how Camtek’s core equipment portfolio is being pulled into structurally higher value chipmaking steps. This development could influence how investors think about the durability of its order pipeline and product mix.
- This article will examine how Camtek’s investment narrative is shaped by this Q3 revenue guidance linked to AI-oriented demand.
Scan beyond Camtek and line up other AI hardware beneficiaries by using our hand-picked screener of 89 AI infrastructure stocks that could also be gearing up for their own earnings catalysts.
Camtek Investment Narrative Recap
For Camtek, the big picture you need to buy into is that advanced packaging inspection and metrology remain central to AI and high performance computing workflows for an extended period. The Q3 2026 guide for roughly 20% sequential revenue growth, supported by Hawk and Eagle G5 demand, underlines that thesis but does not remove the cyclical nature of semiconductor equipment spending.
The most immediate catalyst is the upcoming earnings release and any update on order flow tied to high bandwidth memory and chiplet programs. The largest near-term risk still sits with customer and geographic concentration. Any slowdown in AI related capex or disruption in Asian demand could quickly show up in Camtek’s backlog and near-term margins.
The earnings preview that pegs Q3 2026 EPS at US$0.98 and points to around 20% sequential revenue growth is the key disclosure to watch. It links directly to the earlier story about Hawk and Eagle G5 tools being used in AI and high bandwidth memory production, which is where investor attention is already focused.
That same update also highlights the tension in the Camtek story. Investors are watching strong AI oriented demand on one side and softer reported net profit margins of 7.4% on the other, with large one-off items in the recent past. Execution on this quarter, and what management says about the durability of AI packaging orders, will help inform how that balance is judged right now.
What The Long Range Forecasts Say About Camtek
Camtek's narrative projects US$821.7 million of revenue and US$367.0 million of earnings by 2029. That outlook assumes revenue growth of 18.1% per year and an increase in earnings of about US$319 million from US$48.1 million today.
Uncover why Camtek's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
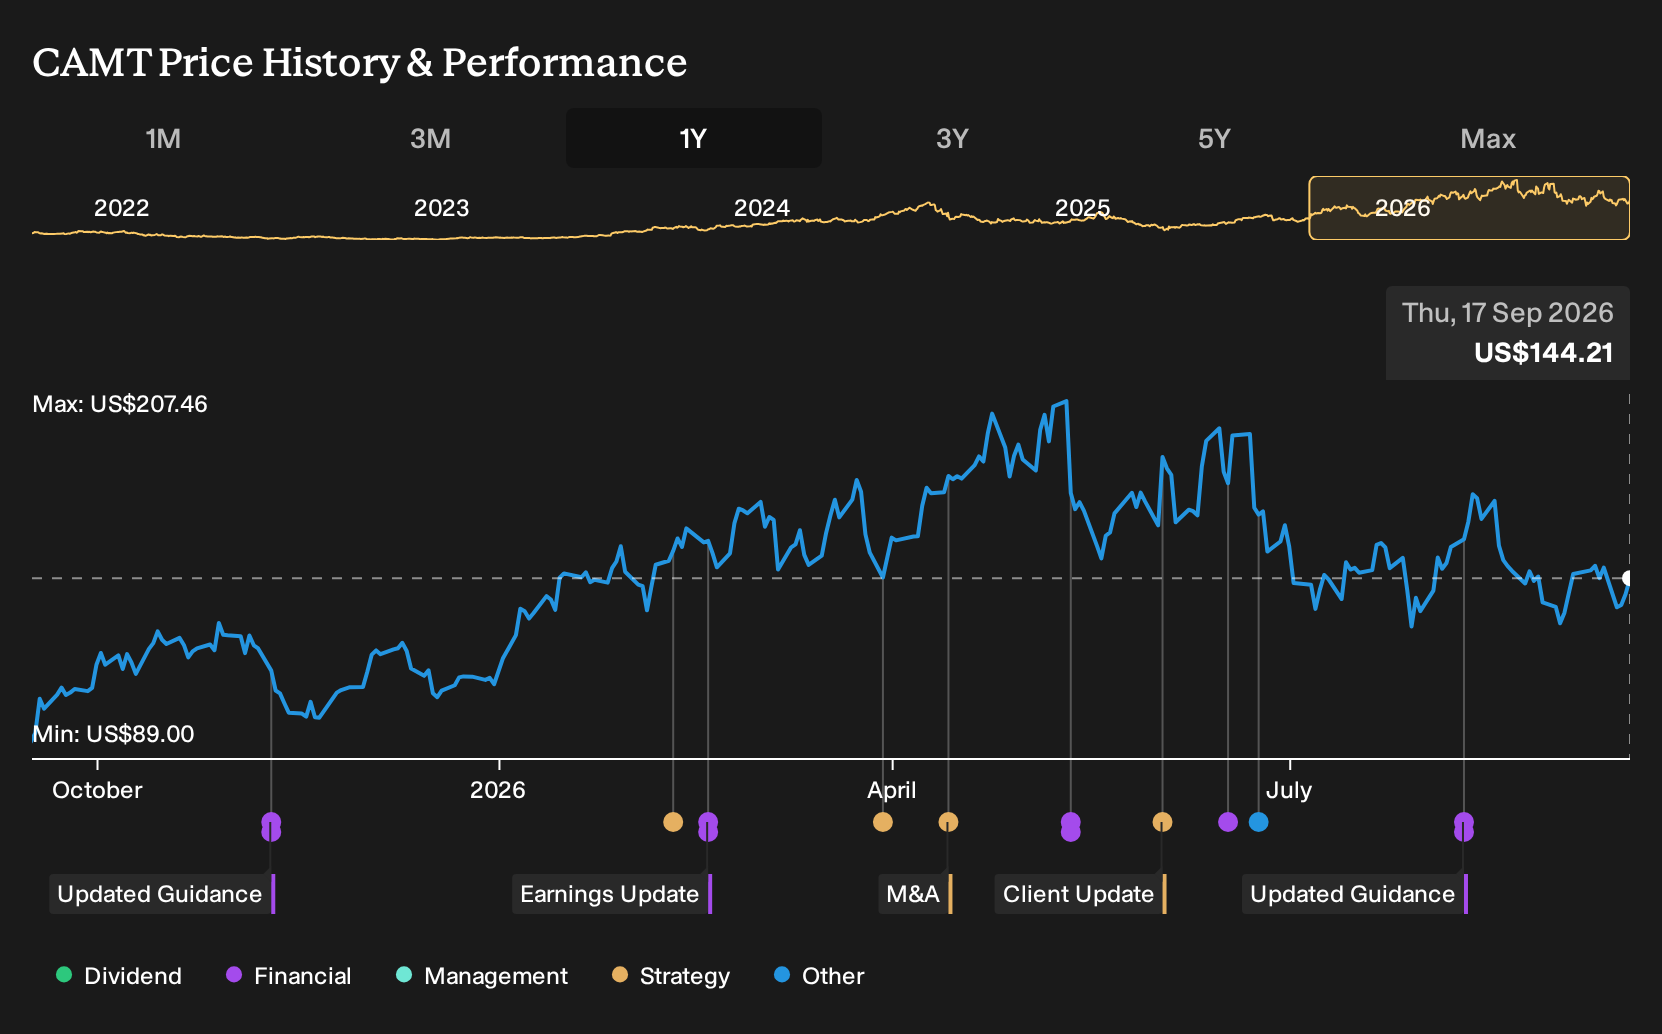
Exploring Other Perspectives
One alternate take on Camtek leans hard into pricing risk around the Hawk platform. The most bearish analysts were pencilling in around US$761.8 million of revenue and US$375.4 million of earnings by 2029, yet still landed on a US$160.0 target. That gap shows how sharply views might shift once this earnings update lands.
Explore 4 other Camtek fair value estimates, including one that suggests as much as 66% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Camtek research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Camtek. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Camtek's overall financial health at a glance.
Looking For More Investment Ideas Beyond Camtek?
Once you have formed a view on Camtek, it can help to compare that thesis against a wider set of opportunities using the Simply Wall St Screener. That way you are judging this stock against other businesses with different income profiles, balance sheets, and risk levels.
- If you want potential bargains backed by solid fundamentals, compare Camtek with a wider pool of quality candidates screened through our 29 high quality undervalued stocks.
- For investors who care most about sleep-at-night resilience, widen your watchlist to companies that show up in our 30 resilient stocks with low risk scores.
- If you are hunting for under-the-radar opportunities, weigh Camtek against a curated 16 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com