
HEICO (HEI) Highlights EPS And Cash Flow Strength, Is It Still 25% Below Fair Value?
Recent coverage around HEICO (HEI) centers on projected EPS strength, rising earnings estimates, and improving cash flow, set against an aerospace sector dealing with strong travel demand, supply bottlenecks, and fresh product launches such as VPT’s FLX Series power solution.
HEICO’s recent pullback has been sharp, with the share price down 19.44% over the past 30 days and 12.05% over 90 days. However, the 3 year total shareholder return of 84.84% and 5 year total shareholder return of 124.73% show that longer term momentum has been strong, even as near term sentiment cools around a US$296.48 price point and fresh product launches like VPT’s FLX Series reset expectations around growth and risk.
Scan for other aerospace and defense names showing strong growth profiles and recent pullbacks similar to HEICO by using our hand picked 29 high quality undervalued stocks to broaden your watchlist.
HEICO now trades around US$296, while the most followed fair value markers cluster near US$386. Is this just a stretched growth story or does the pullback leave genuine value on the table?
Most Popular Narrative: 25% Undervalued
HEICO is priced at about $296, while the most followed narrative anchors fair value near $394. The debate now turns to whether its core aerospace and electronics engines can keep underwriting that gap as the sector grapples with aging fleets and heavier traffic.
The worldwide trend of aging commercial and military aircraft fleets, combined with increasing pressure for cost-effective maintenance solutions, strongly favors HEICO's business model; as airlines and governments seek alternatives to expensive OEM parts, HEICO's FAA-approved PMA parts and repairs continue to gain market share and drive margin expansion, as reflected in rising operating and EBITA margins.
See why 25 investors see HEICO as 25% undervalued.
Result: Fair Value of $393.95 (UNDERVALUED)
Still, the HEICO story can break if OEMs squeeze PMA access, or if future acquisitions fail to integrate cleanly and start to drag on margins.
Find out about the key risks to this HEICO narrative.
Another View: HEICO Through The P/E Lens
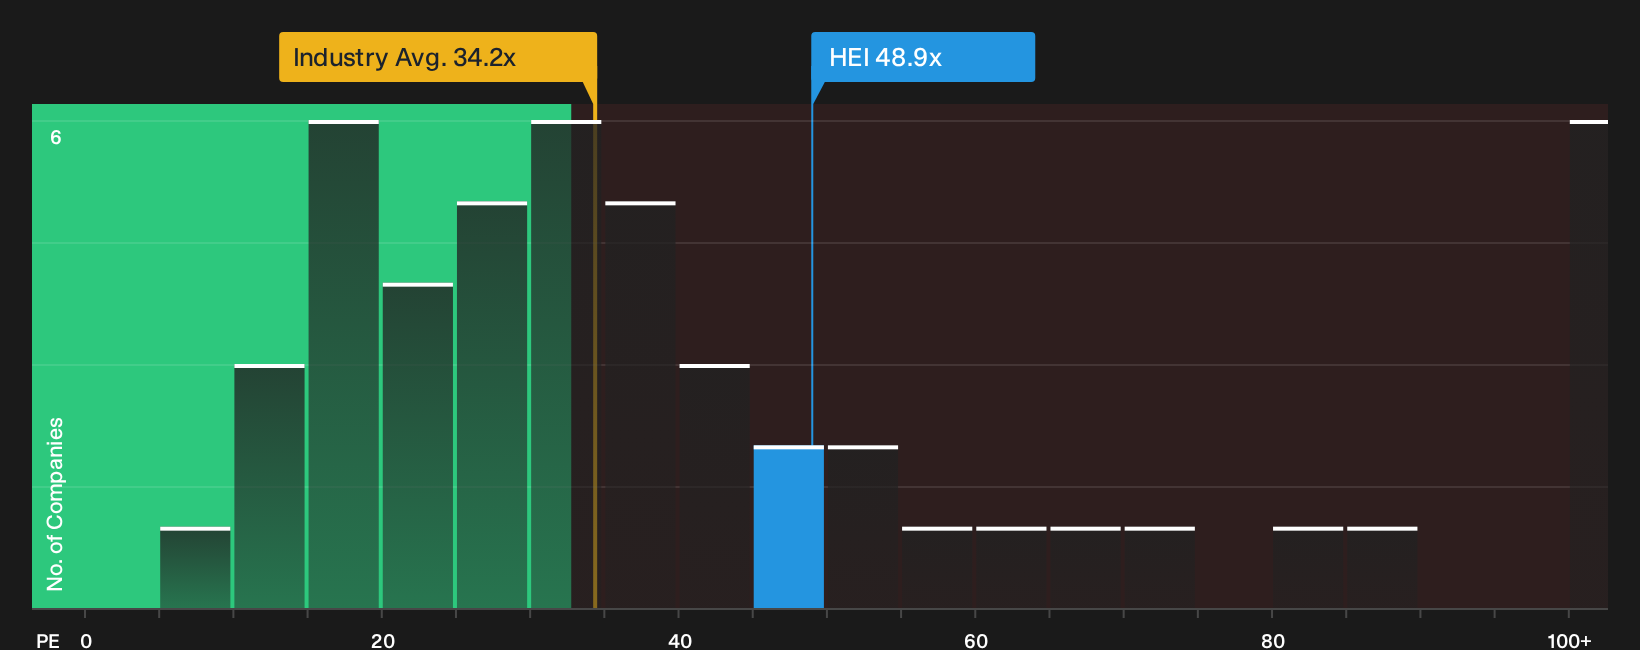
On the simple earnings multiple, HEICO is not cheap. The stock trades on a P/E of 48.9x, which is well above the US Aerospace & Defense industry at 34.2x and far ahead of the fair ratio of 27.8x that our model suggests the market could move toward over time.
Peers on average sit closer to 73.4x, so HEICO screens cheaper than similar stocks, yet still rich relative to that fair ratio benchmark. For investors weighing the 25% undervalued story, the key question is whether paying a premium now leaves enough room for error if growth or margins land closer to the middle of the range.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around HEICO invite a closer look, so move quickly, open the full data set, and weigh both sides of the story. To see the balance of concerns and potential upsides in one place, review the 4 key rewards and 1 important warning sign
Looking for more HEICO sized opportunities?
Do not stop at HEICO. Broaden your ideas list now by scanning three focused groups of stocks that could sharpen your next move.
- Target potential mispricings by reviewing companies that show strong fundamentals yet trade at a discount through the 29 high quality undervalued stocks.
- Strengthen your income stream by checking out businesses with higher yields and consistent payouts using the 6 dividend fortresses.
- Dial down portfolio risk by focusing on financially resilient businesses using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com