
How $244 Million Shelf Filing Will Impact Zenas BioPharma (ZBIO) Stock
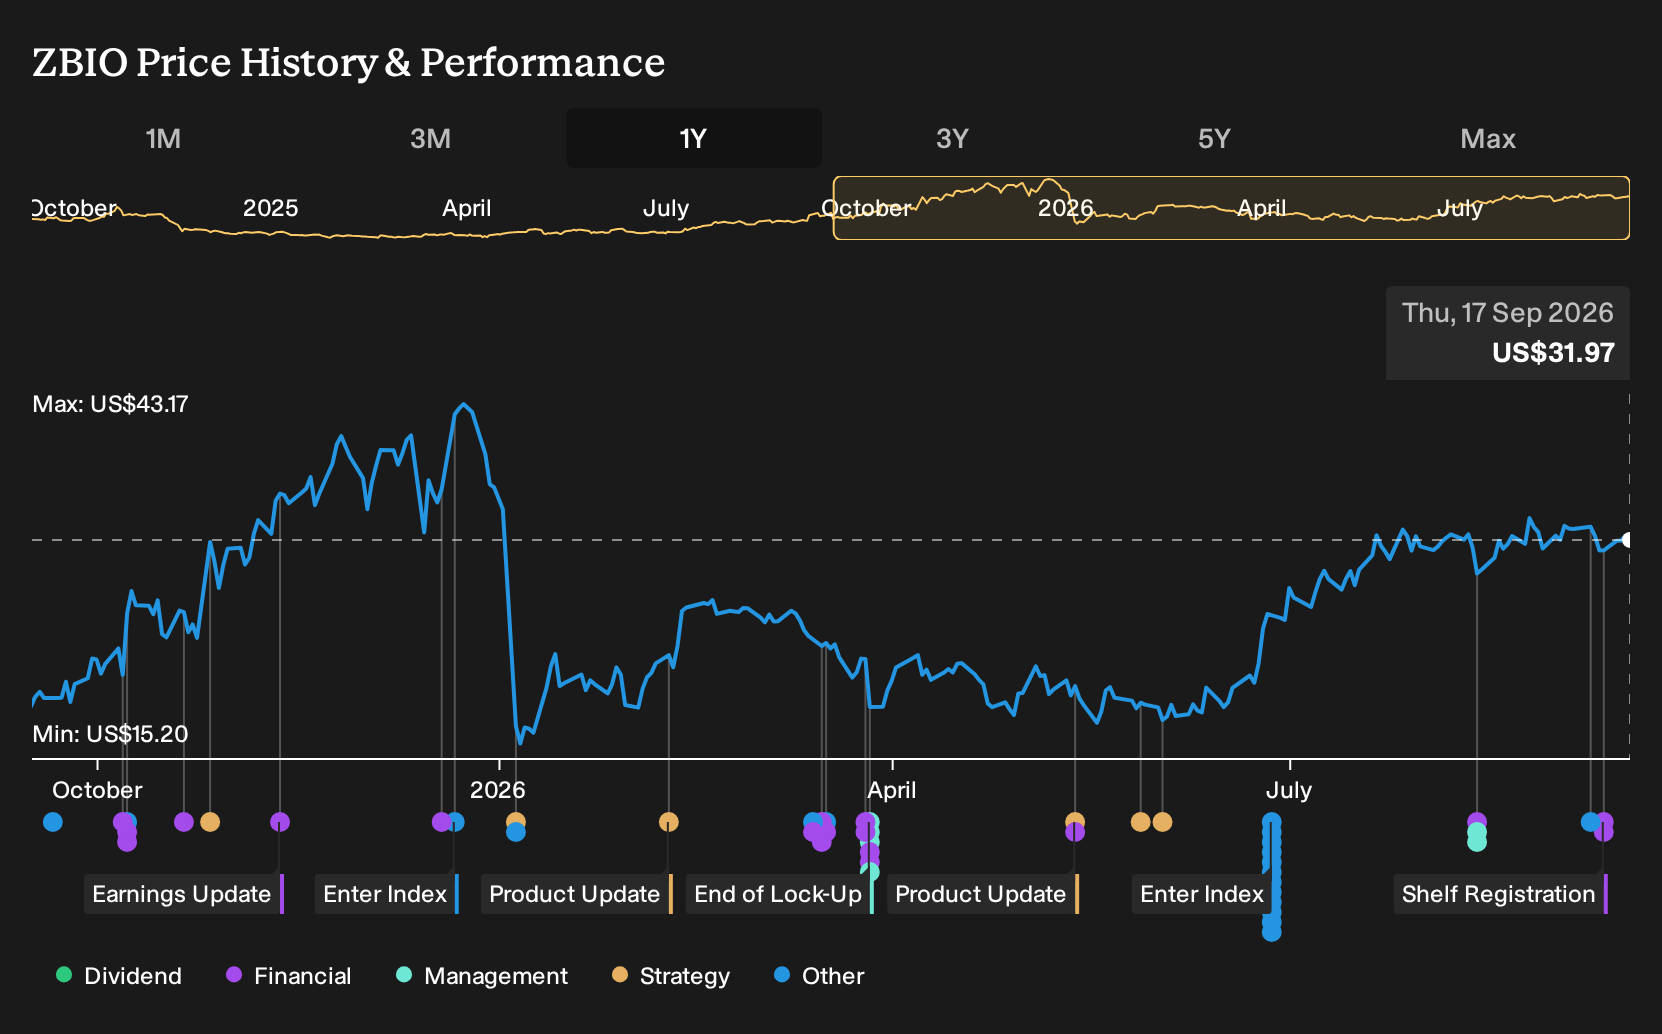
- Zenas BioPharma filed two shelf registrations on 11 September 2026 covering up to 7,600,000 common shares, totaling about $244.69 million, including an $18.66 million ESOP-related component.
- The combined size of these potential offerings highlights a meaningful focus on future funding flexibility, which could influence how investors view Zenas BioPharma’s capital needs and cost base.
- This article examines how Zenas BioPharma’s investment narrative may be affected by this large shelf capacity for future common equity issuance.
Compare how Zenas BioPharma’s funding plans stack up against other potential opportunities by scanning our hand picked 16 high quality undiscovered gems with strong fundamentals that may be flying under most investors’ radar.
What Is Zenas BioPharma's Investment Narrative?
To own Zenas BioPharma, you need to believe the immunology pipeline, led by obexelimab, can convert heavy R&D spending into commercially relevant therapies despite minimal current revenue of about US$1.0m and a reported loss of US$484.384m. The business is capital hungry and currently unprofitable, with forecasts still pointing to losses over the next three years. Recent shelf registrations, including the ESOP related component, reinforce that equity remains a core funding tool rather than cash flow from operations.
The near term story hinges on clinical execution and partner interest. The upcoming Morgan Stanley, H.C. Wainwright, and Citigroup conferences in mid September 2026 are clearly aimed at supporting this objective. The expanded shelf capacity may give Zenas BioPharma room to fund trials if conditions are favorable, but it also keeps dilution risk on the table after an already dilution heavy year and with higher risk funding on the balance sheet.
Yet there is a single pressure point that could matter far more than the headline dilution risk if...
There's only one way to know the right time to buy, sell or hold Zenas BioPharma. Head to Simply Wall St's company report for the latest analysis of Zenas BioPharma's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Zenas BioPharma research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Zenas BioPharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zenas BioPharma's overall financial health at a glance.
Looking For More Investment Ideas Beyond Zenas BioPharma?
If this Zenas BioPharma story has you thinking more broadly about where to put fresh capital to work, it can help to line it up against a few very different types of opportunities using the Simply Wall St Screener.
- For investors who want potential mispricing combined with quality fundamentals, scan a curated set of 29 high quality undervalued stocks that may offer a more compelling balance between price and business strength.
- If capital preservation and steadier profiles matter more to you right now, narrow your search to a 30 resilient stocks with low risk scores that score well on resilience and financial robustness.
- When balance sheet strength is non negotiable, filter for companies in our list of solid balance sheet and fundamentals (23 results) and compare their financial footing with what you see at Zenas BioPharma.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com