
Why Xenon Pharmaceuticals Stock Is In Focus After Seizure Drug Filing
- Xenon Pharmaceuticals has submitted an NDA to the FDA for azetukalner in focal seizures, supported by two placebo controlled late stage trials and more than 1,500 patient years of safety data, while pausing new enrollment in psychiatry studies after reviewing neuropsychiatric adverse events.
- The voluntary pause in new major depressive disorder and bipolar depression enrollment, while epilepsy studies continue, highlights how safety management choices could affect azetukalner’s multi indication potential and Xenon Pharmaceuticals’ future revenue mix.
- We will now look at how Xenon Pharmaceuticals' investment narrative could shift given the azetukalner NDA and psychiatry enrollment pause.
Xenon Pharmaceuticals Investment Narrative Recap
To own Xenon Pharmaceuticals, you need to believe azetukalner can move from late stage epilepsy trials into a real commercial product while the broader ion channel portfolio matures behind it. The firm still reports no revenue and a sizeable loss of US$409.2 million, so the operating story is about converting R&D into its first cash generating asset.
In the near term, the most important catalyst is the FDA review of the azetukalner NDA in focal seizures and progress in the ongoing Phase 3 epilepsy trials. The biggest risk sits in clinical and safety outcomes as exposure widens, especially with psychiatry trials paused for new enrollment, which could slow any future multi indication revenue mix.
The NDA submission for azetukalner in focal seizures is the announcement that matters most for this setup. It crystallizes years of epilepsy trial work into a formal bid for U.S. approval and gives investors a clearer operational waypoint, while epilepsy Phase 3 studies like X TOLE3 and X ACKT continue in the background.
This filing also helps frame every other catalyst. Psychiatry timelines have shifted, with X NOVA2 topline data now expected in Q1 2027 and new enrollment paused, so azetukalner’s epilepsy path becomes the reference point for execution, safety monitoring and eventual payer and physician discussions if approval is granted.
Xenon Pharmaceuticals' current analyst narrative points to forecast revenue of US$384.6 million and earnings of US$72.8 million by 2029. This implies yearly revenue growth from effectively zero commercial revenue today and an earnings swing of about US$456 million, moving from a loss of US$383.2 million today to a projected profit in 2029.
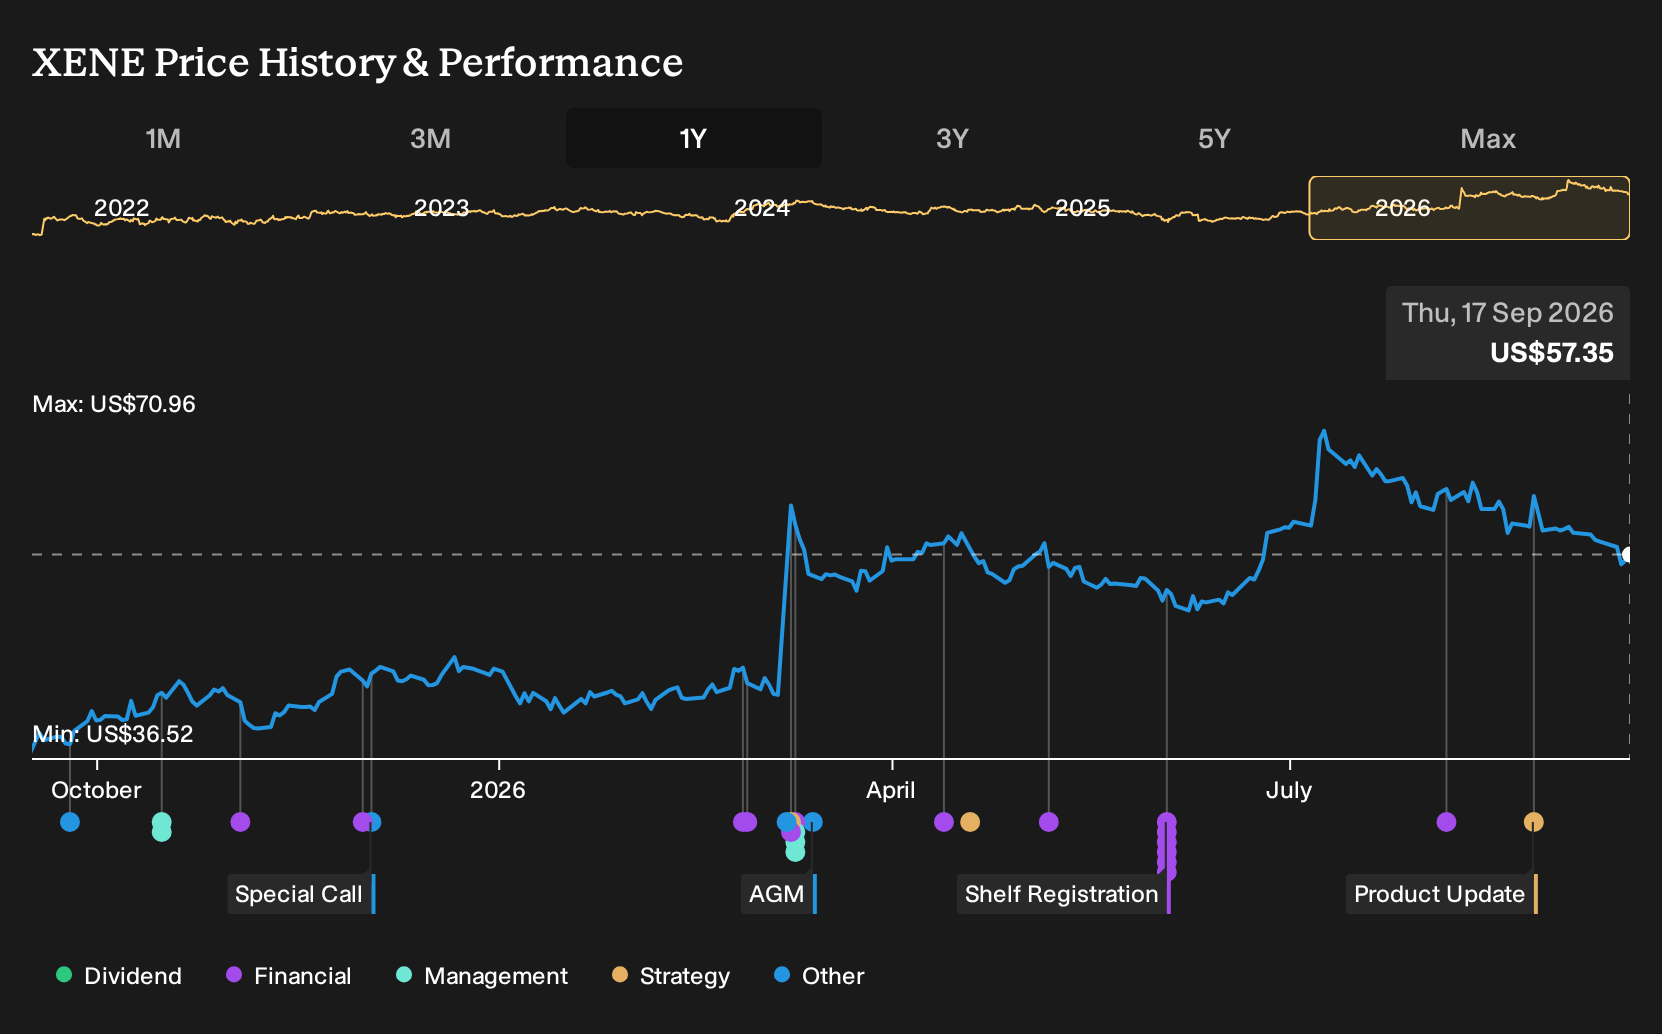
Uncover how Xenon Pharmaceuticals' fair value indicates a 40% potential upside to its current price, which could narrow quickly if sentiment turns more optimistic.
Exploring Other Perspectives
You might see the voluntary psychiatry enrollment pause very differently. The most optimistic analysts view it as a temporary speed bump and focus on azetukalner’s epilepsy potential, supporting revenue of about US$905.1 million and earnings of US$18.3 million by 2029. Those projections were set before this NDA and safety update, so opinions may change over time.
Explore 2 other Xenon Pharmaceuticals fair value estimates, including one that suggests as much as 645% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Xenon Pharmaceuticals research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Xenon Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xenon Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Xenon Pharmaceuticals?
If this Xenon Pharmaceuticals story has you thinking about where else late stage pipelines or resilient balance sheets could matter, it is a good moment to widen the lens using the Simply Wall St Screener.
- For investors who want potential upside with some fundamental support, scan through a curated set of 29 high quality undervalued stocks that combine quality signals with pricing that may not fully reflect them yet.
- If capital preservation ranks high on your checklist, filter for companies with sturdier finances using our list of solid balance sheet and fundamentals (23 results) and see which ones fit your risk tolerance.
- Income focused investors can hunt for steadier cash returns by reviewing a hand picked group of 6 dividend fortresses that offer higher yields backed by detailed fundamental data.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com