
International Seaways (INSW) As Record Q2 Tanker Earnings Meet An Overvalued View
International Seaways (INSW) has just posted record second quarter net income, with tanker earnings tied to higher time charter equivalent revenues as Middle East chokepoint disruptions push vessels onto longer crude and product routes.
At a share price of US$110.53, International Seaways has ridden strong tanker markets into sharp near term momentum, with a 7 day share price return of 8.21% and a 90 day move of 30.82%. Long term investors have seen a 1 year total shareholder return of 163.96% and a very large 5 year total shareholder return close to 10x. This signals that recent strength sits on top of an already powerful multi year rerating as the market reassesses both earnings power and risk around disruption driven tanker demand.
Scan for other shipping and energy plays showing similar disruption-driven momentum by reviewing our curated list of 29 high quality undervalued stocks.
International Seaways now trades above the average analyst target while still screening at a sizeable intrinsic discount. Is the market simply late to the story, or is it already pricing disruption risk correctly?
Most Popular Narrative: 8% Overvalued
Against the current share price of $110.53, the most followed narrative pegs International Seaways at a fair value of about $102.17, with that gap framed through a 7.24% discount rate and a heavier hit to future earnings than recent results suggest.
The company's strategy of renewing and modernizing its fleet, including the acquisition of newbuild eco-vessels and selling older tonnage, positions it to benefit from stricter environmental regulations, which may reduce operating costs and support sustained or improved net margins.
See why 55 investors see International Seaways as 8% overvalued.
Result: Fair Value of $102.17 (OVERVALUED)
Still, International Seaways faces meaningful risks if regulatory costs rise faster than expected or if a faster energy transition weakens long haul crude and product flows.
Find out about the key risks to this International Seaways narrative.
Another View: International Seaways Through Market Multiples
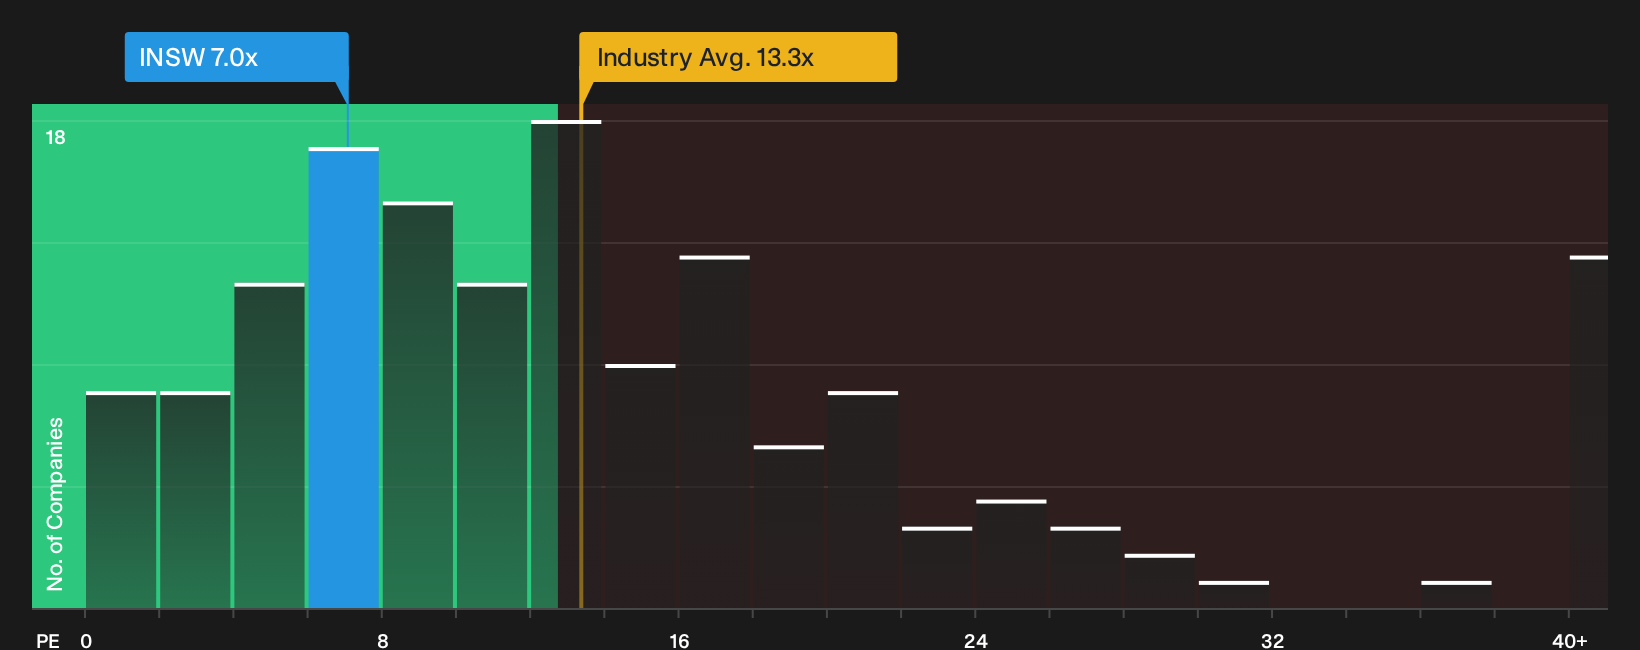
Analyst models call International Seaways about 8% overvalued against a fair value of $102.17. The market, using a simple P/E lens, tells a softer story. INSW trades around 7x earnings, while the US Oil and Gas group sits nearer 13.3x and close peers average 14x.
The fair ratio for INSW is 6.4x, slightly below its current multiple, which hints at limited room for error even if headline earnings look cheap beside the sector. If earnings expectations keep sliding yet the P/E stays this low relative to peers, is that a warning about quality of profits or an opportunity in plain sight for patient investors?
See what the numbers say about this price in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on International Seaways so far. If you want a clear personal stance before the market moves again, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond International Seaways?
If International Seaways has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to uncover fresh opportunities that match your risk, income, and value goals.
- Target potential higher return setups by scanning focused lists of fast moving opportunities through the 7 elite penny stocks with strong financials.
- Strengthen your portfolio foundation by filtering for balance sheet resilience and solid fundamentals using the list of solid balance sheet and fundamentals (23 results).
- Get ahead of the crowd by tracking underfollowed high quality prospects through our curated pool of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com