
What Nextpower Shares Patent Lawsuit Means For Shareholders
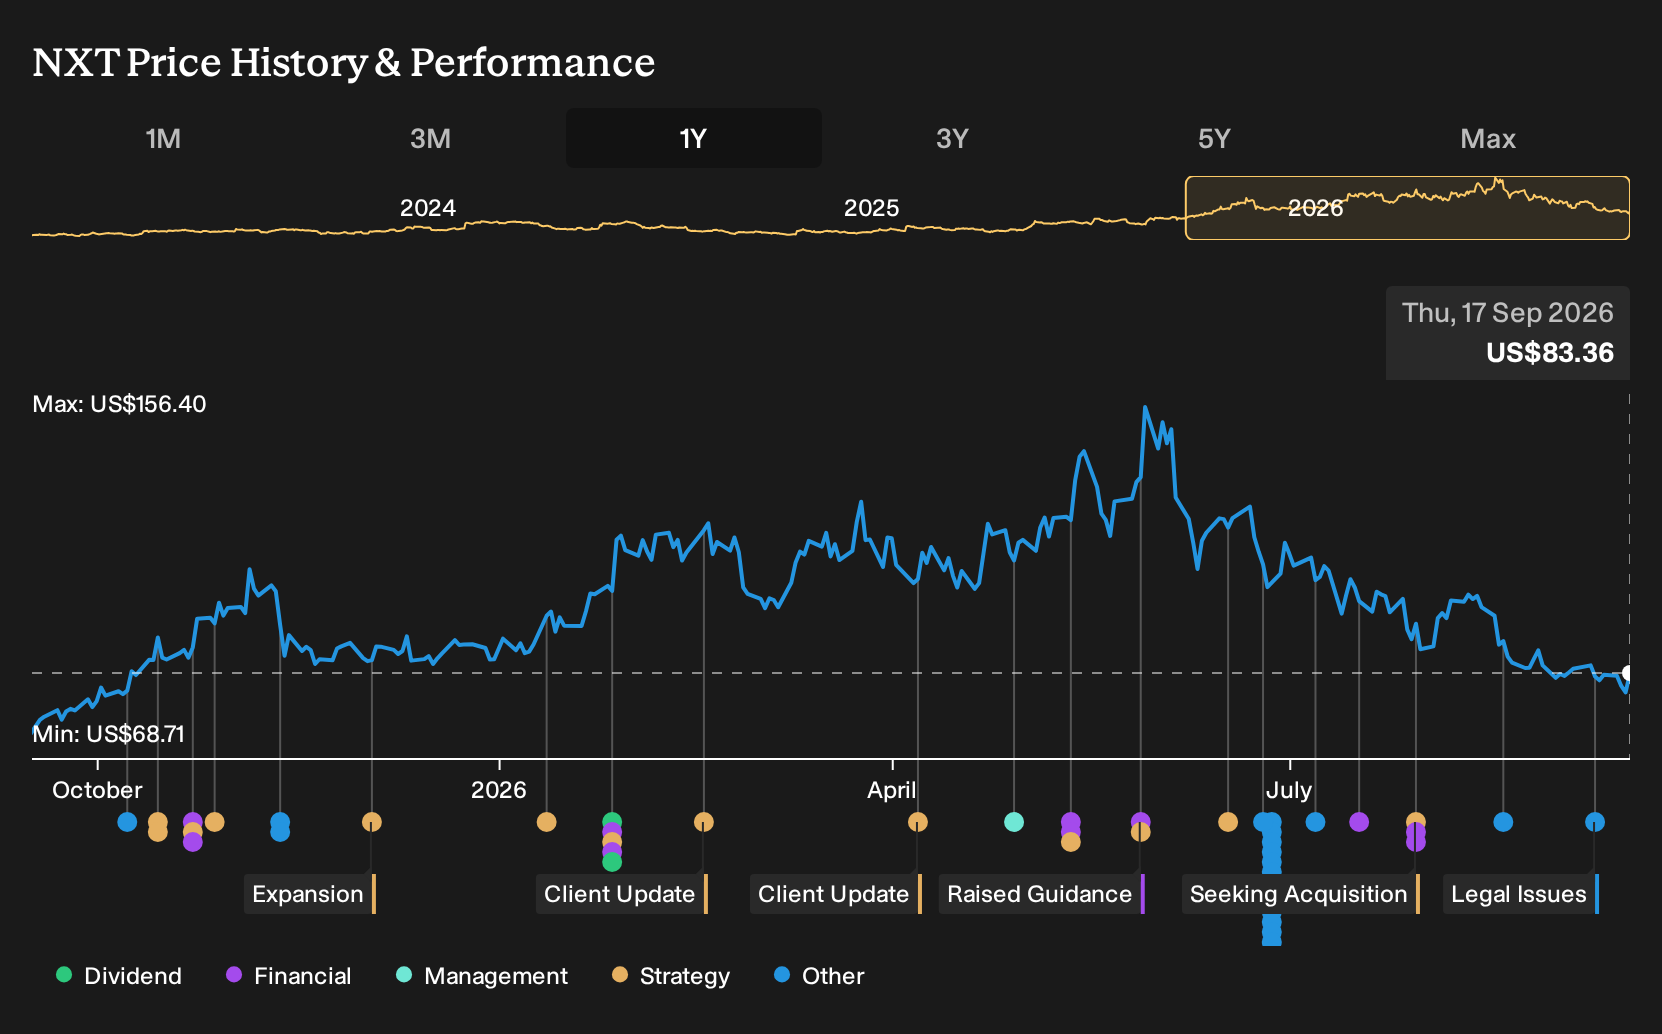
- GameChange Energy reported that its subsidiary GameChange Solar Corp. has filed a U.S. patent infringement lawsuit against Nextpower, alleging that Nextpower's solar tracker products use high tilt stow technology covered by GameChange's U.S. Patent 12,449,161 and seeking both injunctive relief and monetary damages.
- The dispute targets hardware central to Nextpower's solar tracker offering, which could affect product design choices, legal costs and how the business competes for future utility scale solar projects if the case becomes protracted.
- The next section considers how Nextpower's investment narrative could be affected by the new patent lawsuit over high tilt stow technology.
Nextpower Investment Narrative Recap
For you to own Nextpower, you need to believe utility scale solar continues to reward tracker specialists that execute well on technology, delivery and cost. The recent GameChange lawsuit adds a fresh legal overhang, but the core operational story still comes from project execution, backlog conversion and maintaining product differentiation in trackers and software.
Right now the key short term swing factor is how quickly management can steady sentiment after a 32% share price decline over six months tied to softer quarters. The biggest risk is compression in margins and cash flow if pricing, tariffs or project timing move against Nextpower while legal expenses rise.
The Barclays Energy Power Conference appearance on 10 September 2026 is the closest near term test of this story. Management gets a live stage to frame the lawsuit, reaffirm demand signals for NX Horizon platforms and remind investors of free cash flow progress, return on equity and the broader project pipeline.
Your focus at that event is simple. Watch how clearly Nextpower addresses legal risk, project timing, tariffs and domestic content exposure, and how confidently it talks about R&D spend versus profitability. That messaging can shape perceptions of whether current execution issues and the new patent dispute look manageable or start to weigh on the longer term thesis.
Nextpower's current analyst framework points to forecast revenue of US$6.1b and earnings of US$939.7m by 2029, built on an assumed 19.0% yearly increase in sales. That path implies an earnings step up of about US$345.6m from US$594.1m today, which is a little under a 1.6x rise in profit over the period.
Discover why Nextpower's fair value indicates a 69% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate angle on Nextpower focuses on financing risk rather than tariffs. The most cautious analysts already worked off slower demand, with revenue modeled at about US$5.5b and earnings of US$851.0m by 2029. You can read this as a clearly more pessimistic script, which may shift again once the lawsuit is fully processed.
Explore 4 other Nextpower fair value estimates, including one that suggests it could be worth just $98.33.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nextpower research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nextpower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nextpower's overall financial health at a glance.
Looking for more investment ideas beyond Nextpower?
Once you have a view on Nextpower, it often helps to set it beside a wider watchlist so you can judge risk, quality and income across different types of businesses.
- If you want resilient balance sheets and cleaner fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results) that can help you compare financial strength against what you see at Nextpower.
- For investors hunting for mispriced quality, scan a focused set of 29 high quality undervalued stocks that could sit alongside or compete with a position in Nextpower.
- If income matters as much as capital growth, weigh Nextpower against a group of higher yielding 6 dividend fortresses that may offer steadier cash returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com