
Why Is Moody's (MCO) Setting The Pace In Q2 Among Industry Rivals?
- Moody's (NYSE:MCO) reported a strong Q2 performance, with revenue growth that outpaced other financial exchanges and data providers.
- The group exceeded analyst forecasts on key metrics, beating consensus expectations for revenue, EBITDA, and EPS in the quarter.
- Compared with sector peers, Moody's delivered the fastest reported revenue expansion and the largest upside surprise versus analyst estimates.
- Moody's Q2 outperformance against analyst targets and peers adds important context to the broader picture our research has uncovered. We have also flagged 1 warning sign for Moody's.
This is far from the only business exposed to this theme. It is worth looking across a wider set of related stocks through 6 dividend fortresses.
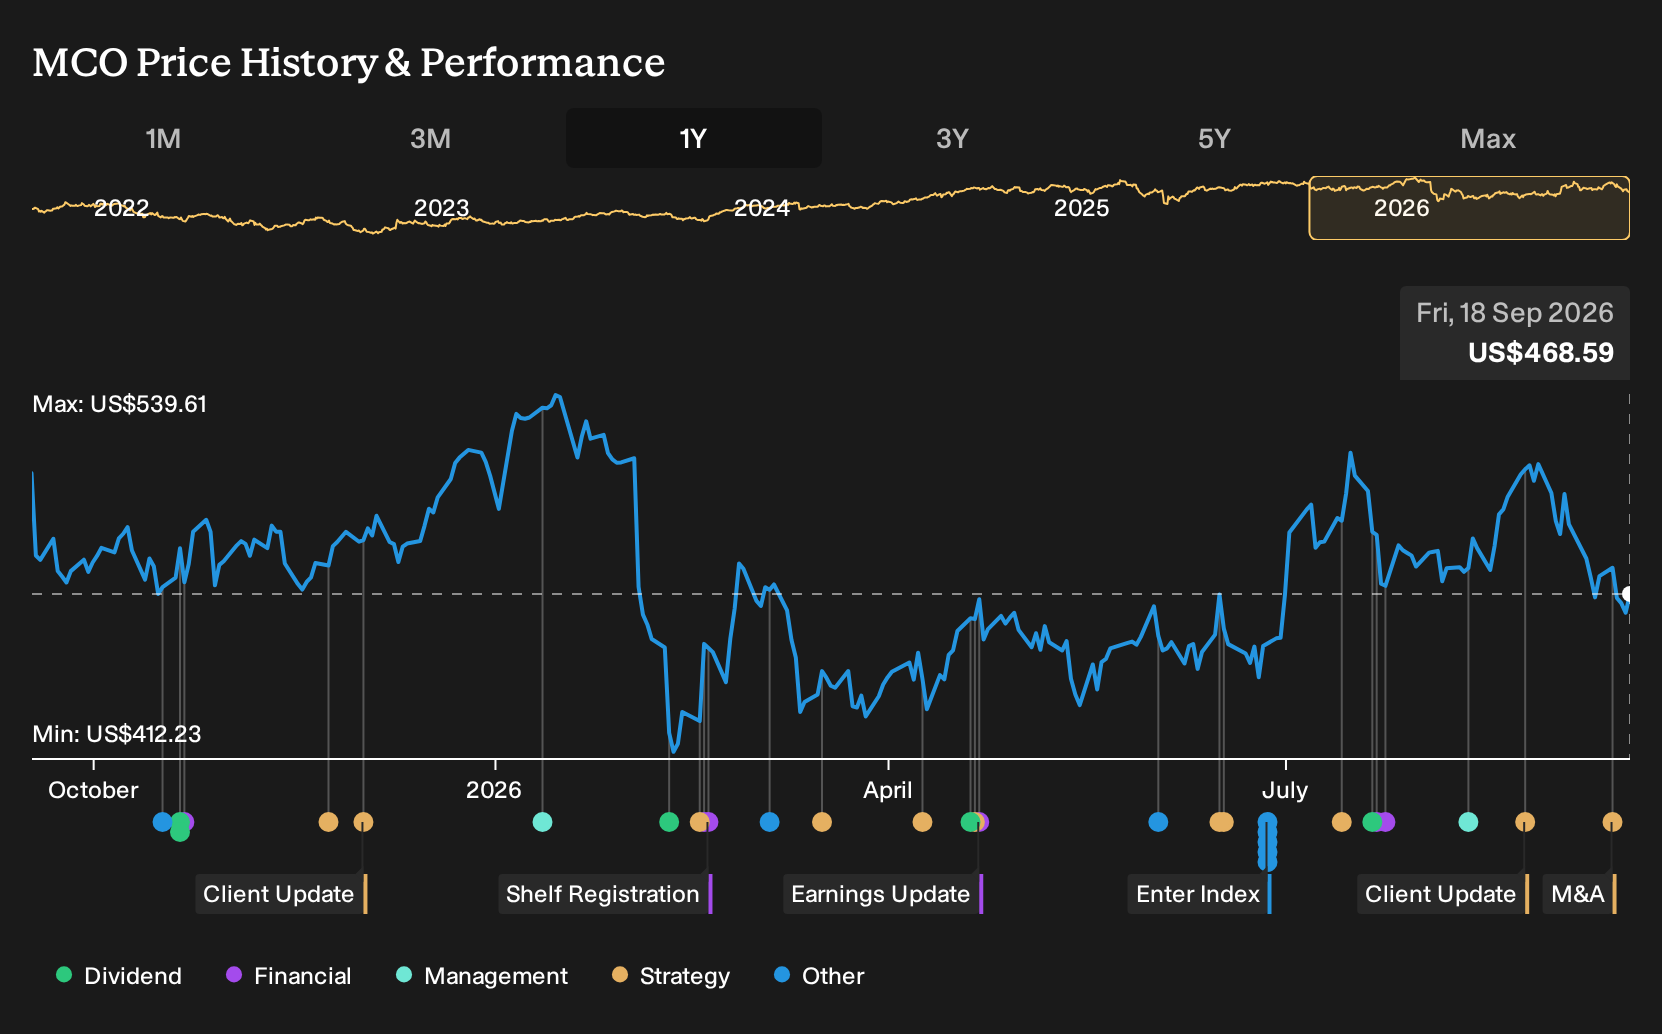
Moody's operates as an integrated risk assessment business, providing credit ratings and data services across the US and international markets. Its recent quarterly performance reflects the current level of demand customers have for its analytics and information tools.
See which insiders are buying and selling Moody's following this latest news.
Moody's Q2 beat leans into the bull story, but raises the execution bar
For investors, this Q2 beat reinforces the bullish narrative around Moody's ability to turn private credit demand and AI heavy analytics into resilient earnings power. Outperformance on revenue and EPS aligns with the idea that expanding private credit workflows, GenAI enabled products, and new partnerships are already supporting stronger operational leverage. It also indicates that market confidence in Moody's execution is high, which supports the existing view that the business can maintain healthy margins even as the sector evolves. The flip side is that such a strong quarter raises expectations. Investors focused on regulatory scrutiny, potential tech disruption from alternative data and internal AI tools, and customer concentration now have a higher bar for any future slowdown to be taken seriously by the market.
See how these catalysts shape Moody's path to a $560 fair value.
The next clear checkpoint is Moody's upcoming earnings update and guidance commentary, where investors can watch for any change in trends around private credit revenue contribution, AI driven Moody's Analytics margin progress, and management's tone on regulatory risks to the private credit segment.
The Moody's question this article has not answered yet
Short term headlines tell only part of the Moody's story. The bigger unresolved question is where current analyst projections say this business ends up a few years from now. See where analysts expect Moody's to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com