
Tenable Holdings (TENB) Deepens Anthropic Tie Up, Is The Stock Above Fair Value?
Tenable Holdings (TENB) has jumped into the spotlight after its share price moved above the average analyst target, following news of deeper Claude Mythos 5 integration into the Tenable One Exposure Management Platform.
That AI tie up comes on top of a strong run for Tenable Holdings, with the share price delivering a 90 day gain of 34.2% and a year to date share price return of 58.65%. However, the 5 year total shareholder return is down 22.38%, which shows long term holders have had a very different experience from recent buyers.
Compare Tenable Holdings' AI driven momentum with a curated group of cyber and AI exposed companies in our 35 AI small caps to see how this rerating stacks up.
The sharp move has pulled Tenable Holdings just above the average analyst target, which leaves a simple problem for new money: Do the current fundamentals still justify paying up from here?
Most Popular Narrative: 2% Overvalued
Tenable Holdings closed at $36.06 against a central fair value narrative of $35.35, so the story hinges on whether its AI heavy exposure management vision earns that small premium.
The convergence of IT, cloud, and OT environments requires organizations to obtain holistic risk visibility; Tenable's ability to consolidate multiple asset types (VM, cloud, identity, OT, AI security) in a single platform is resulting in larger deal sizes and growing enterprise adoption, directly impacting top-line growth and average selling prices.
See why 36 investors see Tenable Holdings as 2% overvalued.
Result: Fair Value of $35.35 (OVERVALUED)
Still, Tenable Holdings faces two clear pressure points. A crowded cybersecurity field could squeeze pricing, and heavier AI and acquisition spending might outpace the revenue pay off.
Find out about the key risks to this Tenable Holdings narrative.
Another View: Tenable Holdings Through A Sales Multiple Lens
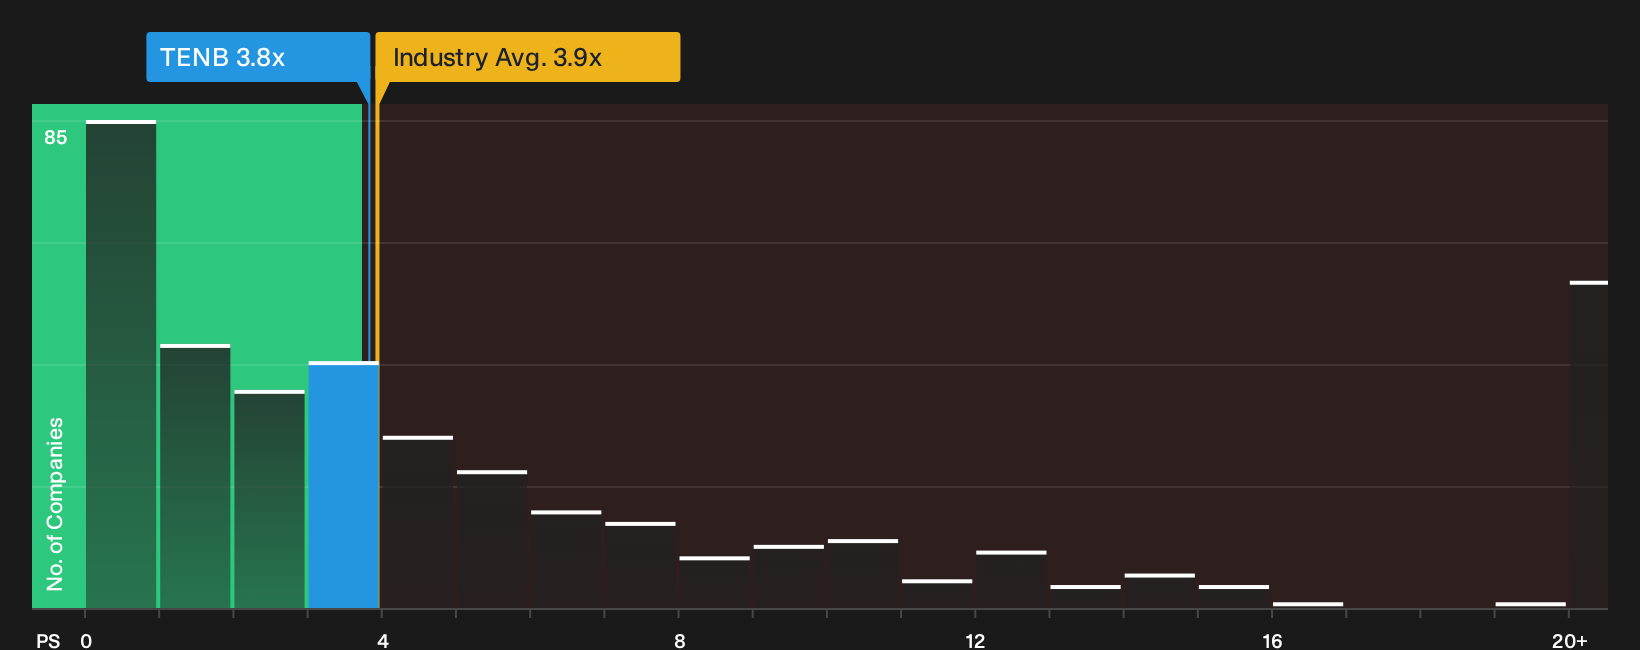
The DCF narrative frames Tenable Holdings as about 2% overvalued, yet the simple P/S picture looks more forgiving. The stock trades around 3.8x sales, slightly below the US Software group near 3.9x and under an estimated fair ratio of 4.1x, which points to limited valuation stretch. The real question is whether earnings quality and execution risk justify that modest discount or indicate a potential mispricing.
Our sales based view raises questions about how much safety is really embedded in that discount compared with peers. It is therefore worth seeing what the detailed multiples breakdown says about Tenable Holdings from here See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Tenable Holdings so far. If you want to move before sentiment shifts again, weigh the trade off yourself with the 4 key rewards and 2 important warning signs.
Looking for more Tenable Holdings sized investment ideas?
If you want to keep sharpening your edge beyond Tenable Holdings, use the Simply Wall Street Screener to surface fresh opportunities before the crowd catches on.
- Target quality at a discount by hunting for companies with strong fundamentals that still trade below intrinsic value through the 29 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with conservative leverage and healthy liquidity using the list of solid balance sheet and fundamentals (23 results).
- Spot potential future leaders early by scanning a curated pool of under followed opportunities with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com