
Edge AI Design Win Might Change The Case For Investing In Microchip Technology Stock (MCHP)
- Microchip Technology reported that AnalogAI selected Silicon Storage Technology’s memBrain SAGE neuromorphic IP for ultra-low power edge AI processors and that the SY757xx family of 1.2V LVCMOS clock buffers entered production and sampling to support high-speed FPGA, SoC and CPU platforms.
- These design wins and product launches point to Microchip Technology pushing deeper into real-world edge AI hardware and timing solutions, where power efficiency, jitter performance and on-chip non-volatile storage are central to customer buying decisions.
- We will look at how Microchip Technology's memBrain SAGE edge AI design win reshapes the broader investment narrative around its product portfolio.
Compare Microchip Technology’s edge AI push with other hardware stocks that may be setting up for a breakout by scanning our curated list of 89 AI infrastructure stocks.
Microchip Technology Investment Narrative Recap
To own Microchip Technology, you need to believe the business can turn design wins in edge AI and timing into steadier demand while working through high inventory and factory underutilization. The recent AnalogAI and SY757xx updates are encouraging for the product story but do not directly resolve the near term drag from elevated inventory or factory charges.
The short term swing factor remains how fast end markets absorb stock so utilization and margins can recover. The biggest risk is that the recovery is slower than expected, which would keep pressure on earnings and limit how quickly Microchip Technology can address its high debt load and keep funding product development at the same pace.
The AnalogAI adoption of Silicon Storage Technology’s memBrain SAGE neuromorphic IP is the clearest tie to the edge AI thesis. It shows Microchip Technology licensing its SuperFlash based technology into real world processors that target sub one watt environments such as robots, drones and vehicles, which fits cleanly with the embedded control story.
For catalysts, this win helps Microchip Technology deepen its presence in AI enabled industrial and automotive style applications where non volatile on chip storage, low power and latency are critical. The operational test now is execution. That means converting this and similar IP deals, plus the SY757xx clock buffer family, into meaningful licensing and semiconductor product revenue without letting capital intensity, inventory or debt service crowd out returns.
Microchip Technology's current earnings of $367.2 million are set against analyst expectations for revenue to grow 16.8% per year and for earnings to reach $2.3 billion by 2029, which implies an earnings increase of about $1.9 billion if those forecasts play out.
Uncover why Microchip Technology's fair value indicates a 48% potential upside to its current price that may not last much longer.
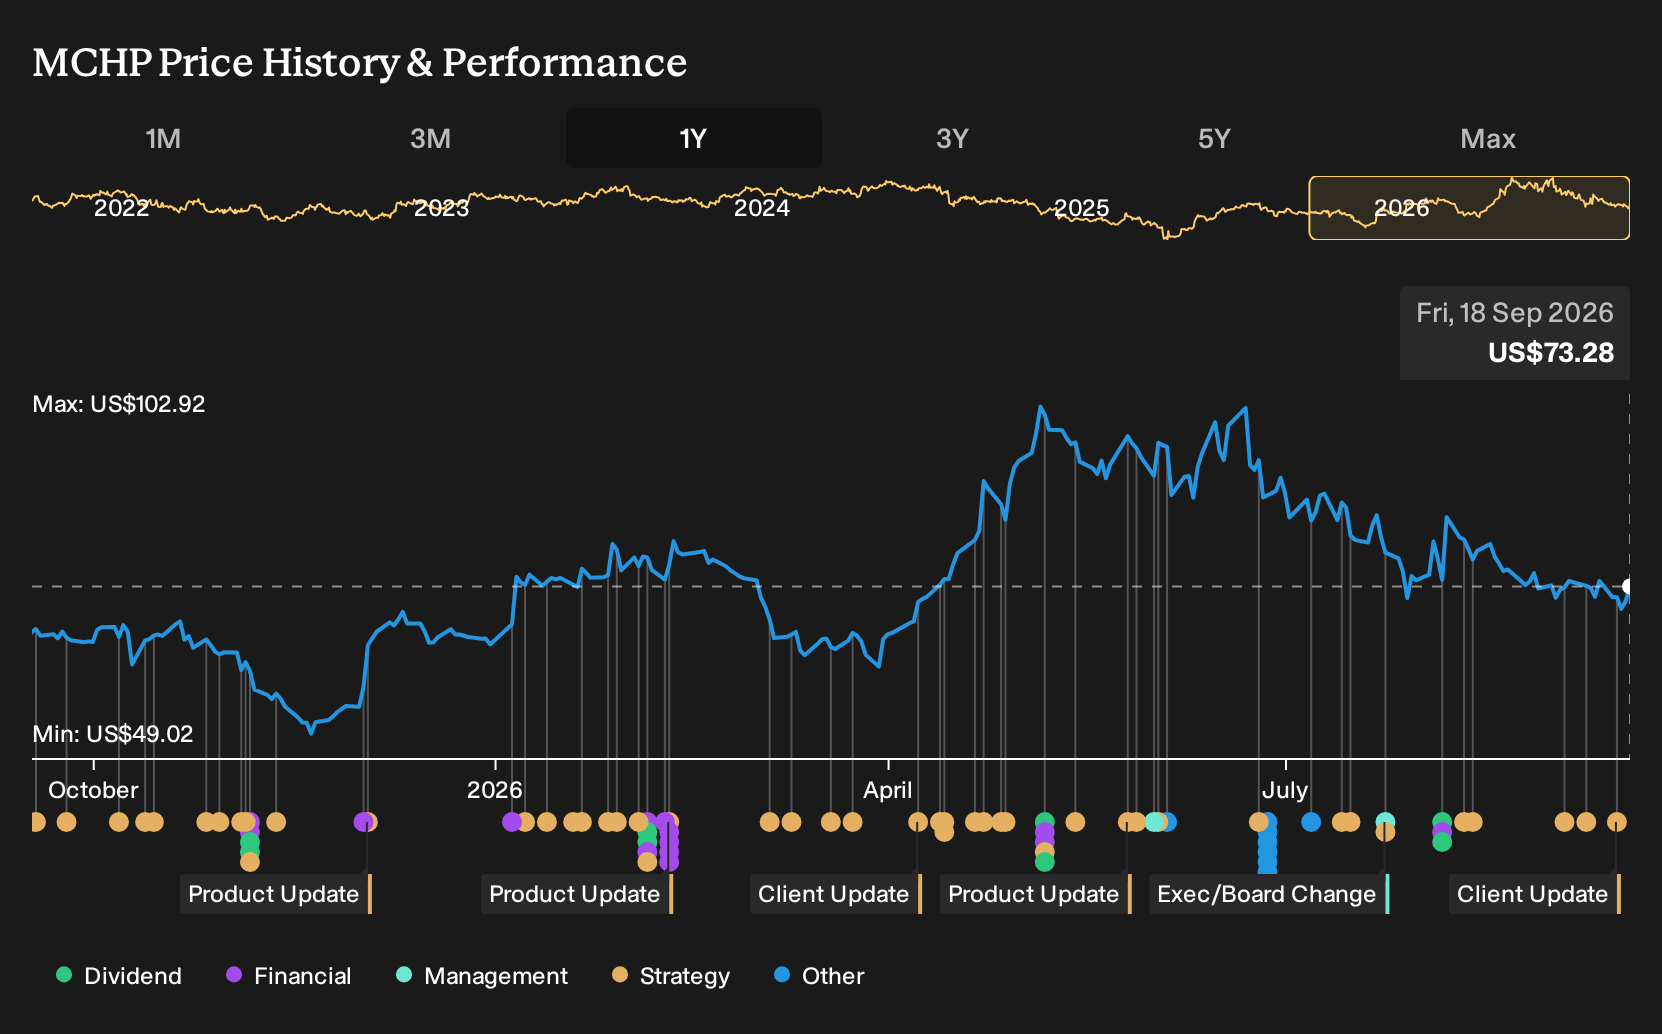
Exploring Other Perspectives
High conviction analysts focus on a different catalyst. They see Microchip Technology’s efficiency plan and inventory clean up as the real swing factor, not just edge AI wins. Some of these forecasts already assume revenue reaching about US$8.1b and earnings near US$2.3b by 2029, so this new AnalogAI deal could reshape those expectations again.
Explore 4 other Microchip Technology fair value estimates, including one that suggests the potential for as much as 84% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Microchip Technology research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Microchip Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Microchip Technology's overall financial health at a glance.
Looking For More Ideas Beyond Microchip Technology?
Once you have a view on Microchip Technology, it often helps to line it up against other opportunities on your radar. The Simply Wall St Screener can surface very different types of stocks so you can compare quality, risk and potential return profiles side by side.
- If you want income to play a bigger role in your portfolio, scan for higher yielding candidates through 6 dividend fortresses that might complement a position in Microchip Technology.
- For investors who care most about balance sheet strength, filter for financially robust businesses using the list of solid balance sheet and fundamentals (23 results) to see which ones match your risk tolerance.
- If you are hunting for less crowded opportunities, look across the 16 high quality undiscovered gems and see which smaller stories deserve a spot on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com