
SEB (ENXTPA:SK) Names A New CEO, Is The 23% Undervaluation Case Convincing?
SEB (ENXTPA:SK) has reshuffled its leadership, with the board appointing Loïc Moutault as Chief Executive Officer effective October 1, 2026, replacing Stanislas de Gramont at the end of his tenure.
SEB’s latest leadership change comes as the share price trades at €56.4, with a 90 day share price return of 8.67% and a year to date gain of 14.36%, suggesting improving momentum. This is occurring even though the 1 year total shareholder return is down 3.56% and the 5 year total shareholder return has declined 47.64%.
Compare SEB’s leadership change with other potential turnarounds by reviewing our curated list of 611 high quality undiscovered gems that display strong fundamentals but have received limited market attention so far.
SEB’s share price has started to recover even as long term returns remain weak and a new CEO steps in. Does that create a more attractive entry point now, or does it suggest waiting for potentially lower prices before investing?
Most Popular Narrative: 23% Undervalued
SEB is framed as undervalued in the most widely followed narrative, with a fair value of €73.45 against the latest close at €56.4, and that gap is tied directly to how earnings and margins might evolve over the next few years.
SEB's product innovation pipeline, demonstrated by recent launches (floor washers, air fryers, garment steamers) and investment in R&D, enables the company to capture premium pricing and better margins, which is cited as a factor supporting potential future net margin and revenue expansion. Expansion in Asia, especially China and the broader APAC region, is described as yielding growth on the back of urbanization and rising middle class consumption, and is presented as positioning SEB for long-term revenue growth as global demographics shift.
See why 6 investors see SEB as 23% undervalued.
Result: Fair Value of €73.45 (UNDERVALUED)
Still, SEB faces pressure from elevated inventories and weaker North American demand, which could weigh on margins and challenge the rebound narrative if these conditions persist.
Find out about the key risks to this SEB narrative.
Another View: What SEB's P/E Is Telling You
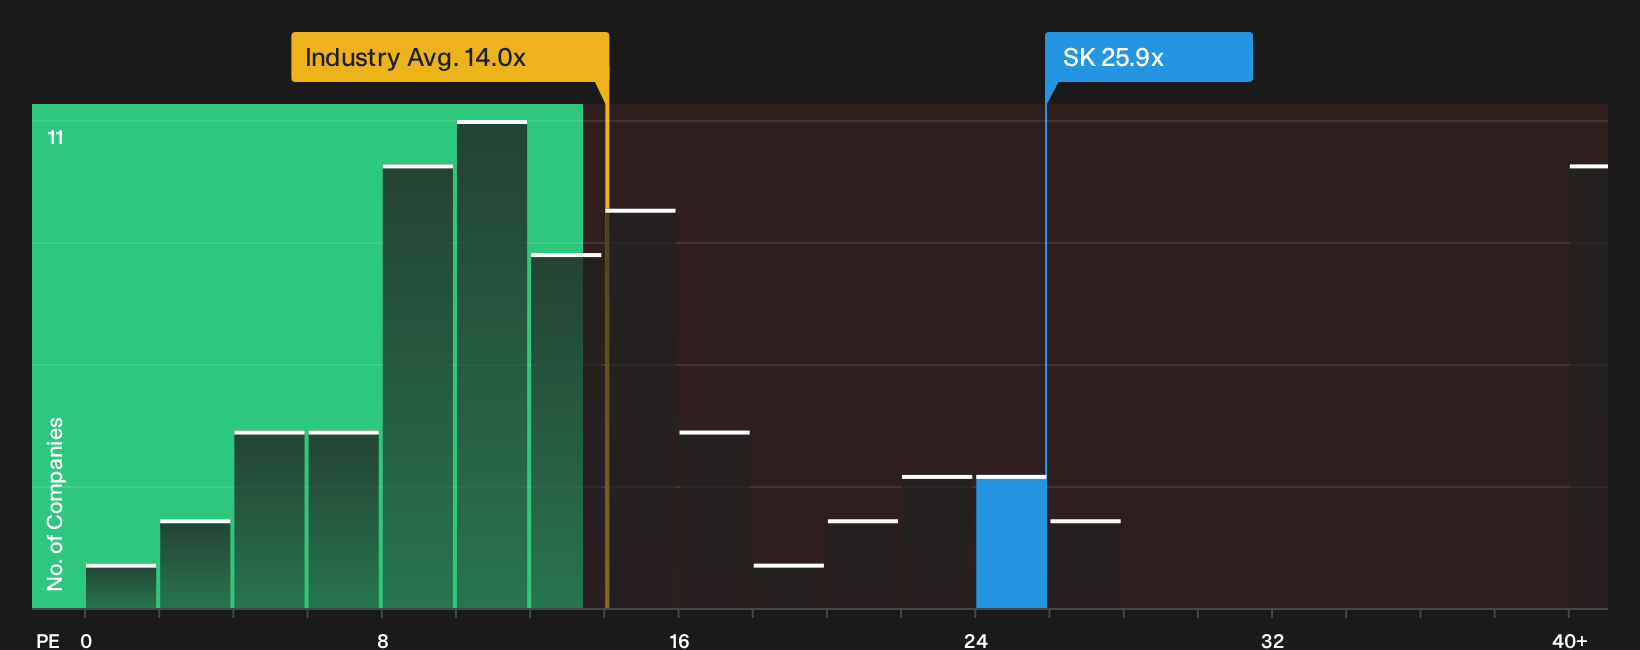
SEB might look cheap against fair value models, yet its valuation ratio sends a different signal. The stock trades on a P/E of 25.9x compared with 14x for the European Consumer Durables group and a fair ratio estimate of 29.4x, which points to less room for error if earnings disappoint. Does that premium simply reflect quality, or does it limit upside from here?
See what the numbers say about this price in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the SEB story make this a decision that rests heavily on your own judgment and time horizon, so move quickly to review both sides of the argument and weigh the 3 key rewards and 4 important warning signs.
Looking for more SEB investment ideas?
If SEB has you rethinking your watchlist, now is the moment to broaden your opportunity set with a few focused stock ideas curated through the Simply Wall Street Screener.
- Target potential mispricing by scanning for quality companies trading below their implied worth through the 178 high quality undervalued stocks.
- Prioritise resilience by reviewing the 227 resilient stocks with low risk scores that combine steadier risk profiles with more controlled downside.
- Strengthen your core holdings by checking the list of solid balance sheet and fundamentals (197 results) that pair healthier balance sheets with fundamental support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com