
What Savaria (TSX:SIS)'s Dividend Increase Means For Shareholders
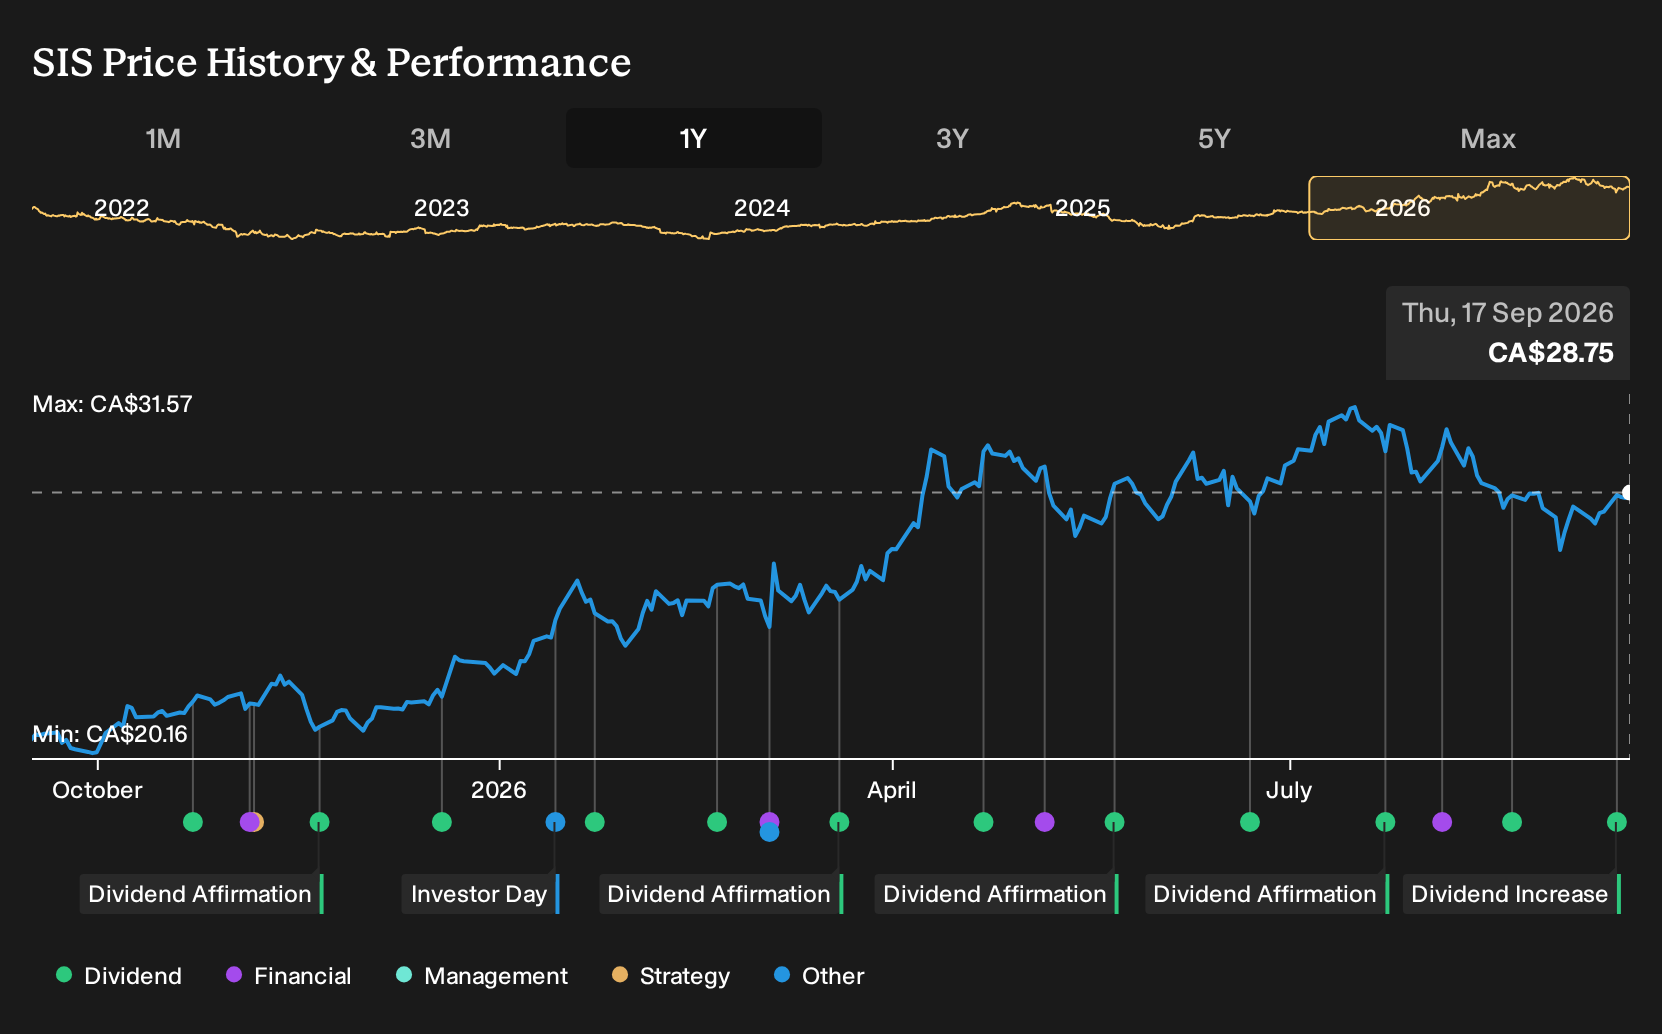
- Savaria Corporation previously announced that its Board approved a higher monthly dividend of C$0.04916 per share, lifting the annual payout to C$0.59 per share starting with the October 9, 2026 distribution to shareholders of record on September 30, 2026, designated as an eligible dividend for Canadian tax purposes.
- The decision links shareholder payouts directly to financial results in 2025 and early 2026.
- We will now see how Savaria’s higher monthly dividend, in the context of its recent financial results, could influence the existing long term investment narrative.
Scan how Savaria’s dividend move compares by reviewing other income focused stocks in our curated list of 1 dividend fortresses.
Savaria Investment Narrative Recap
To own Savaria, you need to be comfortable with a business that leans on aging demographics and support for accessibility, while still working through uneven demand in key regions. The higher dividend signals management confidence, but the more important near term driver remains execution on new product rollouts and dealer expansion, which underpins any improvement in organic revenue.
The main risk today sits in softer conditions and subsidy pressure in Europe, combined with the possibility that Savaria One efficiency gains taper off. If revenue momentum does not pick up as expected, earnings could feel tight and the dividend change may end up being more cosmetic than transformational for the equity story.
The dividend increase announced for the October 9, 2026 payment sits on top of a business that already reports growing earnings and higher net margins versus last year. That linkage matters. A higher regular payout funded by current profitability looks different from a raise that leans on leverage or one off items.
For you as a shareholder, the key question is how this dividend compares with other potential capital uses, such as further M&A or product investment. With analysts highlighting execution risk around new offerings and European exposure, the announcement places more focus on Savaria’s ability to keep margins resilient while still funding growth projects that support future cash flows.
Savaria's current analyst story points to CA$1.1b in revenue and CA$143.7 million in earnings by 2029, built on 6.3% yearly revenue growth and an earnings increase of about CA$64.7 million from CA$79.0 million today.
Uncover why Savaria's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between C$35 and about C$49 per share, so some private investors see Savaria as materially mispriced. When you set those opinions against risks like prolonged European subsidy pressure or slower Savaria One benefits, you get very different expectations for future performance. Explore those contrasting viewpoints before deciding how this dividend fits your own thesis.
Explore 2 other Savaria fair value estimates, including one that suggests as much as 69% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Savaria research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Savaria. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Savaria's overall financial health at a glance.
Looking For More Ideas Beyond Savaria?
If Savaria has sharpened your thinking about income, quality, and risk, it can help to line it up against other opportunities. The Simply Wall St Screener lets you filter for the traits you care about most so you can build a watchlist that actually fits your goals.
- For investors who want income supported by robust balance sheets, compare Savaria with a wider list of solid balance sheet and fundamentals (7 results) that can help you stress test portfolio resilience under different conditions.
- If your focus is on quality at a reasonable entry point, set Savaria beside a broader universe of 4 high quality undervalued stocks that pair solid fundamentals with what may be appealing price tags.
- For those who want growth without taking on too much fragility, round out your research by scanning 8 resilient stocks with low risk scores that screen for lower volatility and stronger financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com