
Carpenter Technology (CRS), Why Is It Back In The Spotlight?
Carpenter Technology (CRS) moves into a busy investor spotlight this week, presenting at Morgan Stanley's 14th Annual Laguna Conference and the 16th Annual Aviation Forum, putting its aerospace focused specialty metals story in front of institutional audiences.
The US$408.12 share price has pulled back sharply in recent weeks, with the stock down 20% over 30 days and 30% over 90 days, even though Carpenter Technology has delivered a 21% year to date share price return and a 1 year total shareholder return of 71%. This points to strong longer term momentum despite recent profit taking and a shift in risk appetite.
Scan beyond Carpenter Technology and see how other aerospace and industrial metals players stack up in our hand picked 38 power grid technology and infrastructure stocks.
After a rapid run up in Carpenter Technology followed by a sharp pullback, investors now face a simple question: Does the current valuation still leave enough upside to justify the risk?
Most Popular Narrative: 35% Undervalued
On the most followed view of Carpenter Technology, the current $408.12 price sits well below an assessed fair value of $625.88. This assessment anchors expectations on earnings, margins, and cash flows discounted at 8.02%.
The brownfield expansion project is set to add high-purity melt capacity, allowing Carpenter to further leverage the industry supply-demand imbalance over the medium to long term. This is expected to support higher volumes and sustained pricing power, translating into increased revenue and operating income beginning FY28.
See why 24 investors see Carpenter Technology as 35% undervalued.
Result: Fair Value of $625.88 (UNDERVALUED)
Still, the Carpenter Technology story could change quickly if aerospace demand softens or the US$400m brownfield expansion delivers weaker returns than expected.
Find out about the key risks to this Carpenter Technology narrative.
Another View: Carpenter Technology Through The P/E Lens
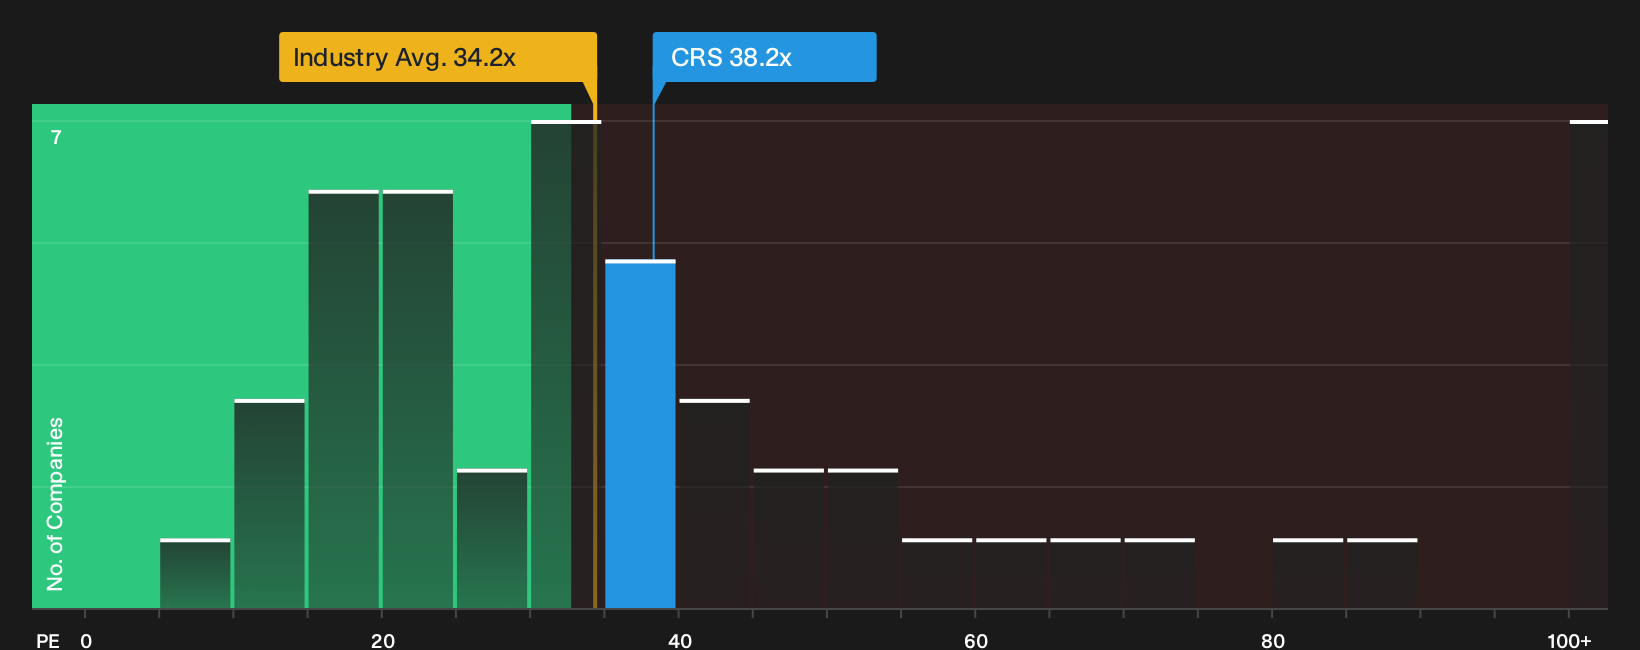
Step away from the fair value of $625.88 and look at Carpenter Technology through its P/E. The shares trade on 38.2x earnings, which is richer than the US Aerospace & Defense sector at 34.2x and above a fair ratio of 30.6x that the market could move toward. That kind of gap can reward patience if growth holds up, but it also raises the question of how much multiple risk you really want to take on at $408.12.
For a deeper look at how this earnings multiple compares across peers and what the fair ratio implies in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Carpenter Technology can feel unsettling, so consider acting promptly, reviewing the numbers yourself, and weighing both sides of the story with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Carpenter Technology?
If Carpenter Technology has your attention, do not stop here. Broaden your watchlist with a few targeted screeners that surface different kinds of opportunities before other investors catch on.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that highlights businesses combining financial strength with dependable fundamentals.
- Hunt for potential value by reviewing 33 high quality undervalued stocks that flag companies trading below their assessed worth based on cash flows and balance sheet quality.
- Zero in on lesser known prospects by checking 16 high quality undiscovered gems that spotlight smaller profiles with solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com