
How Investors Are Reacting To ROHM (TSE:6963) New Safety MOSFET Launch
- ROHM has recently released the RS4P063BPHZG, a 100V Wide-SOA MOSFET for automotive safety and protection circuits, using a common 5060-size package and targeting short-duration high-power loads.
- The move pushes ROHM’s Wide-SOA know-how from AI servers and industrial power supplies into safety-critical car electronics, where reliability, package compatibility, and design-change workload all matter directly for customers’ engineering budgets.
- The focus now shifts to how ROHM’s push into Wide-SOA automotive MOSFETs could influence the broader investment narrative around execution and demand.
ROHM Investment Narrative Recap
To own ROHM, you need to believe the semiconductor manufacturer can turn its unprofitable position, with a reported loss of ¥152,403, into sustainable earnings while managing a weak Japanese automotive and industrial backdrop. The immediate swing factor remains execution on cost reductions versus still elevated fixed expenses and prior inventory issues that weighed on operating profit.
The new Wide SOA automotive MOSFET supports that operational story but does not by itself change the near term catalyst. The main watchpoint is still whether demand in industrial and EV linked power devices stabilises fast enough to meet revised sales and profit goals, while the biggest risk is any prolonged slump in these end markets.
The RS4P063BPHZG launch matters most because it connects ROHM’s Wide SOA know how in AI servers and industrial power supplies directly to safety critical automotive circuits. That ties into the broader push to grow SiC and power device related revenue, where management has been investing in capacity and organizational changes to align product families with applications.
This kind of part, already in mass production, also tests ROHM’s ability to win slots in airbags, pretensioners and battery protection where reliability expectations are strict and design wins can run for many years. For investors watching catalysts, consistent execution on this product and the related Wide SOA roadmap can help offset the risk from softer industrial demand and earlier guidance cuts.
ROHM's narrative projects ¥612.6b revenue and ¥78.7b earnings by 2029. This assumes 7.0% yearly revenue growth and an earnings swing of about ¥231.1b from a reported loss of ¥152.4b today.
Discover how ROHM's fair value indicates a 24% potential upside to its current price that may not last much longer.
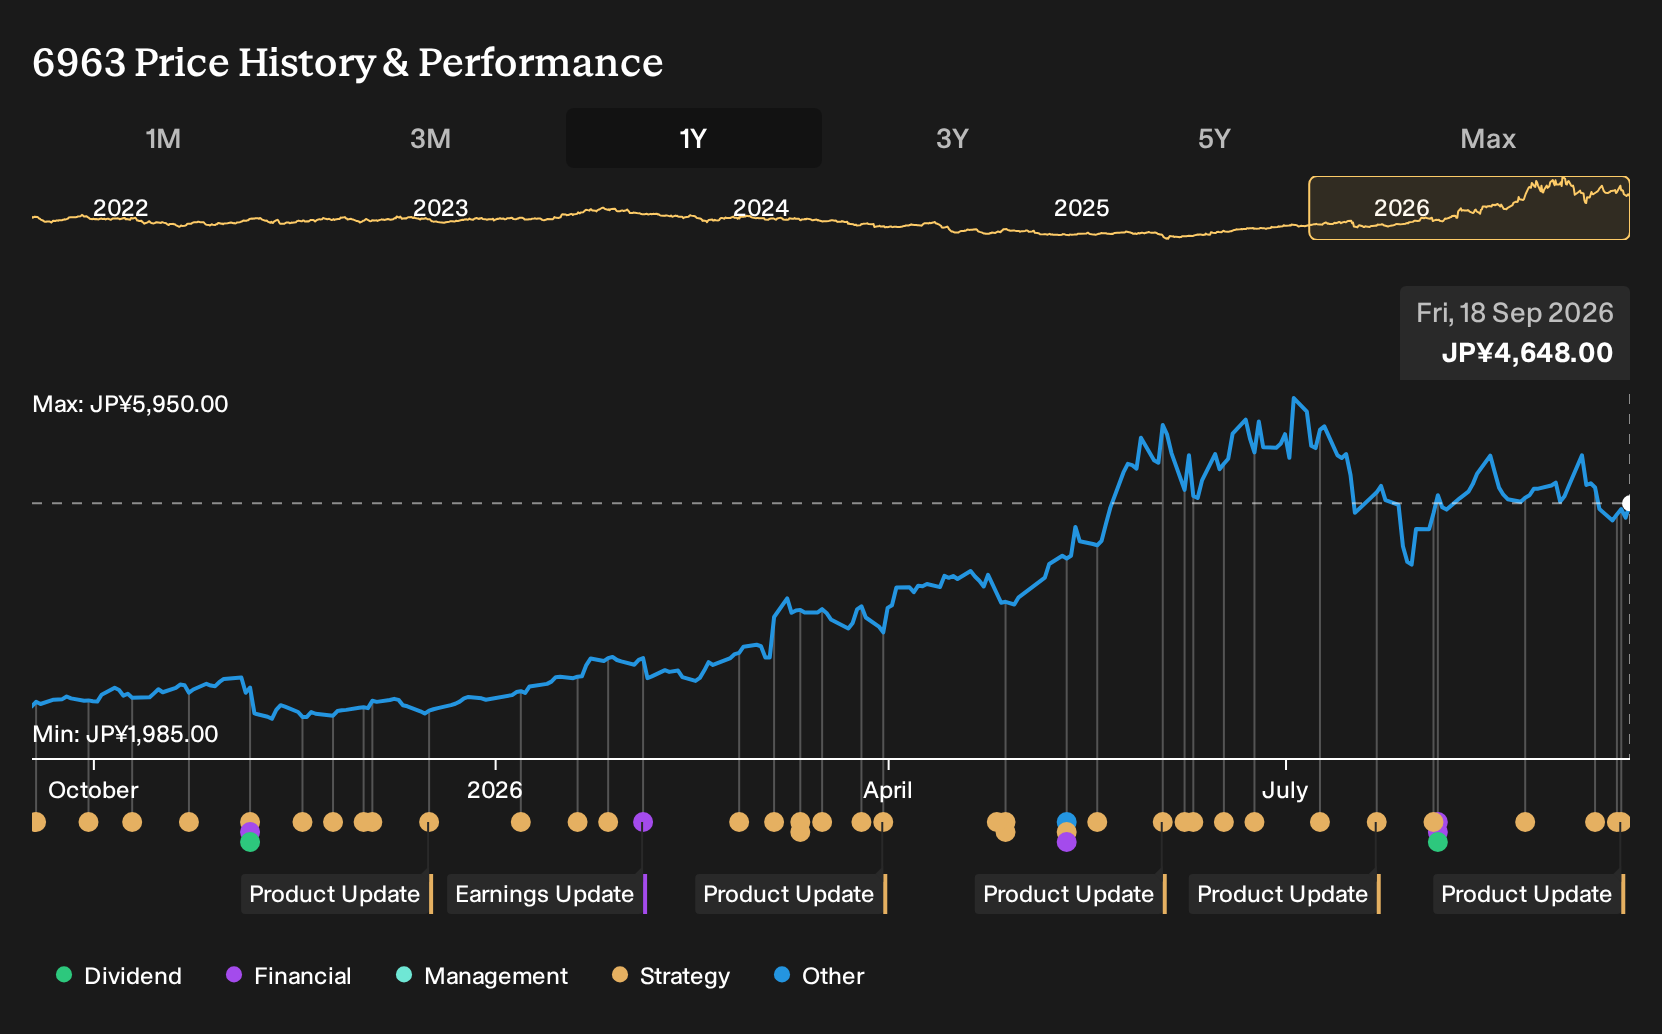
Exploring Other Perspectives
One contrasting angle focuses less on ROHM’s new Wide SOA MOSFET and more on the risk that xEV traction inverter demand underwhelms. The lowest analysts were already pencilling in slower progress, with revenue assumptions of ¥532.4b and earnings of ¥71.8b by 2029. Their more cautious storyline could shift if this product family gains traction.
Explore 2 other ROHM fair value estimates, including one that suggests as much as 68% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ROHM research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ROHM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ROHM's overall financial health at a glance.
Looking For More Investment Ideas Beyond ROHM?
If the ROHM story has you thinking about where else reliable earnings power and balance sheet strength might show up, the next step is to widen your watchlist using the Simply Wall St Screener.
- For investors who want quality and value to meet in the same place, scan through a curated set of 17 high quality undervalued stocks that pass both cash flow and balance sheet checks.
- If durability matters more to you than excitement, filter for 21 resilient stocks with low risk scores that score well on stability and financial resilience.
- When you want to get ahead of the crowd, focus on 74 high quality undiscovered gems that combine solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com