
NVIDIA Stock And 2 US AI Infrastructure Leaders Worth A Closer Look
AI spending now touches everything from GDP headlines to your grocery bill, as US growth leans heavily on data centers and chips while politicians cheer it on and rating agencies flag crash risk. That mix of support and fragility creates both opportunity and real downside for anyone holding US equities. This article walks through three US AI Infrastructure & Data Center Leaders stocks that are directly exposed to that story.
The three stocks covered below are a small sample of the US AI Infrastructure & Data Center Leaders idea. The full screen surfaced 31 more large caps with similar AI and data-center storylines that are not detailed here.
If you want to identify and analyze the broader opportunity set, head straight to the US AI Infrastructure & Data Center Leaders screener to filter for the combinations of quality, growth and balance sheet strength that fit your own playbook.
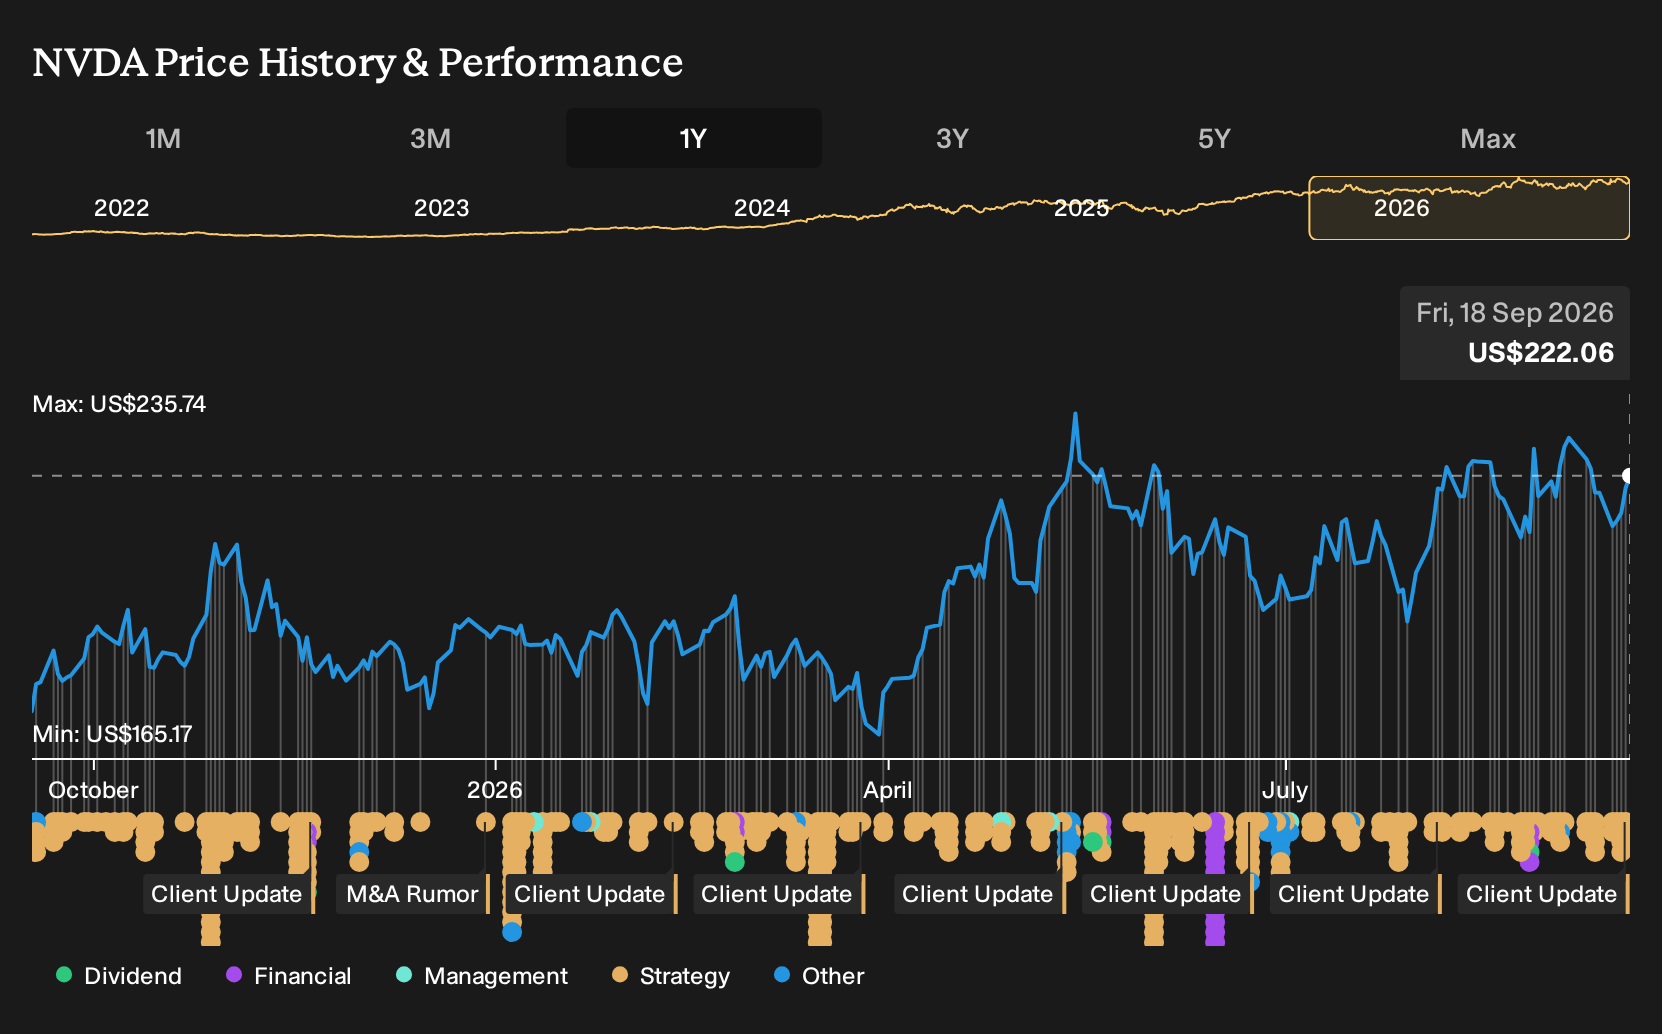
NVIDIA (NVDA)
Overview: NVIDIA is a data center scale AI infrastructure provider, supplying GPUs, full-stack platforms and software that power hyperscale AI and cloud workloads worldwide.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, with revenue primarily from US$214.9b in the United States and US$64.8b in Taiwan.
Market Cap: US$5,296.4b
NVIDIA matters for this screener because its chips, systems and software effectively form the plumbing of today’s AI data centers, tying its fortunes tightly to AI compute spend.
"Uptake of an open-source, cheaper, or better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
What happens to NVIDIA’s rich AI data center economics if a single key assumption about the software layer quietly shifts?
If that assumption shift is on your mind, read the full narrative for NVIDIA to see how NVIDIA’s moat, pricing power and AI data center position could evolve next.
Applied Materials (AMAT)
Overview: Applied Materials supplies chipmaking equipment, software and services that help manufacturers produce advanced semiconductors used in AI data centers worldwide.
Operations: Applied Materials generates about US$22.4b from Semiconductor Systems and US$7.2b from Applied Global Services, with sales spread across Asia, the United States and Europe.
Market Cap: US$331.2b
Applied Materials sits at the pick and shovel layer of the AI buildout, as its tools enable the advanced chips that power hyperscale data centers and cloud servers.
"Structural growth in AI and high-performance computing is reshaping semiconductor demand, driving heavy investments in advanced chip architectures such as gate-all-around (GAA) transistors, high-bandwidth memory (HBM), and advanced packaging. Applied is set to benefit from these device inflections due to its leadership in materials engineering and strong customer adoption of new process technologies, which are expected to deliver outsized revenue and market share gains as these nodes ramp from 2026 onward."
What happens to Applied Materials’ rich AI equipment economics if a single assumption about how long that buildout runs quietly shifts?
That timing question is exactly what the full narrative for Applied Materials unpacks, mapping where Applied Materials could keep accelerating as AI spending shifts and where the risk of stalling really sits.

Cerebras Systems (CBRS)
Overview: Cerebras Systems builds wafer scale AI compute racks for data centers, giving hyperscalers and enterprises hardware tuned for massive inference workloads.
Operations: Cerebras generates about US$680.7 million from Semiconductors, with roughly US$236.6 million from the United States and US$443.5 million from Europe, the Middle East and Africa.
Market Cap: US$46.1b
For an AI infrastructure screen, Cerebras Systems is the purest expression of the theme because its entire business model depends on selling and running custom hardware inside hyperscale style data centers as AI inference usage keeps expanding.
"In March 2026, AWS integrated Cerebras CS-3 systems directly into Amazon Bedrock, solving a classic engineering headache by splitting the inference workload into two parts and delivering up to a 15x speed improvement over monolithic GPU setups."
The durability of Cerebras Systems’ AI data-center opportunity now largely hinges on how one concentrated source of demand behaves if conditions change.
If that buyer concentration is what you keep circling back to, read the full narrative for Cerebras Systems to see how Cerebras Systems could still compound its AI footing.

Seeking Alternatives Before Momentum Flies
Fresh themes move first, prices follow later. Spot the next breakout list while it is still under the radar for now and act now.
- Target steadier portfolio anchors by scanning the 30 resilient stocks with low risk scores before the crowd chases safety and the most resilient balance sheets get fully priced.
- Ride potential momentum shifts by tracking the 18 cryptocurrency and blockchain stocks while sentiment keeps dropping in and out of favor and price moves can be sharp.
- Position for energy transition stories by reviewing the 19 nuclear energy infrastructure stocks while these infrastructure plays are still flying under most AI focused radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com