
What Marriott International (MAR)'s Europe Luxury Resort Expansion Means For Shareholders
- Marriott International highlighted strong global RevPAR performance and broad demand across luxury, premium, select, and midscale brands. This was supported by a record pipeline of about 629,000 rooms and a focus on fee-based income from management and franchising.
- The firm is extending its higher-end footprint with The Ritz-Carlton, Kemer, All-Inclusive in Türkiye and deepening corporate travel engagement through a new direct integration between Spotnana and Marriott’s central reservation system, including verified Marriott Bonvoy loyalty linking.
- We will look at how Marriott International's long-term investment narrative aligns with its luxury all inclusive expansion in Türkiye.
Scan beyond Marriott International and see how other hotel and travel operators with fee-heavy models are positioned in our hand picked 33 high quality undervalued stocks.
Marriott International Investment Narrative Recap
To own Marriott International, you need to believe in a fee heavy, asset light model that depends on RevPAR resilience, net unit growth, and ongoing strength in Marriott Bonvoy engagement. The near term swing factor is how global travel demand and pricing hold up against softer pockets in select service and business transient segments.
The biggest risk right now sits in the combination of high technology spend, leverage, and any slowdown in RevPAR or conversion driven unit additions. The new Ritz Carlton, Kemer, All Inclusive and broader luxury focus are interesting for brand depth, but have limited impact on near term earnings risk or catalysts.
Among the recent news, the new direct integration with Spotnana looks closest to a near term catalyst for Marriott International. Direct connectivity into Marriott’s central reservation system plus verified Bonvoy loyalty linking points toward deeper direct booking relationships with corporate travel buyers rather than just more inventory on one more channel.
If execution goes to plan, this type of integration can support fee revenue durability by keeping more corporate volume inside Marriott’s ecosystem, improving content quality, and giving travel managers cleaner access to negotiated rates. The risk is that heavy technology investment and execution complexity remain high while competitors race to similar distribution and loyalty integrations.
Marriott International's outlook projects US$30.7b revenue and US$3.8b earnings by 2029. This profile assumes revenue growth of 62.3% per year and an earnings increase of US$1.2b from US$2.6b today.
Uncover why Marriott International's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
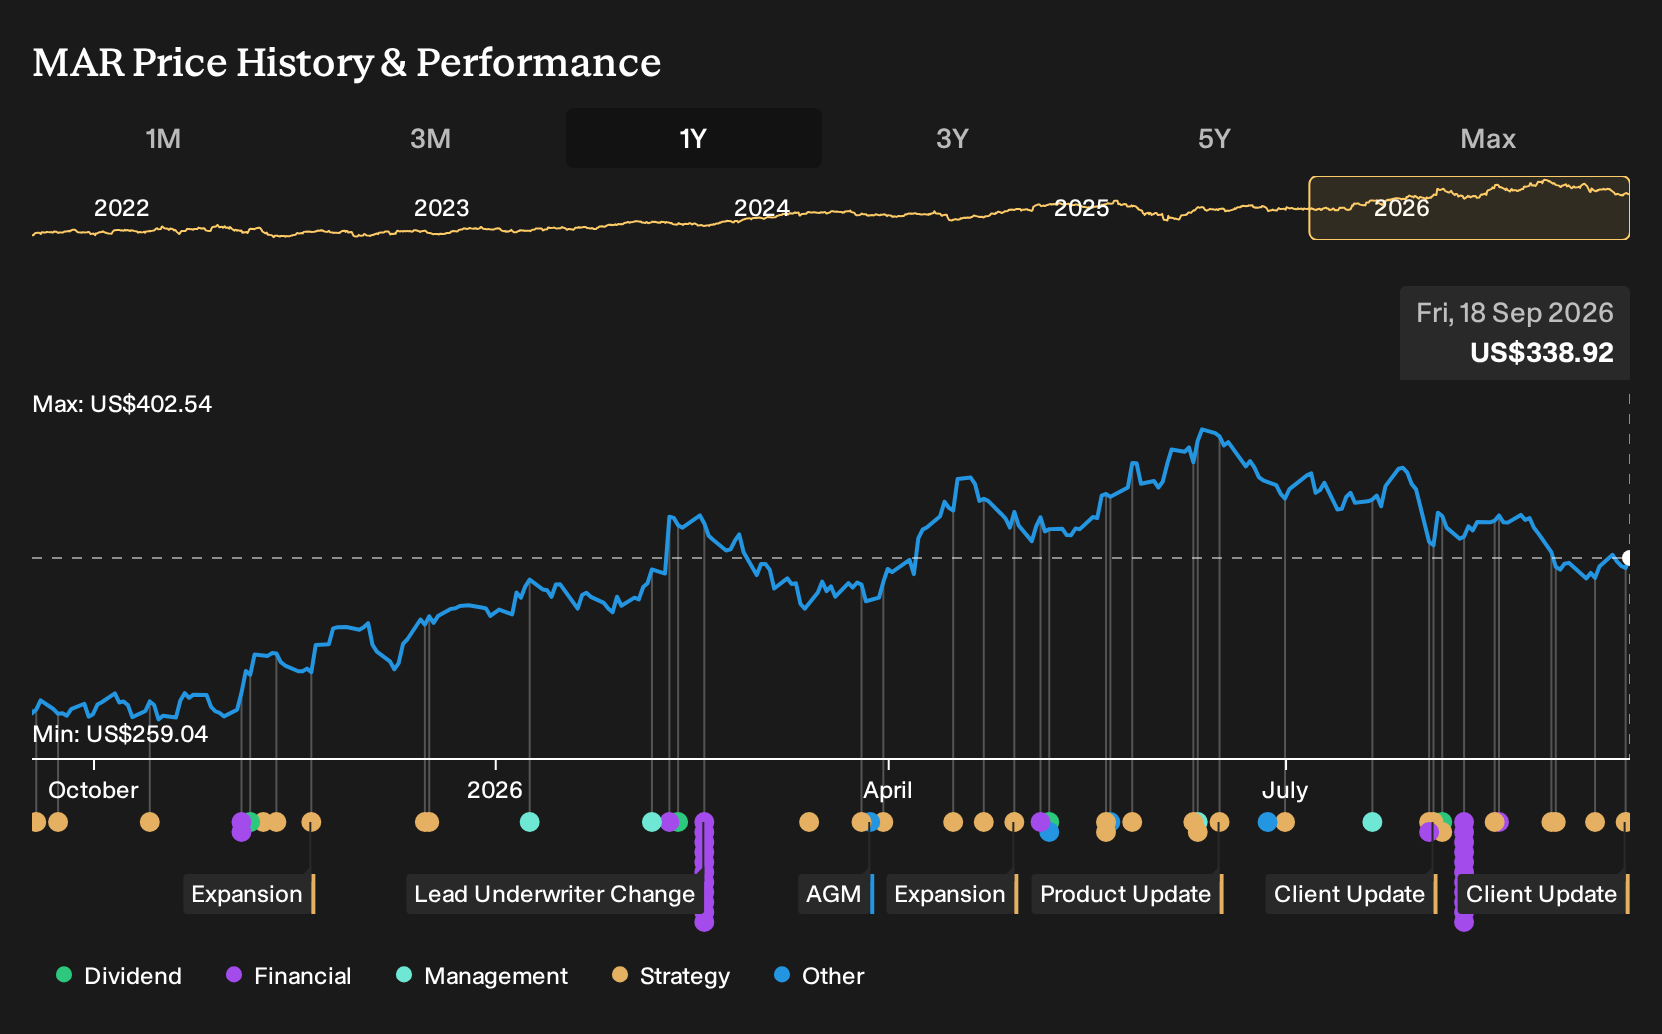
Exploring Other Perspectives
Some of the most optimistic analysts focus on pipeline execution rather than RevPAR risk. Before this Ritz Carlton Kemer news, the bullish camp was sketching Marriott International at roughly US$37.0b in revenue and about US$4.3b in earnings by 2029, versus consensus near US$30.7b and US$3.8b. That gap shows how far views can stretch, and why it can help to weigh several narratives before deciding how this new resort and the Spotnana tie up might reshape the story.
Explore 4 other Marriott International fair value estimates, including one that suggests as much as 25% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marriott International research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Marriott International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marriott International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Marriott International?
Once the Marriott International story is clear in your mind, it can help to widen the lens and compare it with other opportunities that share some of the same qualities, such as strong cash generation, balance sheet resilience, or income potential. The Simply Wall St Screener is a quick way to line those side by side so you can see which stories and risk profiles suit you best.
- For investors who want resilient businesses with measured risk, start with a curated group of 30 resilient stocks with low risk scores and see which ones align with your comfort level.
- If stable finances matter most to you, scan through the list of solid balance sheet and fundamentals (23 results) and focus on companies that pair financial strength with clear business models.
- Income focused readers can zero in on yield opportunities by reviewing the 6 dividend fortresses and assessing which payouts match their tolerance for volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com