
How Investors May Respond To Vistance Networks (VISN) Options Volatility Surges
- Aurora Networks and Kaltura previously announced that Bouygues Telecom had gone live with a unified Kaltura Cloud TV platform, with Aurora providing integration, software development, and IP video migration services across Bouygues Telecom’s multi-device IPTV footprint.
- For Vistance Networks, the more interesting angle sits in the options market, where elevated implied volatility on long-dated puts hints at investor focus on execution risk rather than customer wins alone.
- We will now see how Vistance Networks' investment narrative could be affected by this spike in implied volatility around its options activity.
Scan how traders are pricing execution risk at Vistance Networks, then compare it with other telecom and streaming infrastructure players on our curated list of 38 power grid technology and infrastructure stocks.
Vistance Networks Investment Narrative Recap
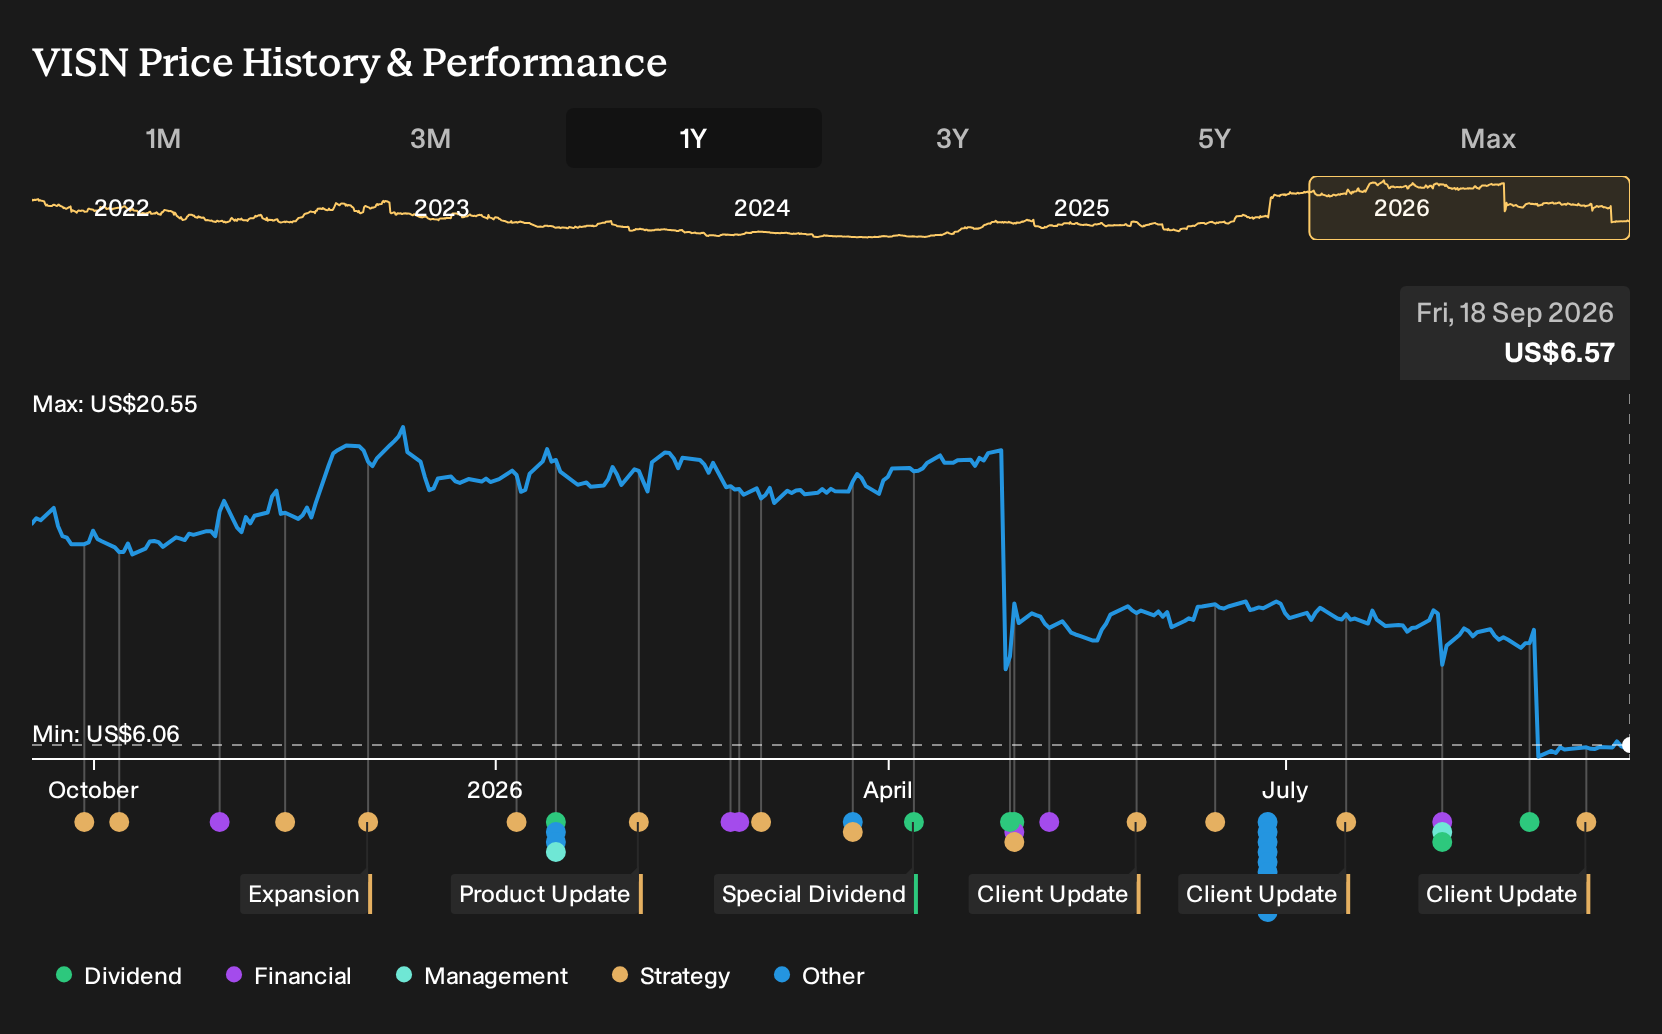
To own Vistance Networks, you need to believe the RUCKUS and Aurora segments can convert their connectivity footprint into steadier, higher quality earnings, even as the business is currently loss making. The key near term catalyst is execution on large operator and enterprise projects that can stabilize revenue after a period of volatility in both the share price and reported results.
The biggest risk sits in project cyclicality, customer concentration and a balance sheet funded entirely by higher risk external borrowing. Elevated implied volatility on long dated puts reinforces that traders are focused on execution rather than customer wins alone. Any slip in contract delivery or IP video transitions could quickly feed back into funding costs and investor confidence.
The Bouygues Telecom Cloud TV deployment with Aurora Networks is the most relevant proof point for this options driven story. It shows Vistance Networks helping a large operator consolidate legacy video systems onto a single IP platform across set top boxes, mobile and smart TVs, using integration and IP video migration capabilities that are hard to replicate at scale.
For your thesis, this kind of contract underpins the catalyst that matters most. Large, complex migrations can support RUCKUS and Aurora utilization, help offset revenue pressure that analysts expect over the next three years, and give the group more room to work down losses. The operational test is the repeatability of these wins across other telecom and data center clients without cost overruns or delivery delays.
Vistance Networks is modeled to reach revenues of $2.4 billion and earnings of $89.6 million by 2029, based on analyst forecasts that include 7.6% yearly revenue growth and a projected earnings decline of $165.8 million from current earnings of $255.4 million.
Uncover why Vistance Networks' fair value indicates a 252% potential upside to its current price, before sentiment around Vistance Networks closes that discount.
Exploring Other Perspectives
One alternate view on Vistance Networks leans heavily on contract momentum rather than execution risk. The most optimistic analysts were already penciling in about $2.5b of revenue and $79.4m of earnings by 2029 before this Bouygues Telecom win, which could shift those expectations again. Opinions clearly span a wide range, so explore several angles before you decide where you land.
Explore 5 other Vistance Networks fair value estimates, including one that suggests potential upside of as much as 281% from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Vistance Networks research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vistance Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistance Networks' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vistance Networks?
If you want to stress test your view on Vistance Networks, compare it with other opportunities that share similar financial traits but sit in very different corners of the market. The Simply Wall St Screener can help you line up those alternatives quickly, then filter by balance sheet strength, dividend profile, or valuation so you can see where Vistance really fits in your broader watchlist.
- For investors who care most about downside protection and steady finances, start with a list of solid balance sheet and fundamentals (23 results) to see which companies pair robust balance sheets with durable fundamentals.
- If income is your focus, scan a 6 dividend fortresses that highlights businesses offering higher yields with an emphasis on sustainability, not just headline payout ratios.
- When you want to hunt for opportunities that are less picked over, filter through a 16 high quality undiscovered gems and compare their fundamentals side by side with Vistance Networks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com