
Byline Bancorp (BY) Following Its Digital Banking Push Is The Stock Still Undervalued
Byline Bancorp (BY) has drawn fresh attention as investors weigh its recent share performance. The stock last closed at US$37.52 and has shown mixed returns over the past week, month, and past 3 months.
Recent trading has cooled a little, with the share price down over the past week. Even so, Byline Bancorp still shows strong momentum when you zoom out, supported by a 29.20% year to date share price return and a 33.74% 1 year total shareholder return.
Scan the regional banking space alongside Byline Bancorp by checking our hand picked list of solid balance sheet and fundamentals (23 results) for comparison.
After a strong run and a recent pullback, Byline Bancorp now trades below analyst targets while sitting at a deeper intrinsic discount. Does that gap signal mispricing, or is it a fair reflection of the fundamentals?
Most Popular Narrative: 13% Undervalued
Byline Bancorp's widely followed narrative pegs fair value at $43.20, which sits above the recent $37.52 close and frames the current discount as a question of execution rather than hype.
Byline's continued investment in digital banking upgrades, demonstrated by the completion of a major online banking systems update, positions the company to attract and retain younger, tech-savvy customers, with the possibility of future deposit growth and enhanced fee income.
Byline's focus on disciplined expense management and ongoing efforts to reduce their cost-to-asset ratio as the bank scales up indicates an emphasis on improving operating leverage and margins.
See why 0 investors see Byline Bancorp as 13% undervalued.
Result: Fair Value of $43.20 (UNDERVALUED)
Still, the Byline Bancorp story can break if Midwest credit quality weakens further or if integration and regulatory costs eat into those projected margins.
Find out about the key risks to this Byline Bancorp narrative.
Another View On Byline Bancorp's Valuation
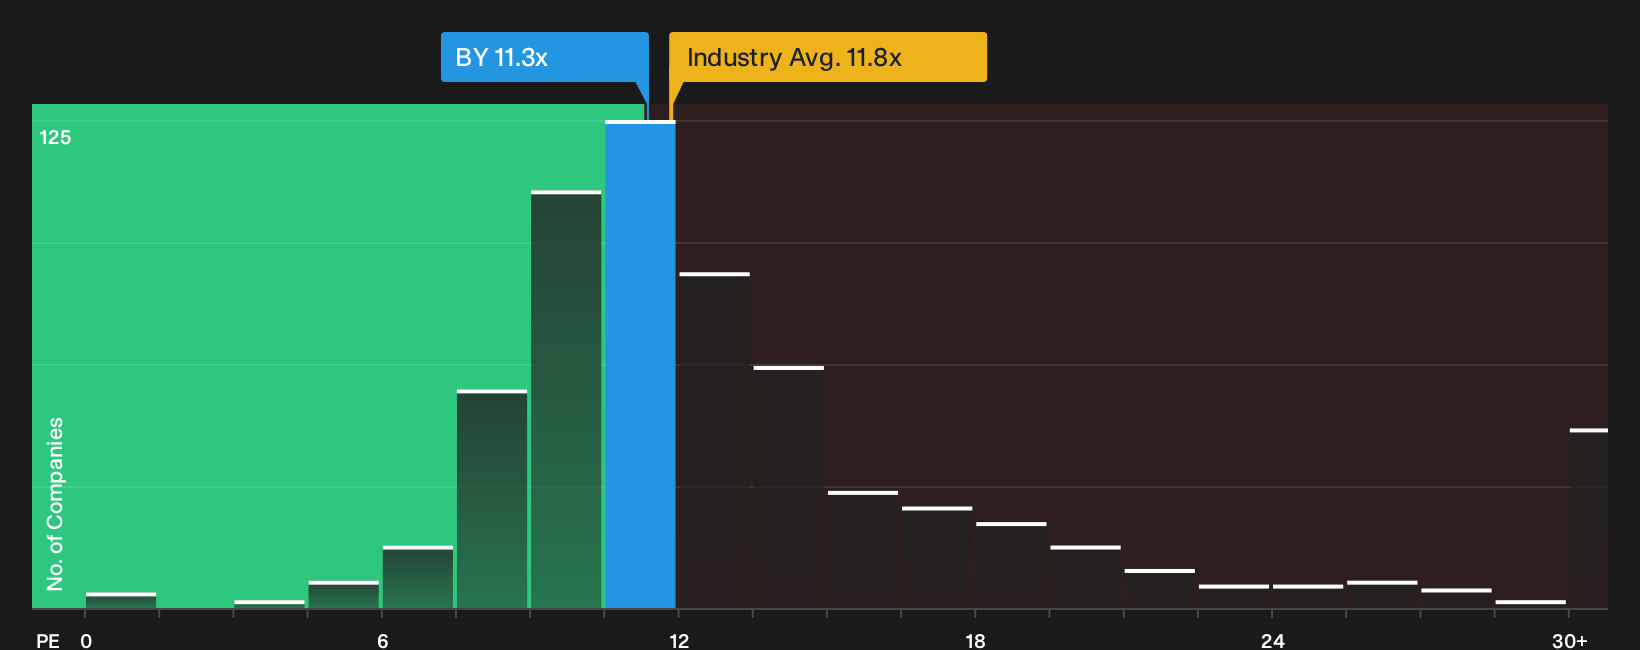
On the surface, Byline Bancorp looks cheap against the analyst fair value and our own cash flow estimate. Its current P/E of 11.3x sits slightly above the fair ratio of 10.4x, even though it is below both US Banks at 11.8x and peer averages at 20.6x. Is that a margin of safety or a value trap in disguise?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in Byline Bancorp's story so far. If you want to move fast and build your own view, weigh both sides with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Byline Bancorp?
If Byline Bancorp has your attention, do not stop here. Broader ideas can sharpen your watchlist, refine your risk profile, and reveal opportunities you might otherwise miss.
- Target value opportunities with strong fundamentals and clear pricing gaps using our hand picked 33 high quality undervalued stocks.
- Strengthen your defensive side by reviewing companies that score well for resilience and balance sheet quality in the 30 resilient stocks with low risk scores.
- Scan our focused 16 high quality undiscovered gems to explore companies that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com