
Is Wise Group (WSE) Undervalued As Class Actions Raise Fresh Regulatory Questions?
Wise Group (WSE) is now at the center of multiple securities class actions after disclosures of a Belgian criminal investigation, alleged regulatory failings on anti-money laundering controls, and a denied U.S. trust bank license.
The regulatory headlines now sit against a weaker tape for Wise Group, with the share price down 4.7% over the past week and 8.5% over the last month. However, a 90 day share price return of 5.6% and a 3 year total shareholder return of 35.0% show that longer term holders have still seen gains, even as the 1 year total shareholder return has fallen 20.8%.
Spot opportunities beyond Wise Group by scanning a curated set of resilient financials and cross-border payment peers in our list of solid balance sheet and fundamentals (23 results).After a sharp pullback, Wise Group is still priced above where many recent buyers came in. The central question now is whether most of the upside has already played out or whether the valuation still leaves meaningful room ahead.
Most Popular Narrative: 32% Undervalued
The most followed narrative puts Wise Group's fair value at $16.94, which sits well above the last close at $11.45. As a result, the gap between price and narrative expectations is doing a lot of work in this story.
Customer balances of US$39b, including US$9b held through Wise Assets, together with an interest income framework that targets sharing 80% of yield above 1% with customers, create a recurring income stream that can support net revenue while still allowing for margin discipline.
See why 1 investors see Wise Group as 32% undervalued.
Result: Fair Value of $16.94 (UNDERVALUED)
Still, the current narrative around Wise Group could crack if regulatory actions escalate from the class actions or if interest income on US$39b of customer balances weakens materially.
Find out about the key risks to this Wise Group narrative.
Another View On Wise Group’s Valuation
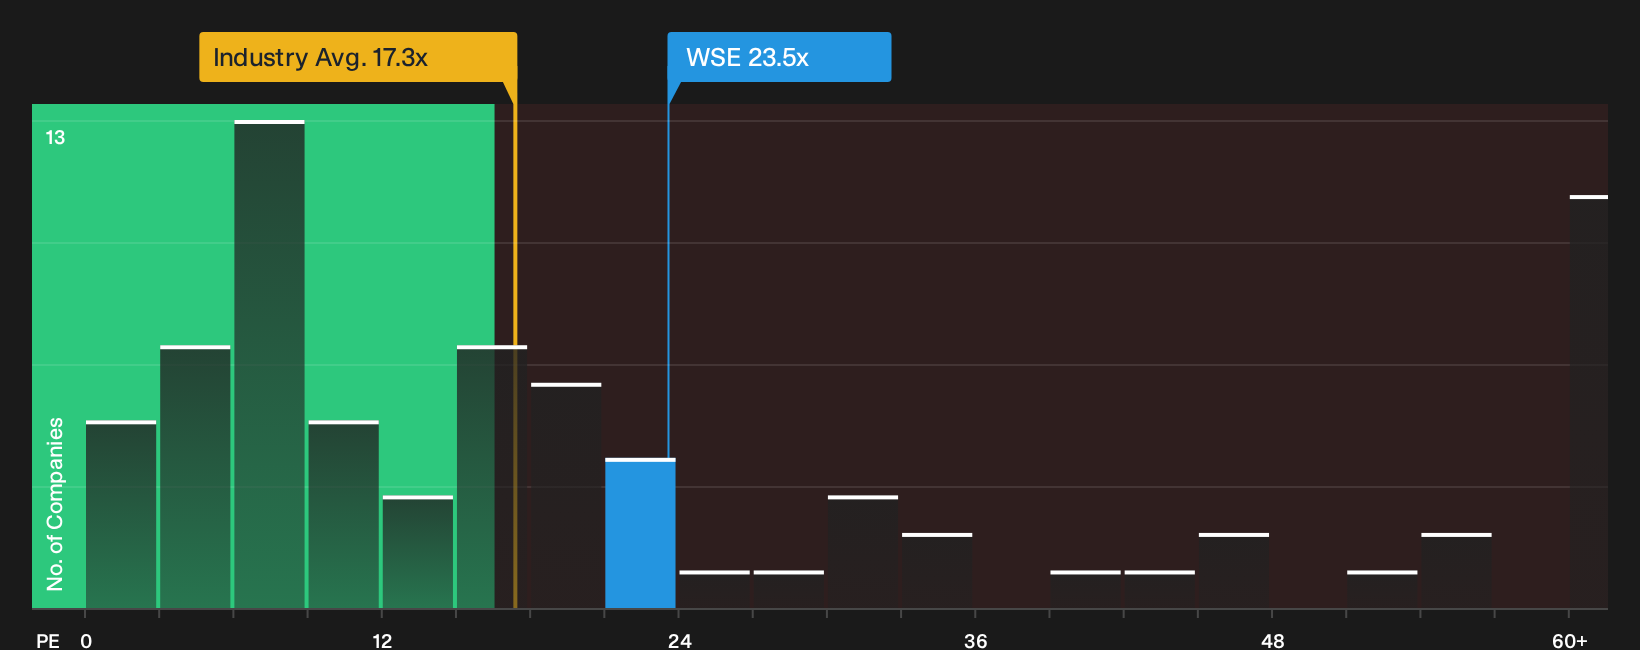
Wise Group screens as undervalued on narrative fair value and DCF, with the SWS DCF model pointing to a future cash flow value of $13.05 against a $11.45 share price. A separate lens comes from the current P/E of 23.5x, which sits well above the US Diversified Financial industry at 17.3x, the peer average at 19.4x, and the fair ratio of 16.3x. That gap suggests investors need to weigh the potential upside implied by cash flows against the risk that the earnings multiple drifts closer to that lower fair ratio over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed headlines and valuation signals can pull Wise Group in different directions, so move quickly from reading to testing the numbers yourself and forming your own stance. If you want a structured view of what the market currently sees as the upside case, take a closer look at the 3 key rewards.
Looking For More Investment Ideas Beyond Wise Group?
Do not stop with Wise Group. Broaden your watchlist with fresh ideas that match your risk profile and income goals while staying grounded in real financial data.
Use the Simply Wall St screener to quickly test different angles before committing capital.
- Target potential bargain opportunities by scanning a curated 33 high quality undervalued stocks list that filters for quality fundamentals and pricing that may leave room for upside.
- Build a steadier income stream by reviewing 6 dividend fortresses that combine higher yields with balance sheets you can actually scrutinize.
- Protect your downside first by focusing on 30 resilient stocks with low risk scores so sharp drawdowns are less likely to catch you off guard.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com