
Will New Fund Stake Change Ryan Specialty’s (RYAN) Narrative
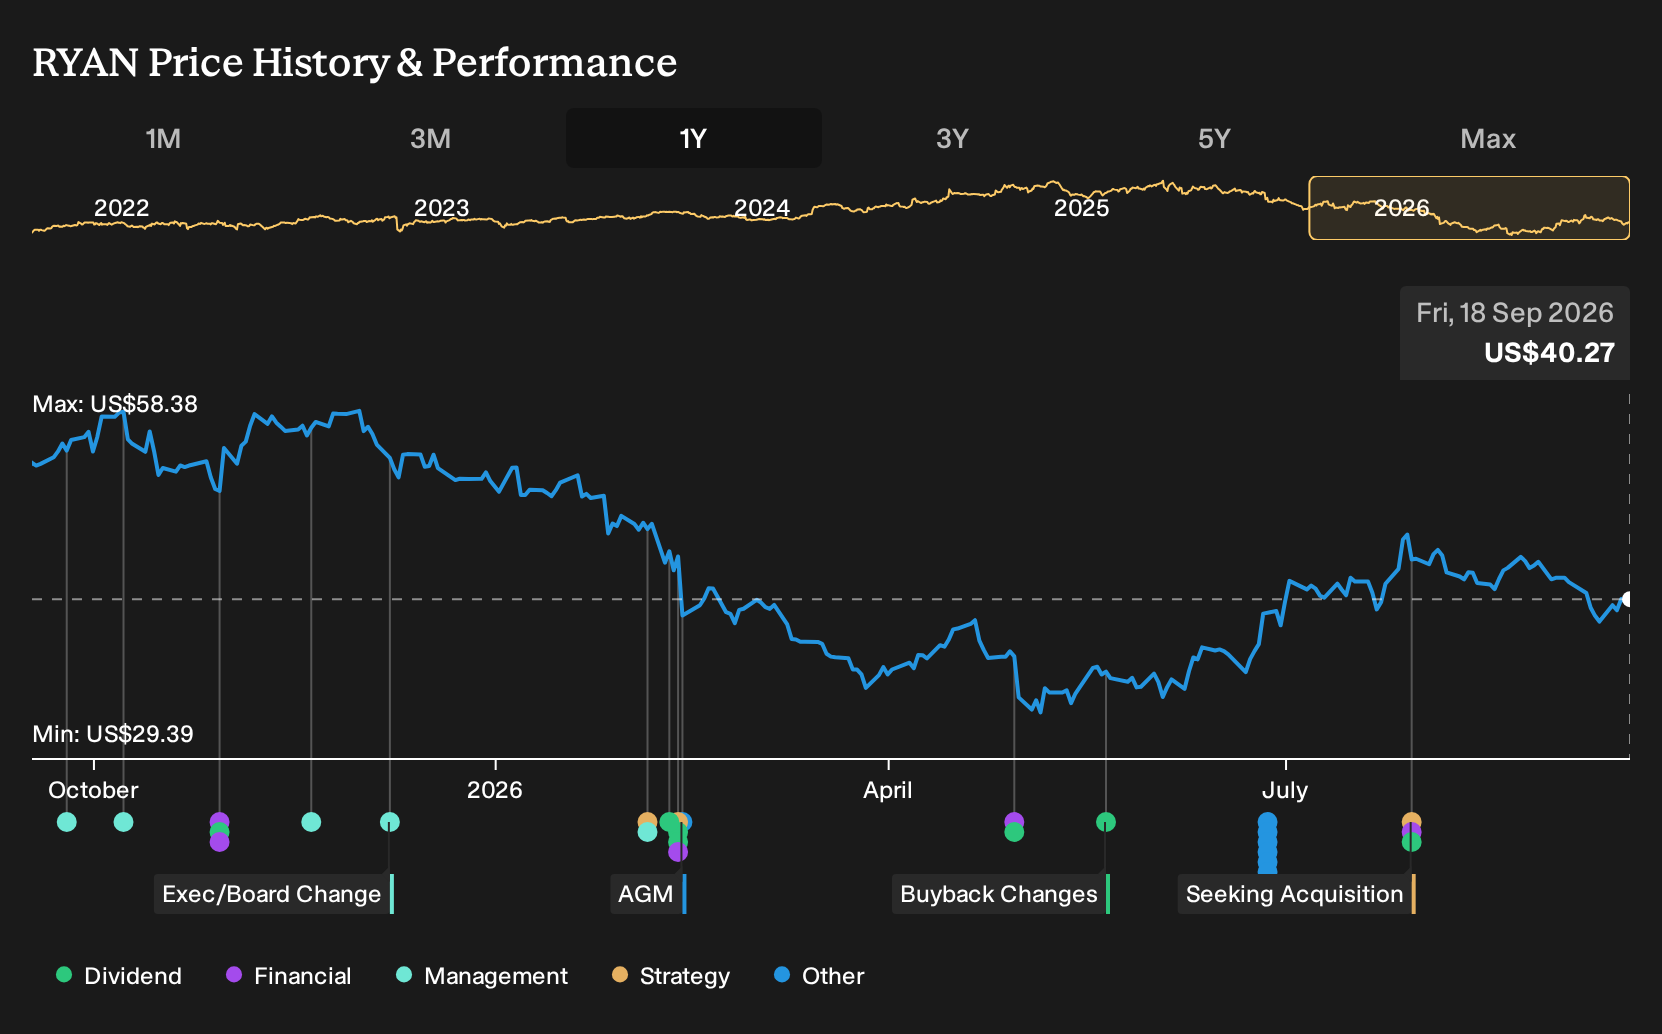
- Fenimore Asset Management recently initiated a position in Ryan Specialty Holdings after insurance rate softness and a reduced earnings outlook, focusing on the firm’s specialty insurance services across distribution, underwriting, and risk management.
- An important angle is that Ryan Specialty’s founder Pat Ryan bought shares during weakness, which reinforces investor attention on the business model’s resilience rather than short term pricing conditions.
- We will now look at how Ryan Specialty Holdings' investment narrative could be affected by Fenimore’s new stake and insider buying.
Scan opportunities with similar resilience by reviewing the hand picked 30 resilient stocks with low risk scores that share Ryan Specialty Holdings' focus on durable business models and risk management.
Ryan Specialty Holdings Investment Narrative Recap
To own Ryan Specialty Holdings, you need to be comfortable with a specialist intermediary that leans into complex risks while absorbing hits from softer property pricing and heavier near term spending. The near term swing factor is how quickly submission volumes and specialty lines offset weaker property rates. Fenimore’s new stake and Pat Ryan’s buying do not change that operational reality.
The biggest near term risk is that prolonged soft pricing and higher operating expenses from platform investments keep margins tight for longer. Integration execution and reliance on key carrier partners remain important watchpoints, but this news does not materially shift those issues. It mostly reinforces focus on business quality over short term conditions.
There are no fresh corporate announcements directly tied to Fenimore’s entry, so the most relevant reference point is still Ryan Specialty Holdings’ existing push into higher margin specialty lines and delegated authority programs. Those initiatives, including areas like Ryan Re and Alternative Risk, sit at the center of the current earnings debate because they raise costs upfront.
Execution on those programs is a practical catalyst. If submissions and fee income track well through softer property cycles, that supports the case that recent rate pressure is cyclical noise rather than structural damage. If integration stumbles or carrier relationships weaken, the same initiatives could leave the business with elevated expense, tighter cash coverage of debt, and more volatile results.
Ryan Specialty Holdings' current earnings are US$99.0 million and analysts collectively expect this to reach US$565.7 million by 2029, which is an increase of about 5.7x. The forecasts assume revenue reaches US$4.0 billion and grows by 7.7% per year over the period to 2029.
Uncover why Ryan Specialty Holdings' fair value indicates a 26% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
One alternate view puts acquisition integration in the spotlight. You saw consensus pointing to US$4.0b in 2029 revenue and US$565.7 million in earnings. The most optimistic analysts were already sketching US$4.2b and US$807.4 million in earnings. If Fenimore’s stake and Pat Ryan’s buying change sentiment, those pre news assumptions may shift. It can be useful to explore both stories before deciding.
Explore 4 other Ryan Specialty Holdings fair value estimates, including one that suggests as much as 77% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ryan Specialty Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ryan Specialty Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryan Specialty Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Ryan Specialty Holdings?
If the Ryan Specialty Holdings story has sharpened your thinking about risk and resilience, it can be useful to size up a wider field of companies with similar qualities using the Simply Wall St Screener.
- For investors who care most about capital strength and staying power, scan a list of solid balance sheet and fundamentals (23 results) that can handle tougher periods without relying on aggressive funding.
- If you are hunting for quality at a reasonable price, review a 33 high quality undervalued stocks that blends robust fundamentals with valuations analysts might consider attractive.
- Income focused investors can weigh up a 6 dividend fortresses that combines higher yields with business models built around consistent cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com