
3 U.S. Financial Stocks Retail Investors Are Watching After The Latest Fed Rate Move
The Fed has just pressed rates a little higher, yet still calls policy “accommodative,” and that mix of firmness and flexibility is exactly what can shake up pricing across large U.S. banks and insurers. When the market scrambles to reprice money, some stocks quietly gain leverage over the next few years. This article unpacks that shift and spotlights three U.S. large-cap financial stocks most exposed to this latest Fed narrative.
The three large caps highlighted below are just a sample, and the full screen pulled up 40 more banks and insurers with equally compelling stories that are not covered here.
If you want to quickly sort that full universe by size, valuation, financial strength, and rate sensitivity, head straight into the U.S. Large-Cap Financials (Banks & Insurance) screener.
Unum Group (UNM)
Unum Group plugs directly into this large cap financials theme as a life and disability insurer that earns a big share of its money from investing customer reserves, so a firming rate backdrop matters a lot to how investors think about its future cash generation.
Unum Group provides employee benefits like disability, life and supplemental health cover across Unum US, Colonial Life and Unum International. Unum US generates about US$8.1b of revenue, Colonial Life US$2.1b and the Closed Block US$1.7b, and the stock is valued around US$15.1b today.
"Strategic derisking of the legacy long-term care (LTC) block through external reinsurance transactions is freeing up capital, reducing earnings volatility, and allowing management to focus on more profitable and capital-efficient core businesses, supporting steadier net income and increased share repurchases."
The real swing factor for Unum Group is what happens if a single key assumption about future claims experience moves even slightly off script.
If that claims math is where your thesis could break, the full narrative for Unum Group shows how Unum Group’s derisking, capital returns and rate exposure either compound or stall.

Fidelity National Financial (FNF)
Fidelity National Financial plugs into this large cap banks and insurance theme as a US-focused insurer and title specialist whose float and investment portfolio give investors a direct line into how a firmer Fed path can ripple through cash flows over time.
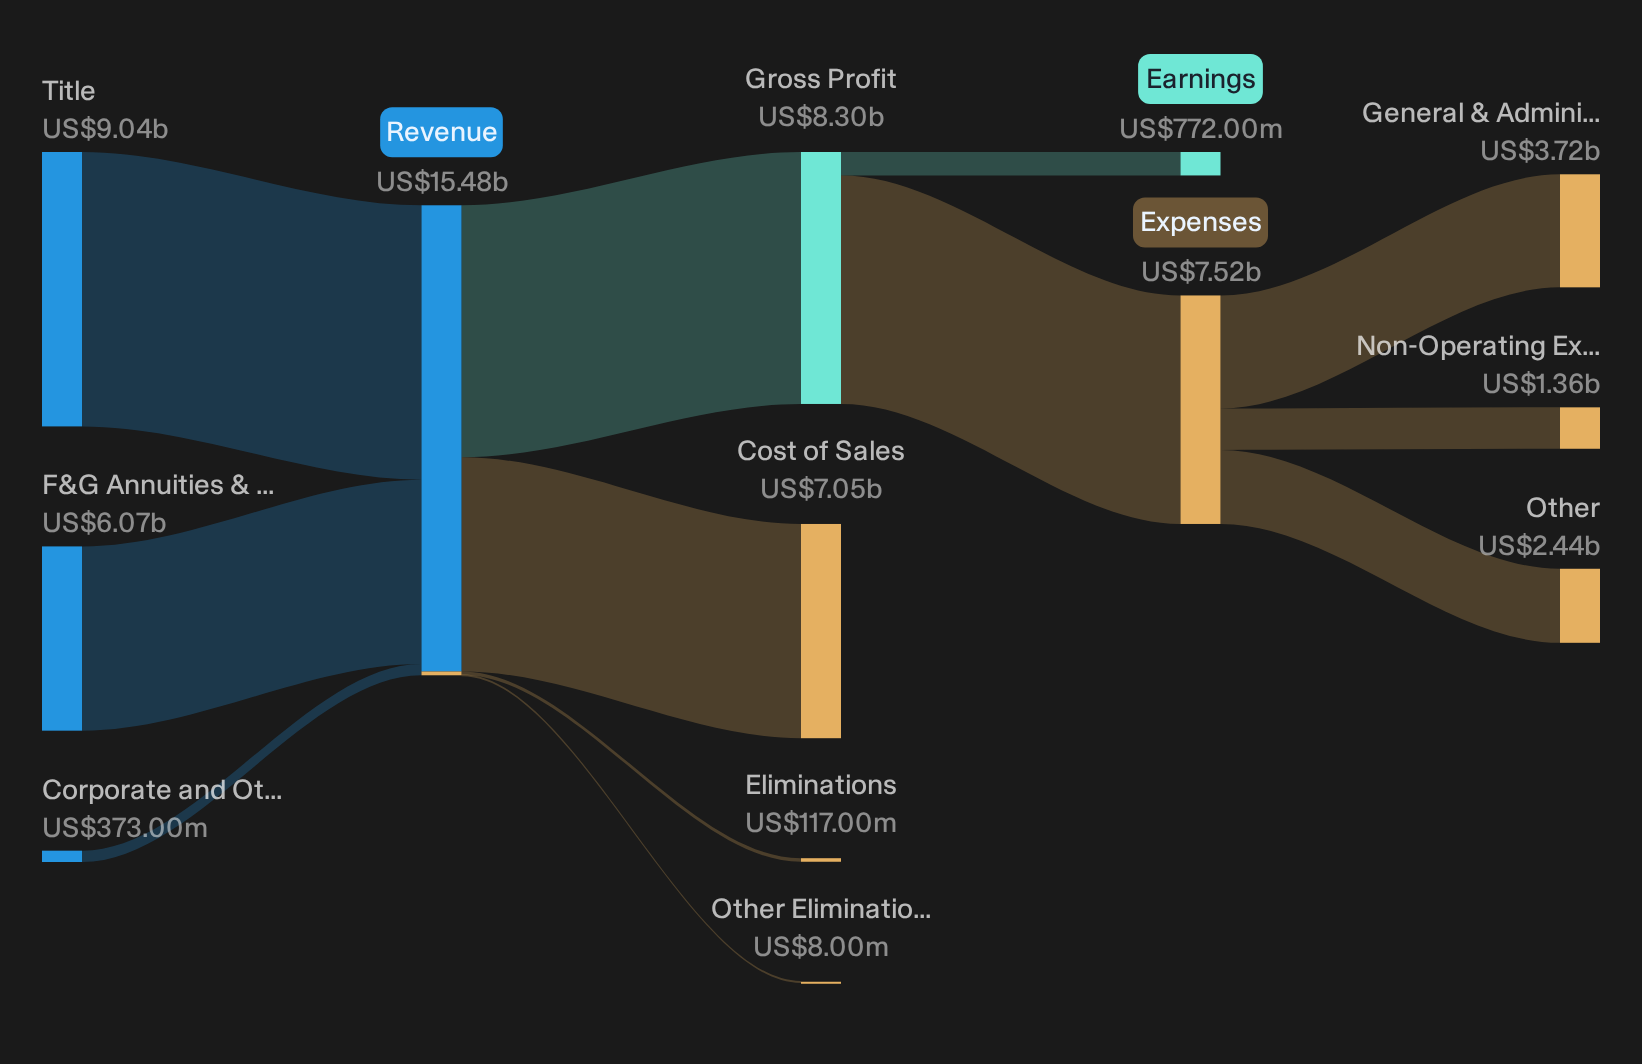
Fidelity National Financial runs a broad US real estate and insurance platform, with about US$9.0b from Title, US$6.1b from F&G annuities and life, and US$0.4b from Corporate and Other, and the stock is valued around US$11.6b today.
"Ongoing digital investment, including enhanced security, technology, and recruitment in tech-focused roles, is expected to streamline transaction processes and drive operational efficiencies, resulting in lower long-term costs and eventual net margin expansion once these up-front expenses normalize."
What happens to those efficiency gains if one stubborn cost line refuses to ease could be the real swing factor for Fidelity National Financial.
If that cost line worries you, the full narrative for Fidelity National Financial shows where Fidelity National Financial’s efficiency push could accelerate, stall, or quietly reshape long-term earnings power.
OceanFirst Financial (OCFC)
OceanFirst Financial is a regional U.S. bank holding company in the large cap banks and insurance theme, with earnings closely tied to how net interest margins react as the Fed nudges rates higher. Its community banking franchise gives that rate sensitivity real-world reach.
OceanFirst Financial generates all of its US$427.6 million in revenue from community banking services in the United States and is valued at about US$1.8b, giving it meaningful scale while still operating as a regional lender and deposit taker.
For the screener theme, OceanFirst Financial matters because its community-focused deposit base, broad loan book, and interest-earning securities link directly into how higher short and medium term rates filter into everyday banking spreads. This is exactly what investors are trying to capture here.
"The substantial investments in C&I bankers and expansion into new commercial markets are driving robust growth in the commercial loan pipeline (record $791M), positioning OceanFirst for above-peer loan and net interest income growth as population migration and small business formation continue in its regional markets. This is likely to boost both revenue and net earnings."
The real test comes if one unseen pressure on funding costs cuts into that rate-driven upside just as expectations for higher net interest margins peak.
If that funding squeeze is what you keep circling back to, the full narrative for OceanFirst Financial explains how OceanFirst Financial’s loan engine and deposit costs could quietly decouple.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities can move quickly as momentum builds, prices break out, and quiet stories stop flying under the radar. Scan these ideas before the crowd catches up and consider your options.
- Identify companies quietly building strength before sentiment catches up by running your filters through the list of solid balance sheet and fundamentals (23 results).
- Focus on resilient payouts while yields still look attractive using the curated universe inside the 6 dividend fortresses.
- Monitor the next phase of infrastructure activity by tracking power, grid, and electrification companies with the focused 38 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com