
3 Malaysia Consumer Stocks Backed By Low Inflation And Everyday Spending
Malaysia’s consumer story is entering an unusual sweet spot, with low projected inflation near 2% by 2026, fuel subsidies and price controls helping keep day to day costs in check, while interest rates stay relatively friendly. That mix can reshape how domestic consumer stocks trade and may create quiet winners before the crowd catches on. This article walks through three Malaysia Domestic Consumer Stocks that appear especially exposed to these shifting currents.
The three stocks in this article are only a small sample, and the full screen surfaced 12 more Malaysia Domestic Consumer Stocks with similarly detailed stories that are not covered here. To identify and analyze the rest, head straight to the Malaysia Domestic Consumer Stocks screener.
Nestlé (Malaysia) Berhad (KLSE:NESTLE)
Overview: Nestlé (Malaysia) Berhad produces a wide range of everyday food and beverage brands that anchor Malaysian household spending on staples.
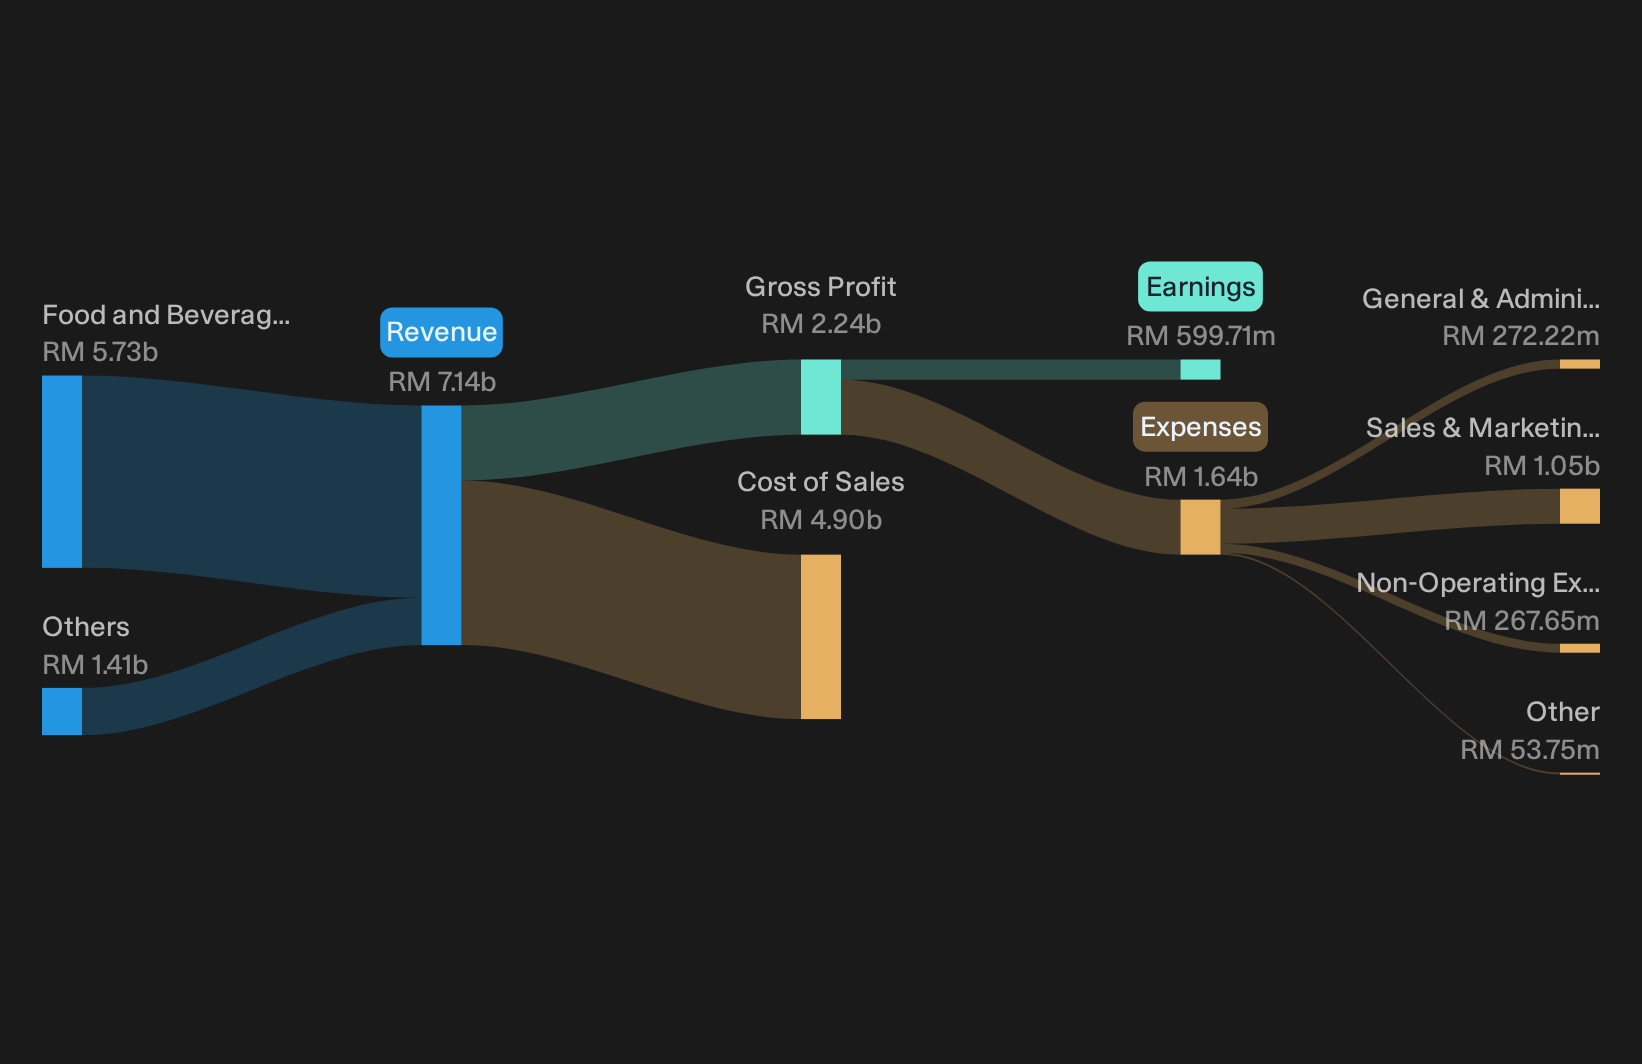
Operations: Nestlé (Malaysia) Berhad generates about MYR 5.7b from Food and Beverages and MYR 1.4b from Others, driven primarily by packaged consumer products.
Market Cap: MYR 21.0b
Nestlé (Malaysia) Berhad offers direct exposure to Malaysian grocery baskets through brands like Milo, Maggi and Nescafé, backed by consumer staples demand supported by low inflation and subsidies. Profitability and governance contribute to this consumer theme, while future returns depend on how one unseen pressure shapes pricing power and input costs.
That unseen pressure is already baked into expectations for Nestlé (Malaysia) Berhad, so walk through the 3 key rewards and 2 important warning signs to see what might quietly re-rate the story.
Mynews Holdings Berhad (KLSE:MYNEWS)
Overview: Mynews Holdings Berhad runs Malaysian convenience stores, ready to eat food production and cafes that plug directly into everyday domestic spending.
Operations: Mynews Holdings Berhad generates about MYR 924 million in revenue from Malaysian consumers, tying its fortunes closely to local household demand.
Market Cap: MYR 318.9 million
Mynews Holdings Berhad is closely linked to the Malaysia Domestic Consumer Stocks theme, with convenience outlets and fresh food aimed at shoppers whose budgets are supported by subsidies and relatively low inflation. Earnings growth expectations are described as strong and closely related to how much Malaysians spend on small daily purchases. However, the P/E premium and funding structure mean that returns are sensitive to how key pressures on the business develop.
Those pressures are already starting to shape expectations, so check the 3 key rewards and 1 important warning sign to see where Mynews Holdings Berhad’s story could quietly accelerate or stall.

Mr D.I.Y. Group (M) Berhad (KLSE:MRDIY)
Overview: Mr D.I.Y. Group (M) Berhad runs MR.DIY-branded home improvement and mass-merchandise stores that concentrate Malaysian household and everyday spending.
Operations: Mr D.I.Y. Group (M) Berhad generates about MYR 5.1b from home improvement retail, with roughly MYR 5.1b from Malaysia and MYR 41 million from Brunei.
Market Cap: MYR 12.1b
Mr D.I.Y. Group (M) Berhad provides focused exposure to Malaysian consumer wallets, with over MYR 5.1b in home-focused retail tied to domestic purchasing power, a 34.2% ROE and a 6.25% dividend yield in a low-inflation, steady-rate backdrop. However, one unresolved funding and payout tension could be decisive for margins and cash returns if conditions shift.
That funding and payout trade off is already in focus, so see how it affects the balance sheet and cash flow in the Mr D.I.Y. Group (M) Berhad financial health report
Seeking Fresh Alternatives Beyond These Stocks
Fresh opportunities move first. Breakout stories gain momentum, under the radar for now, then get caught once the crowd rushes in. Scan these ideas while it matters and get in early.
- Spot resilient compounding potential by scanning a curated group of companies with strong finances using the list of solid balance sheet and fundamentals (197 results).
- Ride early momentum in quality miners by checking a focused basket of producers through the 36 elite gold producer stocks.
- Track emerging themes in automation by sifting through targeted industrial plays inside the 95 robotics and automation stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com