
Preferred Share Sale Might Change The Case For Investing In National Bank Of Canada (TSX:NA)
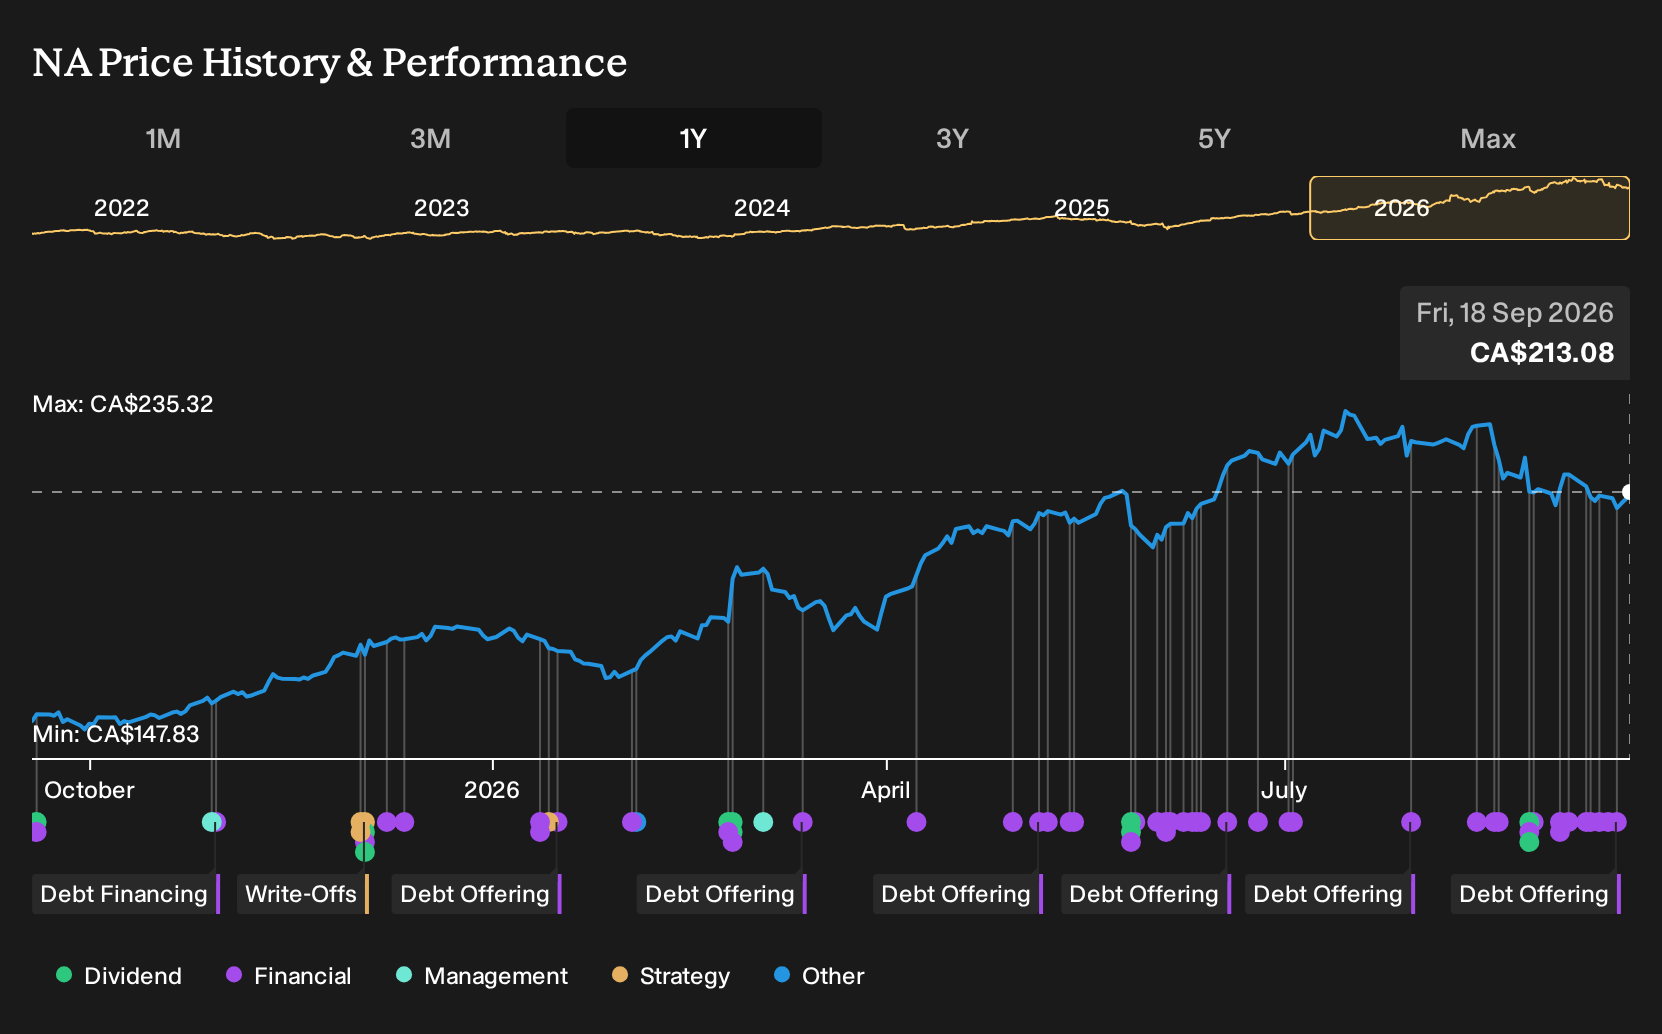
- National Bank of Canada has been active in funding markets, including a past CAD 750 million variable rate preferred share issue and multiple recent US dollar fixed income offerings with callable and variable or fixed coupons.
- The mix of non convertible preferred shares, covered bonds and senior unsecured notes suggests management is fine tuning funding costs, duration and loss absorption without relying on common equity issuance.
- We will examine how this increased fixed income issuance by National Bank of Canada interacts with the existing investment narrative around capital.
Scan how National Bank of Canada's funding moves compare with other issuers by reviewing our hand picked list of solid balance sheet and fundamentals (7 results) for potential ideas.
National Bank of Canada Investment Narrative Recap
To stay invested in National Bank of Canada you need to be comfortable with a Canada focused lender that is still heavily tied to Quebec, integrating Canadian Western Bank, and spending meaningfully on technology. The core thesis leans on stable credit quality, disciplined costs, and measured revenue growth rather than outsized expansion.
The near term swing factor remains how funding costs and net interest margins settle as the rate backdrop evolves. Recent fixed income issuance, including large covered and preferred deals, changes the funding mix but does not obviously alter that core earnings driver. Key risks still sit in credit losses, regional softness, and tech spend overruns.
The new CAD 750 million variable rate preferred share offering is the clearest link to the capital story. It adds a non convertible, non cumulative layer that ranks between common equity and senior debt. For an equity holder this matters because it touches on loss absorption, dividend flexibility, and how the bank funds balance sheet growth.
Interest sensitive preferreds and fixed to floating covered bonds together shape how National Bank of Canada faces ongoing NIM pressure and credit risk. If funding remains available on acceptable terms, management has more room to focus on CWB integration, digital projects, and growing commercial and wealth franchises. If credit costs or regional strains rise, that extra hybrid capital could be tested.
National Bank of Canada's current analyst narrative links to 2029 forecasts that call for CA$18.0b in revenue and CA$6.0b in earnings in 2029, based on 7.2% yearly revenue growth and an earnings increase of about CA$1.3b from CA$4.7b today.
Uncover why National Bank of Canada's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community currently includes 2 separate fair value views on National Bank of Canada, ranging from about CA$223.92 to CA$294.73 per share. Those numbers were set before the latest preferred and bond deals and before upcoming conference commentary. Treat them as starting points, then compare several alternative opinions before deciding how this funding shift might affect your own expectations.
Explore another National Bank of Canada fair value estimate, including one that suggests as much as 38% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your National Bank of Canada research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for National Bank of Canada. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Bank of Canada's overall financial health at a glance.
Looking for more National Bank of Canada style investment ideas?
If National Bank of Canada is on your radar because of its balance sheet, capital tools and income profile, it can help to widen the lens and compare similar opportunities side by side. The Simply Wall St Screener lets you filter by quality, risk and income characteristics so you can build a watchlist that fits your own preferences rather than relying on a single story.
- For investors who care most about resilient financial footing and clean fundamentals, start with a list of solid balance sheet and fundamentals (7 results) that filters for sturdier balance sheets and steadier cash flows.
- If your priority is paying less for quality, look at a 9 high quality undiscovered gems that surfaces financially solid businesses which are not widely followed.
- Income focused investors can focus on reliability first by scanning a 1 dividend fortresses that zeroes in on higher yielding payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com