
Earnings Outlook Upgrade Change The Bull Case For Advanced Energy Industries Stock?
- Advanced Energy Industries is drawing attention as revenue and EPS have grown over the past two years while return on invested capital has weakened, suggesting recent spending has not yet translated into stronger profitability.
- The company now carries a Strong Buy Zacks Rank and higher full year earnings estimates, yet still trails its wafer fabrication peers, which highlights both improving expectations and competitive pressure within its core industry.
- We will now look at how Advanced Energy Industries' improving earnings outlook could reshape the existing investment narrative for the business.
Scan beyond Advanced Energy Industries and see how other chip equipment players with strong earnings momentum and mixed ROIC trends compare inside the 38 power grid technology and infrastructure stocks
Advanced Energy Industries Investment Narrative Recap
For an investor in Advanced Energy Industries, the core belief is that demand for precision power solutions in data centers, AI hardware, and chip fabrication can sustain the business through bumps in share price and return on invested capital. Recent weakness in the stock and softer ROIC point to investment-heavy years where cash is going out faster than visible returns are coming in.
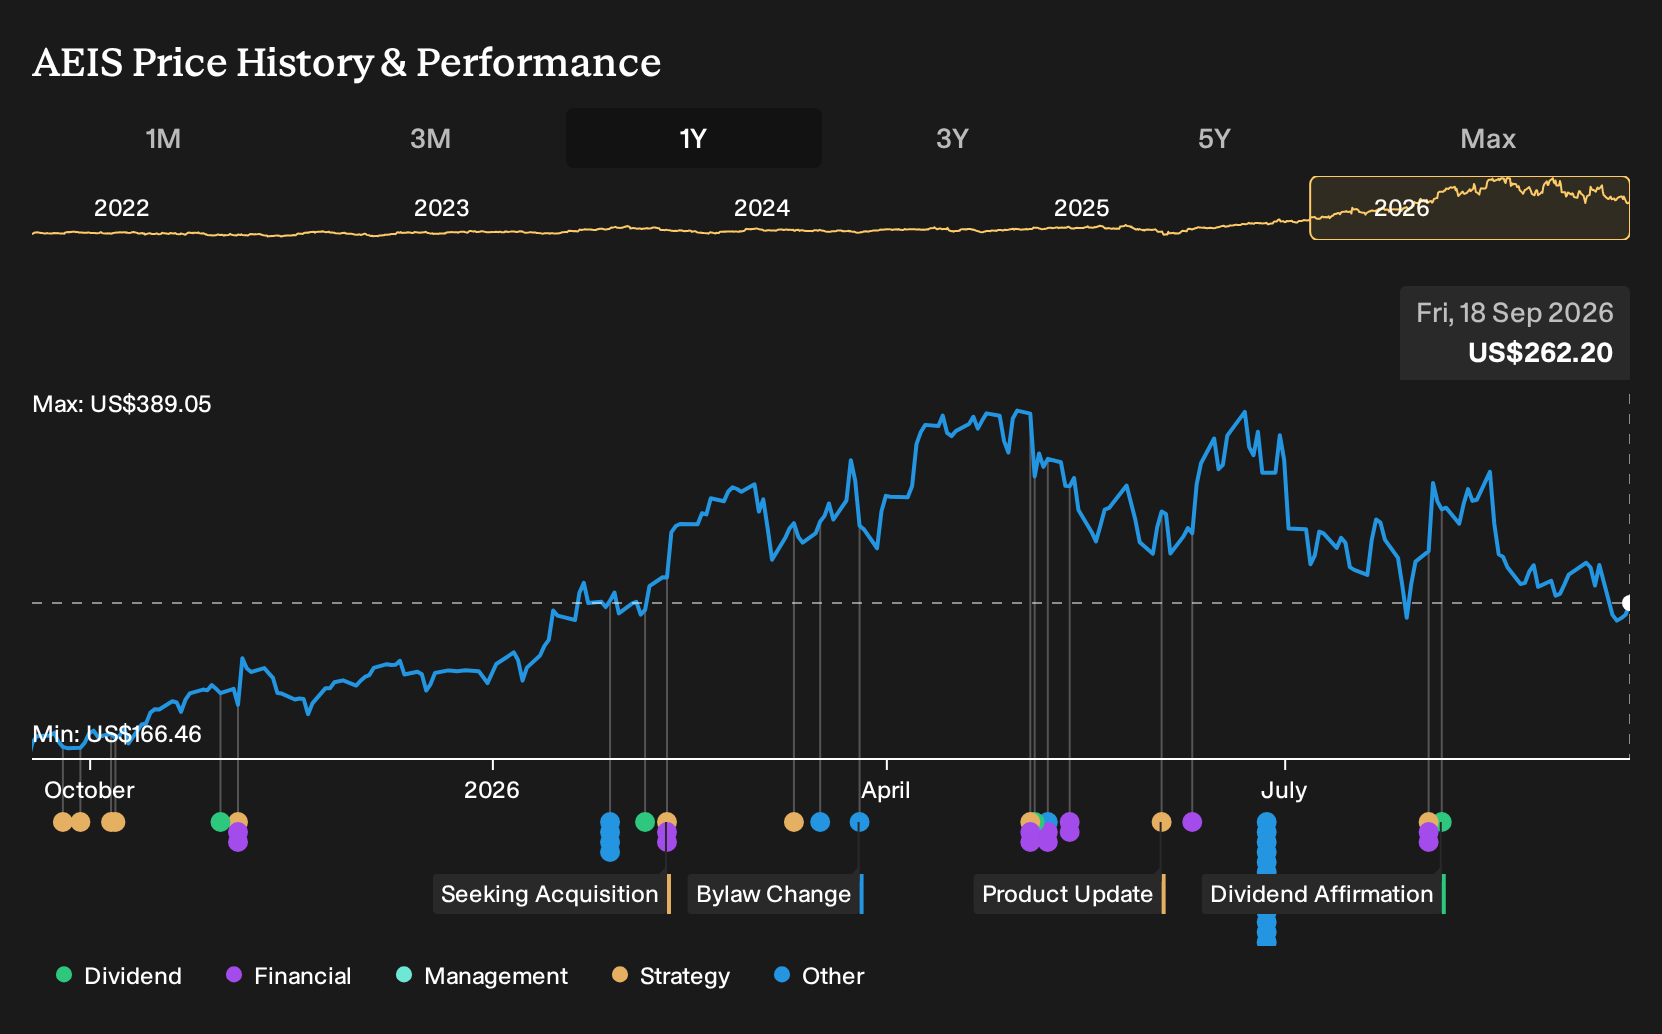
The key short term catalyst is whether those past outlays in new platforms, capacity, and efficiency start to support earnings and margins, especially with revenue and EPS already showing momentum. The biggest risk right now is the concentration in large hyperscale customers and exposure to semiconductor and tariff cycles. The recent 20.1% share price drop appears to reflect these concerns more than any clear change in day to day operations.
Recent commentary around Advanced Energy Industries centers on the stronger earnings outlook, including higher full year estimates alongside a Zacks Rank of #1 and a 23.1% uplift in projected earnings. This aligns with the narrative that prior investment is now feeding into profitability, even as ROIC has been under pressure and needs to stabilize for this story to feel durable.
For you as a shareholder, the relevance is simple. A more constructive earnings profile can support the case that recent capital spending, factory changes, and product mix shifts are starting to gain traction, which directly ties into earlier catalysts around data center, semiconductor, and Industrial & Medical demand. The offset remains clear as well, with volatility in hyperscaler budgets, tariffs, and wafer fab peers outpacing AEIS, all keeping execution risk front and center.
Advanced Energy Industries Earnings Assumptions In Focus
Advanced Energy Industries now sits on a detailed analyst playbook that spells out what needs to happen for the stronger earnings story to hold together. Revenue is modeled to climb at 21.2% a year over the next three years, while profit margins are expected to move from 10.1% today to 19.8% by 2029. This would mark a very different earnings profile than the one reflected in the current numbers.
On the earnings side, forecasts call for net income to reach US$671.3 million by around 2029, up from US$191.7 million today. That implies an increase of roughly US$479.6 million in profit over the period, with earnings per share projected at US$14.37 if share count grows as anticipated. These assumptions sit behind the current analyst targets and provide a concrete set of figures to compare with individual expectations for data center, semiconductor, and Industrial & Medical demand.
Advanced Energy Industries' narrative projects US$3.4 billion in revenue and US$671.3 million in earnings by 2029. This would require 21.2% yearly revenue growth and an earnings increase of about US$479.6 million from US$191.7 million today.
Uncover how Advanced Energy Industries' fair value indicates a 64% potential upside to its current price, which could narrow quickly once sentiment catches up.
Exploring Other Perspectives
One alternate view puts Advanced Energy Industries’ new Thailand facility at the center of the risk story. The most cautious analysts worry that if second wave cloud and enterprise customers adopt high voltage DC more slowly, even with revenue forecasts of US$3.8b and earnings of US$845.8m by 2029, expectations could reset. These projections were set before the recent share price drop, so you should treat them as moving parts that could shift as fresh information lands.
Explore 4 other Advanced Energy Industries fair value estimates, including one that suggests it could be worth just $370.00!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Advanced Energy Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Advanced Energy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advanced Energy Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Advanced Energy Industries?
If you want to pressure test the Advanced Energy Industries thesis against other opportunities, cast a wider net using the Simply Wall St Screener. You can quickly line up different businesses on earnings quality, balance sheet strength, and risk so your portfolio is built on more than one story.
- For investors focused on resilient performers with fewer red flags, start by scanning a set of 30 resilient stocks with low risk scores that score well on stability and downside protection.
- If income is a priority, compare Advanced Energy Industries with a curated group of 6 dividend fortresses that combine meaningful yields with underlying business strength.
- For those hunting for underfollowed opportunities, widen your watchlist with a collection of 16 high quality undiscovered gems that pair solid fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com