
Live Sports Streaming Might Change The Case For Investing In United Airlines Stock (UAL)
- United Airlines Holdings recently began offering live professional and college football on Starlink-equipped seatback screens through a new agreement with DISH Network, now covering more than 200 aircraft on roughly 700 domestic flights per day and targeting nearly 700 planes by early next year.
- The move ties premium in-flight entertainment directly to MileagePlus membership and United Airlines Holdings' broader push into upgraded cabins and larger, more efficient aircraft, linking customer loyalty, product differentiation, and ongoing fleet investment to its profitability focus under higher fuel and operating costs.
- We will look at how United Airlines Holdings' live sports rollout via Starlink reshapes the existing investment narrative around premium differentiation.
Scan how United Airlines Holdings' push into premium in-flight experiences compares with other carriers focusing on stronger products and balance sheets by reviewing the curated list of solid balance sheet and fundamentals (23 results).
United Airlines Holdings Investment Narrative Recap
Owning United Airlines Holdings means believing that premium products, loyalty engagement and a modern fleet can support earnings in a capital intensive, cyclical industry. Management is pushing larger, more efficient aircraft and higher end cabins while also raising fares to offset fuel expenses. The live sports rollout fits that push but does not change the thesis on its own.
In the near term, the key swing factor is whether fare increases and premium demand offset higher fuel and interest costs. The biggest risk is that heavy debt and operational complexity, especially at congested hubs, limit flexibility if demand softens or reliability issues reappear.
The DISH and Starlink agreement is the clearest operational tie in to this catalyst story. Live football and wider streaming on roughly 700 planes by early next year deepen MileagePlus engagement and could support higher spending on premium seats and ancillary revenue if execution is smooth.
This rollout depends on rapid hardware installation, consistent in flight performance and coordination with rising fuel costs and fare actions. Any reliability problems, cost overruns or underused premium capacity would feed directly into existing concerns about leverage, customer perception and the payoff from the broader fleet and cabin investment cycle at United Airlines Holdings.
United Airlines Holdings' current analyst narrative points to forecast revenues of US$74.3b and earnings of US$4.2b by 2029, based on revenue growth assumptions of 5.7% per year and an earnings increase of roughly US$0.7b from about US$3.5b today.
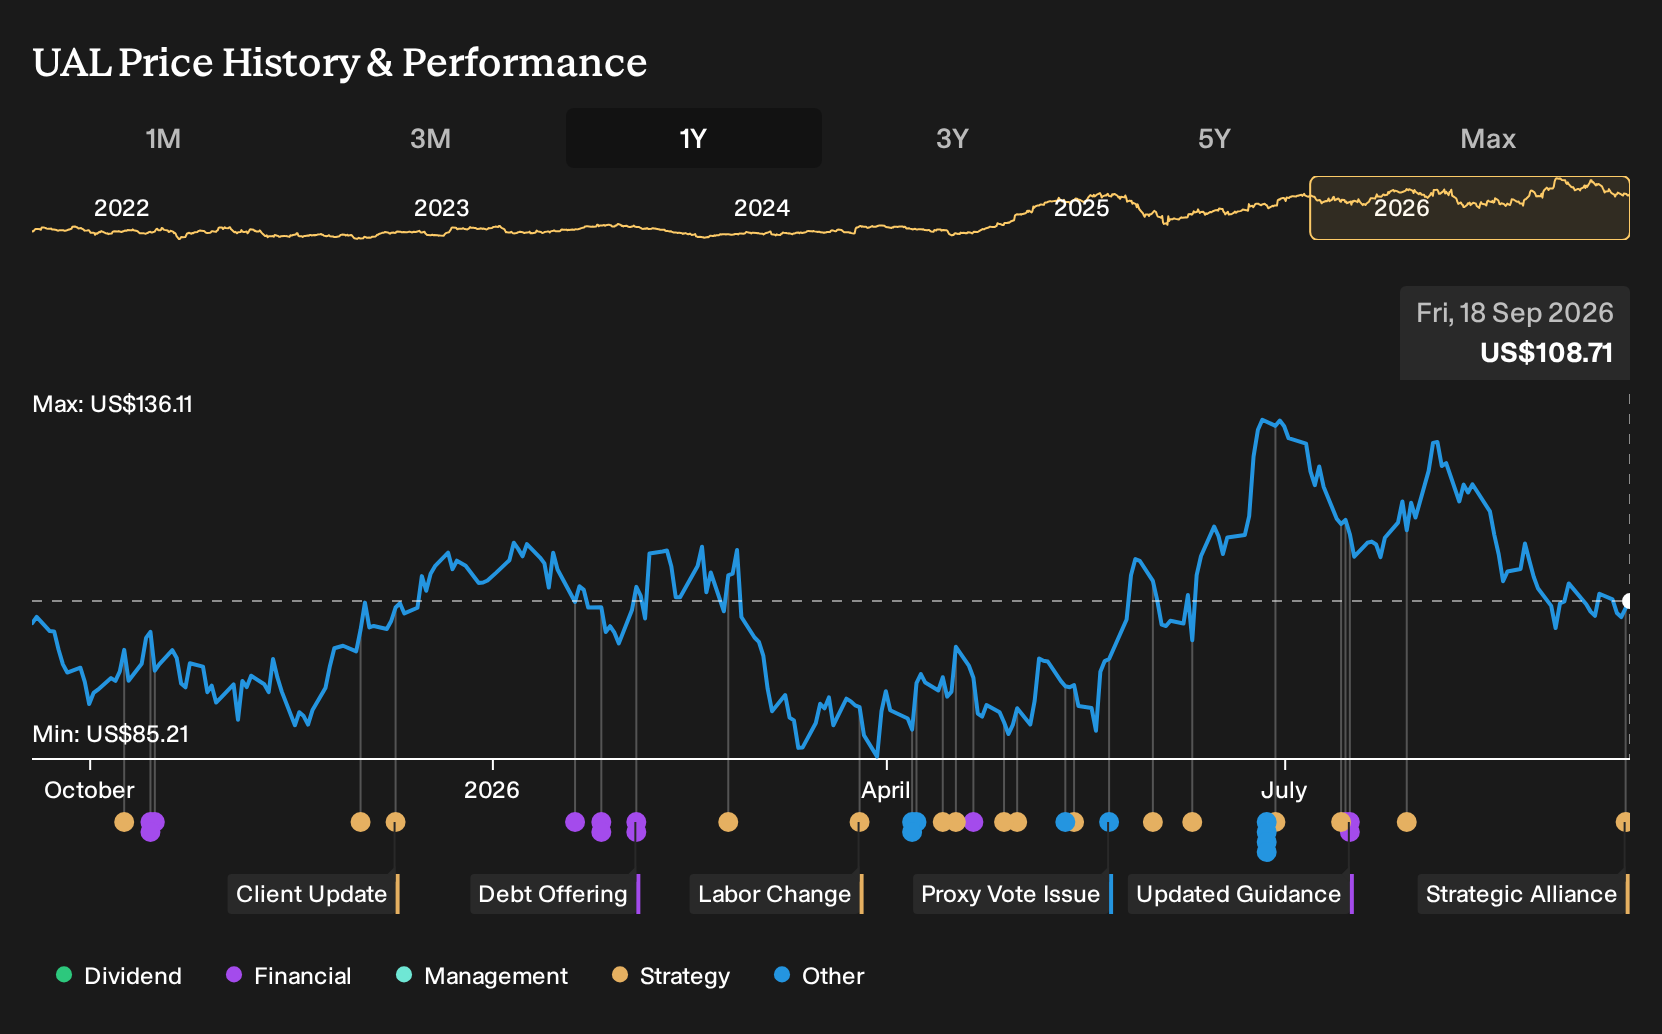
Discover how United Airlines Holdings' fair value indicates a 49% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
For a very different angle, focus on the bearish analysts who see United Airlines Holdings as far more constrained by future carbon costs than helped by new perks like live football. They were working off revenue forecasts of about US$68.5b and earnings near US$4.7b by 2029, which is well below consensus. Those views were set before this DISH and Starlink deal, so opinions may evolve as you weigh both narratives for yourself.
Explore 2 other United Airlines Holdings fair value estimates, including one that suggests it could be worth just $119.78.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Airlines Holdings research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Airlines Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Airlines Holdings' overall financial health at a glance.
Looking for more investment ideas beyond United Airlines Holdings?
If the United Airlines Holdings story has sharpened your thinking, broaden your opportunity set by scanning other businesses through the Simply Wall St Screener. Pick a few angles that match how you like to invest, then let the data surface stocks that fit your preferred mix of quality, risk and income.
- For investors who want lower volatility and sturdier financial profiles, start with a 30 resilient stocks with low risk scores that have historically kept their risk scores in check.
- If you prefer to get paid while you wait, review a curated set of income opportunities through the 6 dividend fortresses that may suit a yield focused approach.
- For those hunting beyond the obvious large caps, widen your search to a 16 high quality undiscovered gems that combine strong fundamentals with less crowded attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com