
Learn Why The Bull Case For Merchants Bancorp Stock Could Change Following Earnings Beat
- Merchants Bancorp reported a satisfactory Q2, with revenue up 1.7% year on year and earnings per share ahead of analyst expectations, despite net interest income coming in below forecasts.
- The bank’s focus on low risk, government backed lending across multi family mortgage banking, mortgage warehousing, and traditional banking appears to have supported stable performance in a mixed quarter.
- We will now look at how Merchants Bancorp’s earnings beat on EPS could influence the broader investment narrative around the bank.
Scan how Merchants Bancorp’s conservative lending focus compares with other banks and financials by checking our curated list of 30 resilient stocks with low risk scores for potential low risk opportunities.
What Is Merchants Bancorp's Investment Narrative?
To own Merchants Bancorp, you really need to buy into a simple idea. A relatively conservative, government backed lending model across multi family mortgage banking, mortgage warehousing, and traditional banking can justify steady use of capital if execution remains tight. The latest quarter, with a 1.7% revenue uptick and an EPS beat despite softer net interest income, supports the view that the engine is working, even when a single line item underwhelms.
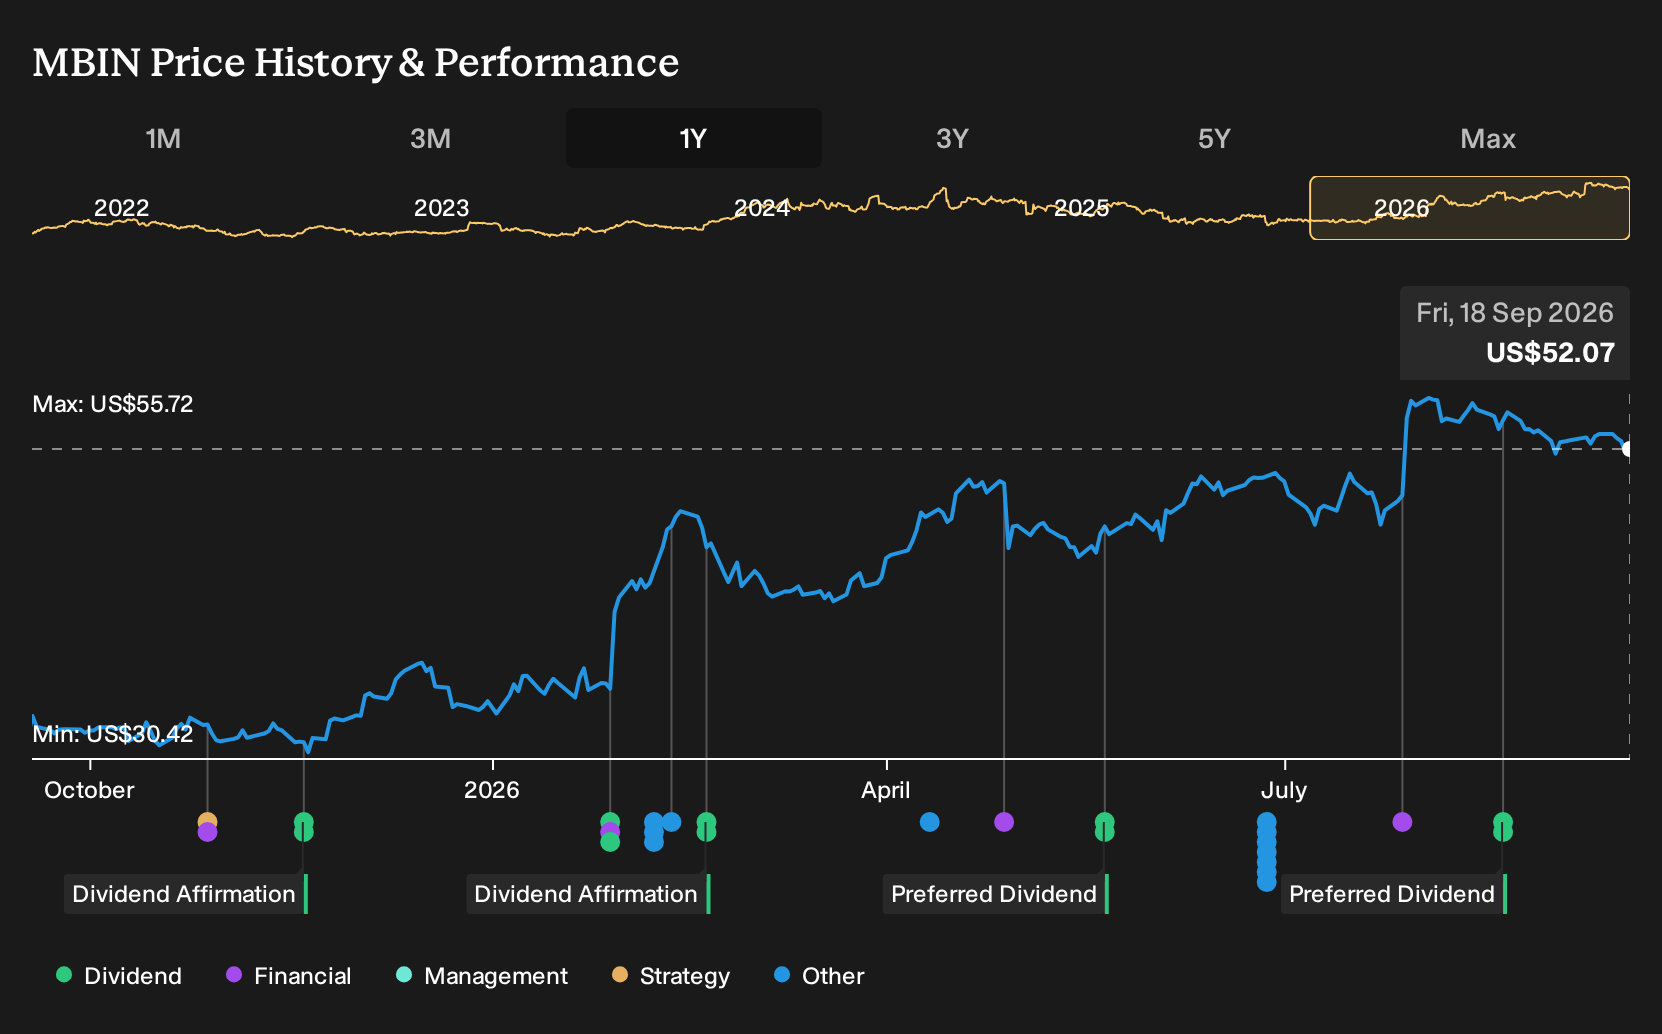
In the short term, the key swing factors are clear: demand for multi family and warehouse credit, pricing discipline on new loans, and the funding cost on deposits. MBIN’s P/E of 10.5x, below both industry and peer averages, plus high quality earnings, provides some cushion if sentiment cools after the recent 7.9% move since results. The Q2 print does not rewrite the story. It reinforces that the current playbook still holds.
Even so, there is one uncomfortable detail in Merchants Bancorp’s story that tends to get less attention than it should.
There's only one way to know the right time to buy, sell or hold Merchants Bancorp. Head to Simply Wall St's company report for the latest analysis of Merchants Bancorp's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Merchants Bancorp research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Merchants Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Merchants Bancorp's overall financial health at a glance.
Looking For More Merchants Bancorp Style Ideas?
If Merchants Bancorp's measured approach appeals to you, it can help to widen the lens and compare it with other stocks that share similar qualities, whether that is valuation, balance sheet strength, or income potential.
- If you want to focus on companies that combine quality with pricing that may still be attractive, take a look at 33 high quality undervalued stocks that filter for that mix of fundamentals and value.
- For investors who care most about resilience, check out our list of solid balance sheet and fundamentals (23 results) to see which businesses score well on financial strength and stability.
- If you enjoy finding opportunities before the crowd does, you may want to scan our 16 high quality undiscovered gems that highlight underfollowed stocks with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com