
Patrick Industries (PATK) Slides This Year, Is The Stock Trading At A Discount?
Patrick Industries (PATK) has drawn attention after recent trading left the stock down about 21% over the past month and roughly 38% year to date. This has sharpened investor focus on valuation and business fundamentals.
Recent trading pressure has extended earlier weakness, with Patrick Industries posting a 1-day share price decline of 1.73% and a 7-day share price return of down 6.39%. This has contributed to a year-to-date share price return of down 37.78%, while the 3-year total shareholder return of 43.63% and 5-year total shareholder return of 41.05% present a very different long-run picture of investor outcomes.
Pressure like this on Patrick Industries can prompt investors to reassess where they see better risk and reward. Compare it against a curated set of 33 high quality undervalued stocks.
After a slide that leaves Patrick Industries down sharply this year, the fork in the road is clear: lean into the weakness now, or wait and risk watching a valuation rerate without you.
Most Popular Narrative: 37% Undervalued
On the most followed view of Patrick Industries, a fair value of $109.80 sits well above the last close at $68.71, which puts the current slide in a very different light for anyone focused on long term cash generation.
Strategic investments in automation, advanced manufacturing processes, and full-solution models (for example, greater integration of technology and materials across business units) are expected to yield operational efficiencies and scale benefits, supporting gross margin improvement and higher earnings over time.
See why 2 investors see Patrick Industries as 37% undervalued.
Result: Fair Value of $109.80 (UNDERVALUED)
Still, the Patrick Industries narrative can break if RV and manufactured housing demand stays weak for longer or if acquisition integration drags on profitability.
Find out about the key risks to this Patrick Industries narrative.
Another View On Patrick Industries Valuation
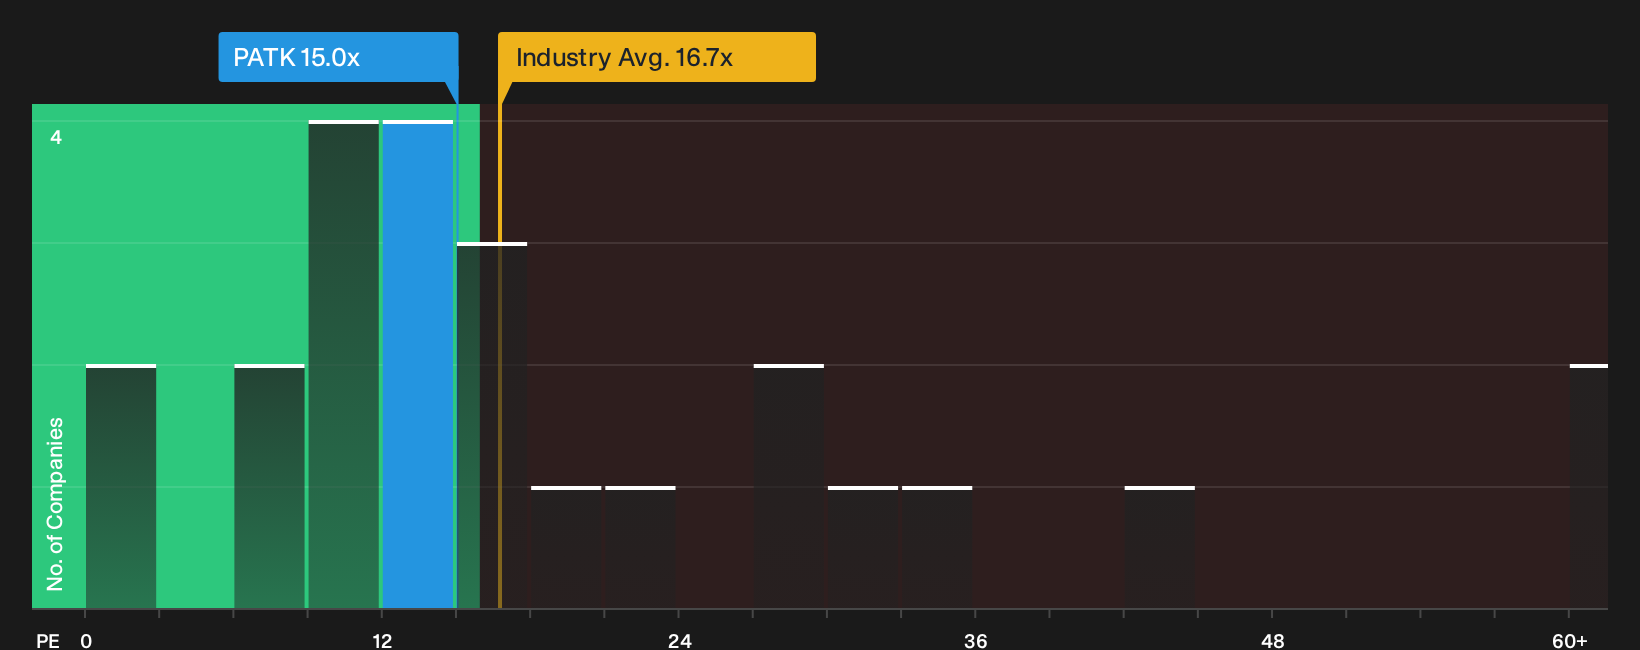
The narrative built around a $109.80 fair value for Patrick Industries sits alongside a different signal from simple earnings multiples. At a P/E of 15x, the stock trades above peer averages at 12.6x, yet only slightly below its own fair ratio of 15.5x, which suggests less obvious upside and more focus on execution risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Patrick Industries story today. If you feel the clock is ticking, pull up the numbers yourself and stress test both sides of the argument through the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Patrick Industries?
If Patrick Industries has sharpened your focus on pricing and fundamentals, do not stop here. Use the Simply Wall Street Screener to pressure test fresh opportunities.
- Target resilient cash generators by reviewing companies with strong balance sheets and fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispricing in quality businesses by scanning the 33 high quality undervalued stocks before others spot the same setup.
- Spot under-the-radar opportunities with solid metrics by checking the 16 high quality undiscovered gems while they are still off most investors' radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com