
Colon Health Launch Might Change The Case For Investing In BioGaia (OM:BIOG B)
- BioGaia launched BioGaia Colus in 2026, a clinically tested, FODMAP friendly colon health probiotic using proprietary L. reuteri BG-R59 in delayed release vegan capsules, starting in the UK with further markets to follow.
- The focus on a lower GI targeted, adult probiotic backed by randomized, double blind, placebo controlled trials adds depth to BioGaia’s adult gut health portfolio and supports its research driven product strategy.
- We will now examine how BioGaia's product led investment narrative could shift with the clinically supported launch of BioGaia Colus.
Scan how BioGaia is repositioning around clinically tested adult gut health, and then compare it with a curated 612 high quality undiscovered gems pursuing similar research-led niches.
BioGaia Investment Narrative Recap
To own BioGaia, you need to believe the business can keep shifting its center of gravity from pediatrics toward higher value, clinically supported adult health while keeping spending under control. The launch of BioGaia Colus fits that thesis because it leans into condition specific, study backed products that can justify premium positioning.
The short term swing factor is whether recent OpEx heavy efforts in adult health, direct channels, and key markets turn into healthier EBIT after a period of margin pressure. The main risk is that these launches, including Colus, do not scale fast enough, which could prolong weaker margins and limit cash for further R&D.
The BioGaia Colus launch is the clearest recent marker of where management wants adult health to go. It uses a proprietary L. reuteri strain, delayed release vegan capsules and a FODMAP friendly profile, and is backed by two randomized, double blind, placebo controlled trials. That kind of evidence led positioning can support pricing power if execution in priority markets is tight.
Rollout begins in the UK and then expands to selected markets, so the operational test is straightforward. Can BioGaia plug this product into existing direct and retail distribution in a way that lifts adult health revenue without another leg up in marketing intensity? If uptake is slow, the risk is more OpEx pressure with limited near term relief to margins and cash flow.
BioGaia's current analyst storyline points to revenues of SEK 2.2b and earnings of SEK 595.2m by 2029, based on assumed yearly top line growth of 11.6% and an earnings increase of SEK 248m from SEK 347.2m today.
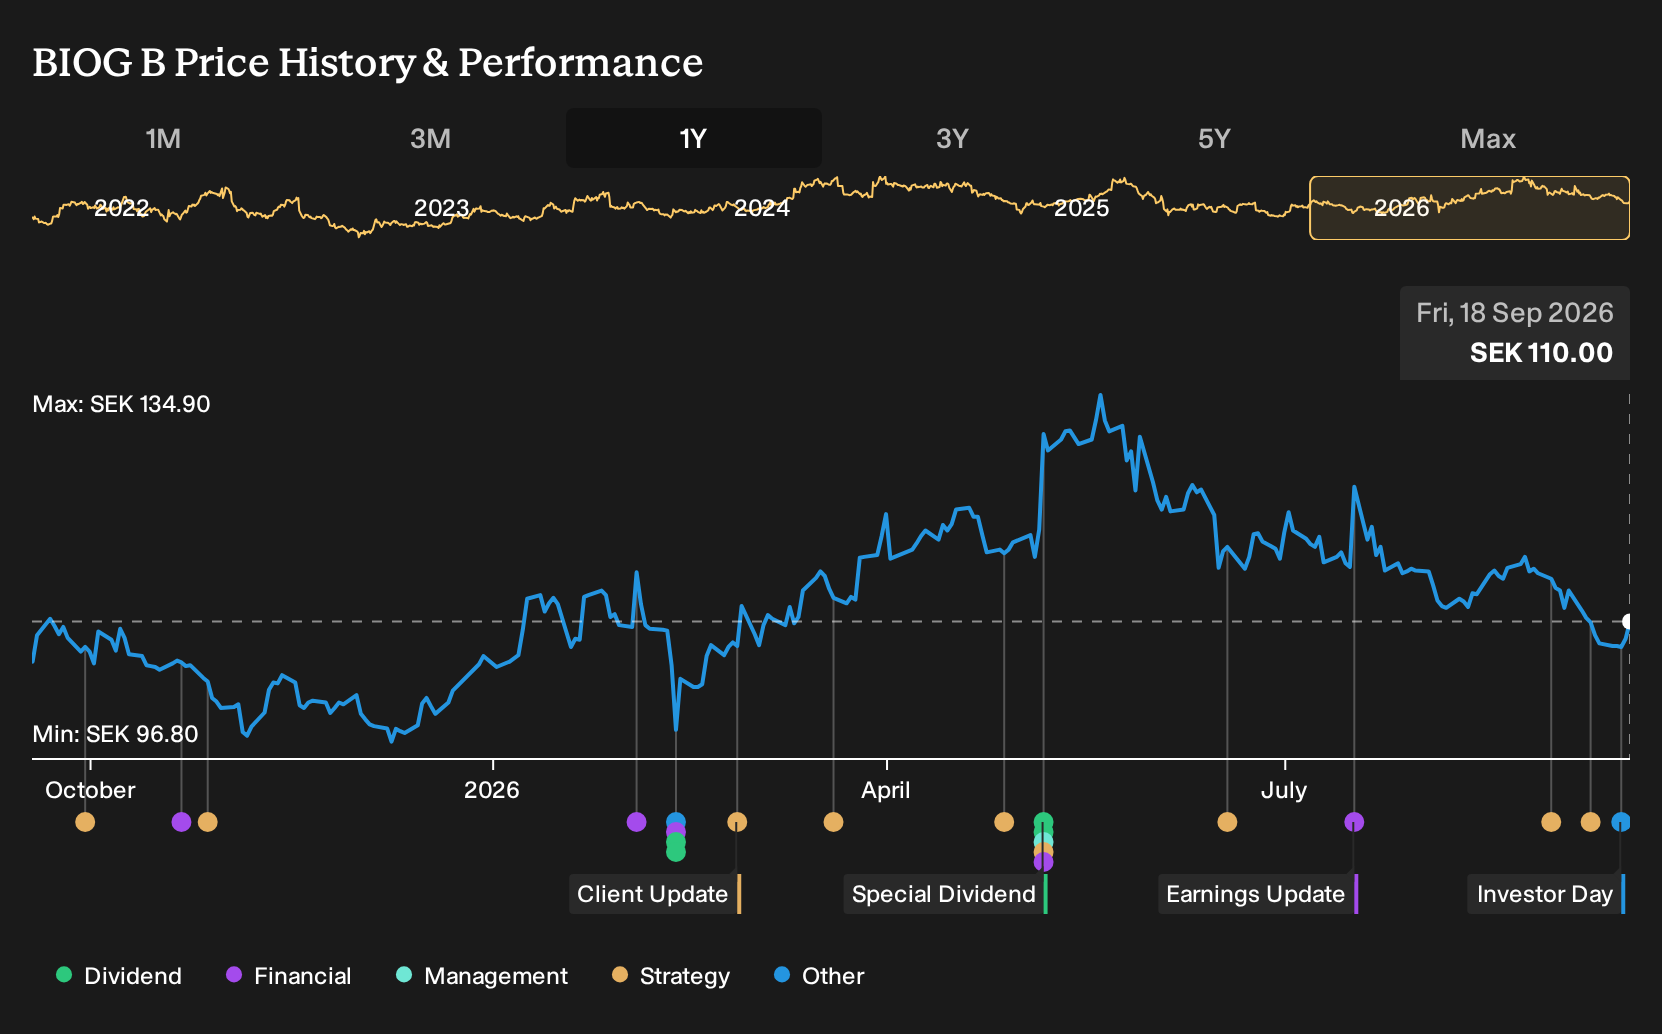
Uncover why BioGaia's fair value indicates a 39% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community span roughly SEK 152.5 to SEK 167.1 per share, which already shows how differently retail investors can price the same BioGaia story. When you also consider the recent EBIT drop, heavier OpEx and the Colus launch as a fresh catalyst, it becomes clear that opinions can diverge sharply. You should treat these as reference points and explore several alternative viewpoints before forming your own stance.
Explore 2 other BioGaia fair value estimates, including one that suggests it could be worth just SEK152.50!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BioGaia research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BioGaia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioGaia's overall financial health at a glance.
Looking for more BioGaia style investment ideas?
If the BioGaia story has sharpened your thinking around quality, risk and evidence based growth, it can help to line it up against a wider watchlist and see what else fits your playbook.
- For investors who care most about quality at a reasonable entry point, compare BioGaia with a 179 high quality undervalued stocks that blend solid fundamentals with discounted prices.
- If capital preservation is higher on your list than potential upside, weigh BioGaia against a 227 resilient stocks with low risk scores that screen well on balance sheet strength and volatility.
- When you want to broaden beyond familiar tickers, set BioGaia alongside a 612 high quality undiscovered gems that share similar financial traits yet attract far less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com