
Rubicon Research And 2 More Indian Insider Led Growth Stocks
Higher interest rates from the Federal Reserve are making cheap money harder to find and punishing weaker balance sheets. Indian growth-focused companies where promoters own a large stake can look more interesting when financing costs bite, because insiders have more on the line and often think in years, not quarters. This article walks through three such fast growing, high insider ownership Indian stocks from our screener and explains why they may be attracting attention now.
The three examples highlighted below are only a small sample, and the full screen surfaced 105 more companies where insiders hold substantial stakes and the growth story is just as compelling. To go broader and identify potential high conviction ideas that fit your own criteria, analyze the Fast Growing Stocks With High Insider Ownership screener.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research is a specialty pharmaceutical business that uses proprietary RubiReten and RubiSRL platforms to develop differentiated therapies across multiple high-growth treatment areas.
Operations: Rubicon Research generates about ₹19.4b in revenue from pharmaceutical products, including generics, specialty formulations, APIs, and related services.
Market Cap: ₹289.9b
Rubicon Research fits this screener because its proprietary drug delivery platforms aim to turn focused R&D into a wider, higher value product line that can support faster growth over time.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
What really matters now is how one pressure on future pricing power and margins plays out against those ambitious growth expectations.
If you are interested in the trade off between pricing pressure and growth ambitions, read the full narrative for Rubicon Research to see how the thesis could be accelerating.

Atlanta Electricals (NSEI:ATLANTAELE)
Overview: Atlanta Electricals manufactures power and special duty transformers for transmission, solar, construction, and infrastructure clients across India.
Operations: The business generates about ₹20,027 million in India from manufacturing power and special duty transformers, supported by after sales services.
Market Cap: ₹128.1b
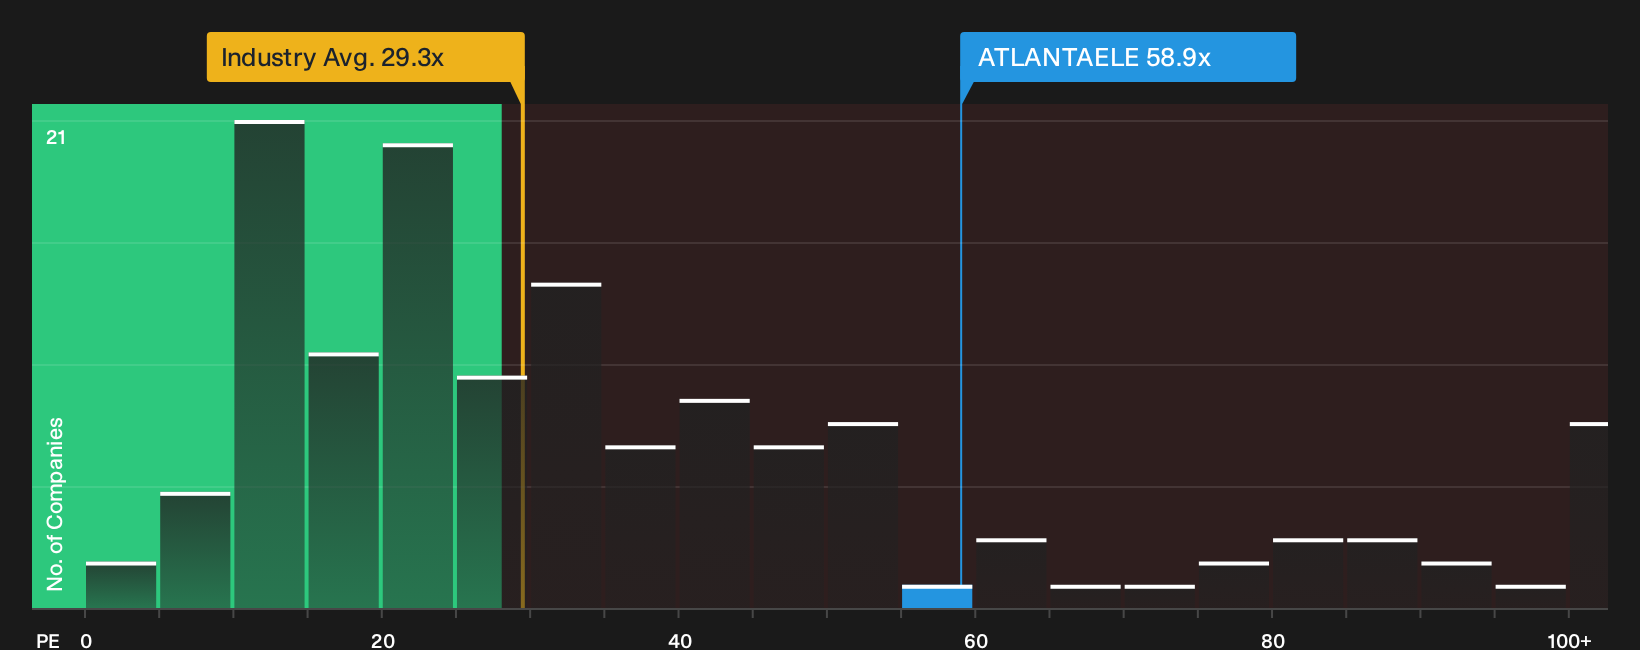
Atlanta Electricals links directly to the Fast Growing Stocks With High Insider Ownership theme, as its transformers are used in grid, solar, and infrastructure buildouts. The company is associated with revenue forecasts of 24.7% a year and earnings forecasts of 31.27%. The combination of a 23.4% ROE and a 58.9x P/E implies that investors may be closely watching whether current conditions continue to support this valuation.
That valuation tension is exactly why the analysis report for Atlanta Electricals could be useful for seeing how growth expectations and earnings quality compare with the current multiple.
Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects delivers EPC solutions for extra high voltage transmission and distribution lines, substations, and poles tied to electrification projects.
Operations: The business generates about ₹27,508 million in revenue from power transmission and power distribution EPC contracts and related infrastructure work.
Market Cap: ₹19.9b
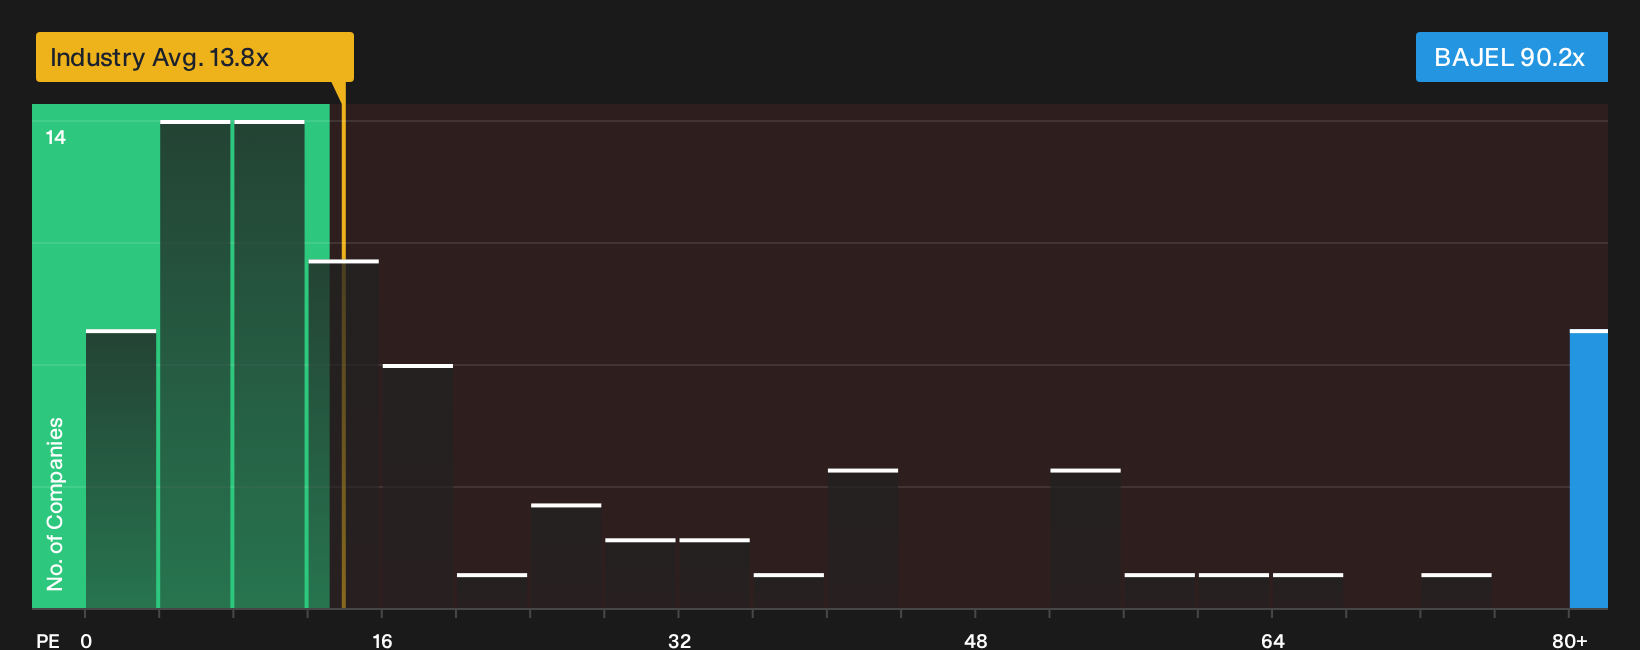
Bajel Projects is linked to the Fast Growing Stocks With High Insider Ownership theme, with forecast revenue growth of 27% and earnings expected to advance 57.67% a year. The stock currently trades on a 90.2x P/E, which raises the question of how resilient that growth story may be if any unseen pressure on its future project economics emerges.
If that premium P/E depends on project economics remaining intact, the 2 key rewards and 1 important warning sign could indicate whether Bajel Projects’ growth story is accelerating or stalling next
Seeking Alternatives Before Momentum Builds
Fresh opportunities often emerge quietly, then momentum builds and the most attractive entry points can be taken quickly. Review these ideas while they are still timely and consider them carefully.
- Target resilient cash generators by running the list of solid balance sheet and fundamentals (197 results) to identify businesses that may hold up when weaker peers start declining.
- Explore potential dividend payers using the 156 dividend fortresses to track companies with established payouts.
- Search for under-the-radar growth with the 612 high quality undiscovered gems to find quality operators before higher trading volumes change their profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com