
Buyback Plan Could Change The Case For Par Pacific Holdings Stock (PARR)
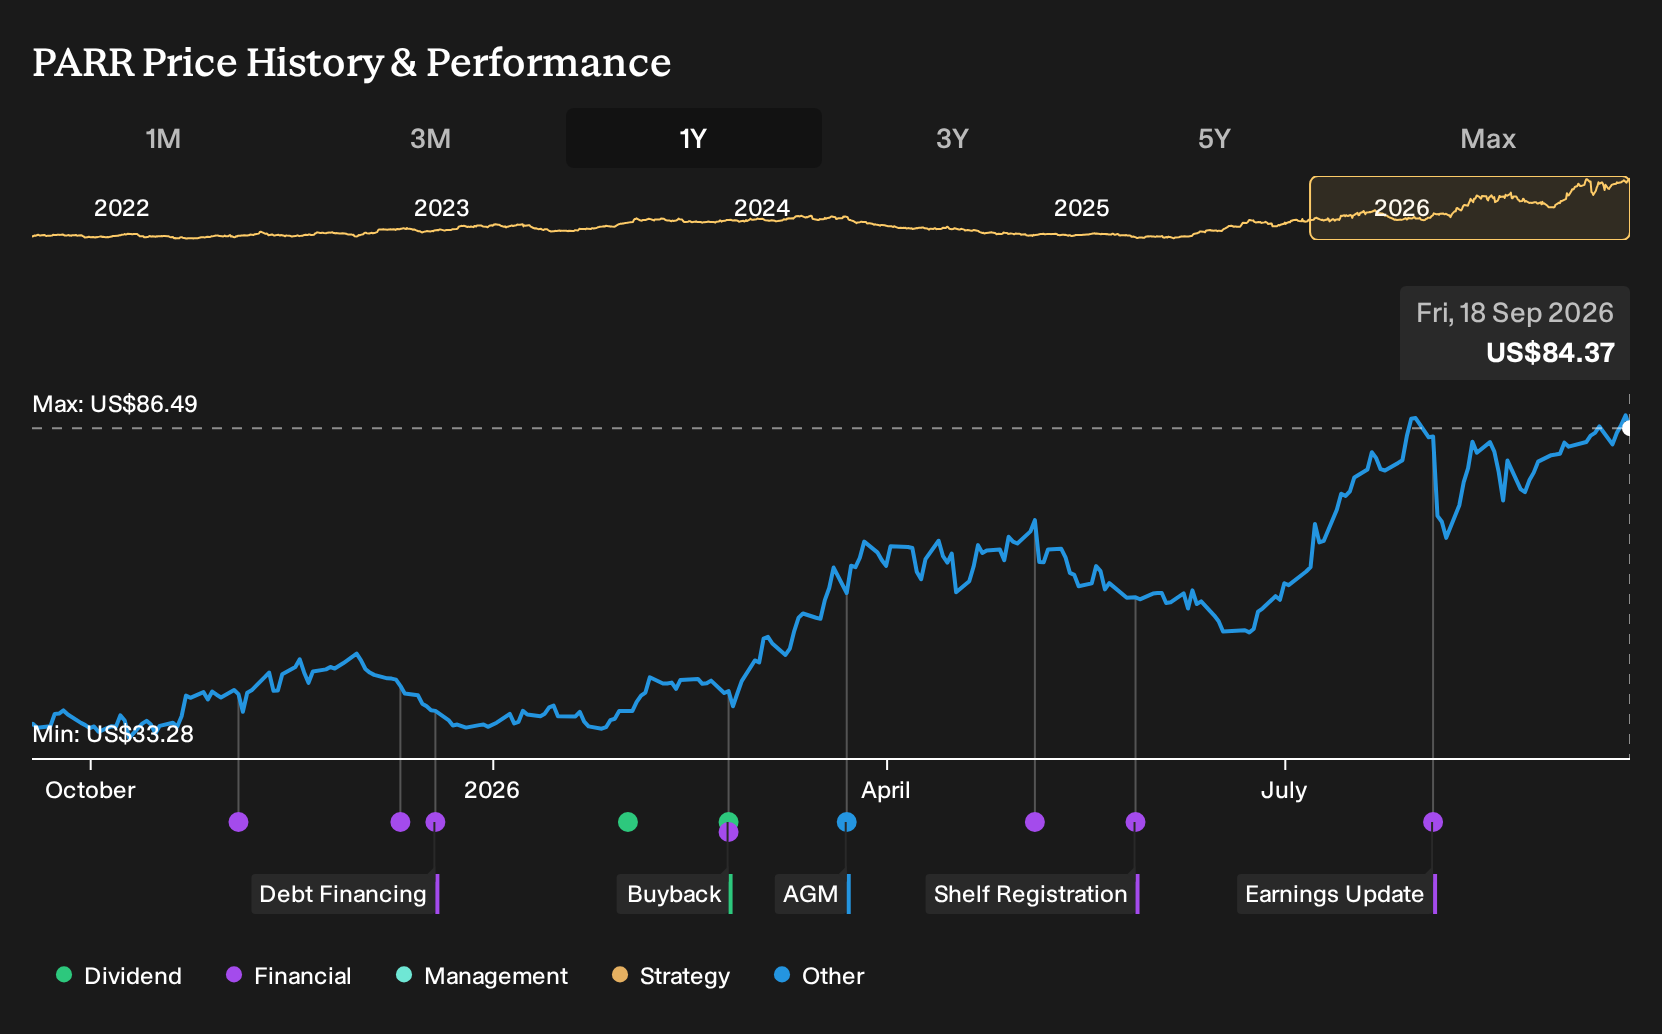
- Par Pacific Holdings recently drew attention after analysts reported a 19.5% uplift in the current year earnings consensus over 60 days, alongside a US$250,000,000 share repurchase authorization, set against a P/E ratio that sits below the wider oil and gas industry average.
- This combination of higher earnings expectations and a sizeable buyback points to management prioritising capital returns and operational profitability. This, in turn, can reshape how investors weigh Par Pacific Holdings against peers with similar refining exposure.
- We will now see how Par Pacific Holdings' investment narrative may be influenced by the upgraded earnings outlook flagged in recent coverage.
Par Pacific Holdings Investment Narrative Recap
To own Par Pacific Holdings, you need to be comfortable with a refining-heavy business that is tied to regional fuel demand in Hawaii and the Western U.S., and with earnings that analysts currently expect to decline over the next few years. The near-term swing factor is how reliably these refineries run, especially older sites that can face outages and higher upkeep.
The biggest risk right now sits in that same operational bucket. Concentrated exposure, aging assets and tightening climate rules can all pressure throughput and costs. The recent earnings upgrade does not remove those issues. It mainly reframes how you weigh near-term profitability against these structural pressures.
The US$250,000,000 share repurchase authorization is the clearest recent announcement tied to this story. It intersects directly with the P/E that remains well below the broader oil and gas industry average and with a company that reports high-quality earnings and a 42% return on equity.
For you, the buyback matters only if Par Pacific Holdings can keep refineries running efficiently while managing leverage and environmental compliance. Execution on renewables projects such as the planned SAF initiative, and on integration work in markets like Montana, will influence how much free cash flow is actually available to retire shares over time.
What The Analyst Case Implies For Par Pacific Holdings
Par Pacific Holdings' narrative projects US$6.7b revenue and US$455.7m earnings by 2029. This assumes revenue declines at 7.9% per year and points to an earnings decrease of US$401.2m from US$856.9m today.
Uncover why Par Pacific Holdings' fair value is in line with its current price.
Exploring Other Perspectives
One brighter twist in the alternate view is how strongly some analysts lean into Par Pacific Holdings' SAF project and refinery optimizations. Before this buyback news, the most optimistic group was pencilling in about US$7.2b of revenue and US$570.1m of earnings by 2029. That is a meaningfully higher bar than consensus, and you can use that gap to test which scenario you find more convincing as new information emerges.
Explore 3 other Par Pacific Holdings fair value estimates, including one that suggests as much as 416% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Par Pacific Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Par Pacific Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Par Pacific Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Par Pacific Holdings?
Once you have a view on Par Pacific Holdings, it can help to cross-check that thesis against a wider set of companies with similar qualities, whether you care most about value, resilience or balance sheet strength.
- If you want potential mispricing on your radar, scan our hand picked 33 high quality undervalued stocks and see which businesses combine compressed P/E ratios with solid fundamentals.
- For investors who care most about durability, filter for companies with steadier risk profiles using the 30 resilient stocks with low risk scores and compare how their track records line up against your current watchlist.
- If capital strength is your starting point, focus on cleaner finances and robust fundamentals through the list of solid balance sheet and fundamentals (23 results) to spot candidates that may weather tougher conditions more comfortably.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com