
Will MGH Research Tie Up Change Aptar Stock Narrative
- AptarGroup announced a research collaboration with Massachusetts General Hospital, led by Alice Stanton, PhD, to build a translational platform for nose-to-brain drug delivery using in vitro, in vivo and computational tools that integrate the company’s nasal systems such as Cerespray and Neurospray.
- The work aims to create New Approach Methodologies consistent with FDA support. These methodologies could help pharmaceutical partners screen CNS candidates more efficiently, refine formulations and device designs, and potentially lower development costs across future neurological programs.
- We will now look at how AptarGroup's nose-to-brain research platform with MGH could reshape the broader investment narrative.
AptarGroup Investment Narrative Recap
To hold AptarGroup, you need to believe its higher value pharma platforms can offset slower areas like prestige beauty, nasal decongestants and Narcan related orders, while still absorbing heavier legal and R&D spend. The MGH nose to brain collaboration supports that thesis at a science level, but does not change near term revenue or margin drivers on its own.
In the short term, the key swing factor remains how quickly pharma demand normalizes where funding or inventory issues have weighed on orders. The biggest operational risk still sits in sustained legal costs and weaker categories that could keep net margins under pressure even if new CNS tools gain customer traction.
The recent leadership change in finance matters for these catalysts. AptarGroup has seen its Chief Accounting Officer resign, with former CAO Daniel Ackerman stepping back into the role on an interim basis while also serving as Senior Vice President, Finance for Aptar Pharma. That keeps an experienced insider over financial reporting during a heavy investment phase.
For you as a shareholder, execution discipline around the MGH partnership and broader CNS platforms will depend partly on consistent financial controls, especially while legal expenses, capex, and R&D remain elevated. Stable oversight from someone who already understands Aptar Pharma’s economics can help reduce operational noise around earnings, which becomes important when the stock trades on a premium P/E and carries meaningful debt.
AptarGroup's narrative projects US$4.7b revenue and US$473.9m earnings by 2029. This implies 5.8% yearly revenue growth and an earnings increase of about US$111.4m from US$362.5m today.
Uncover why AptarGroup's fair value indicates a 33% potential upside to its current price, which could narrow quickly.
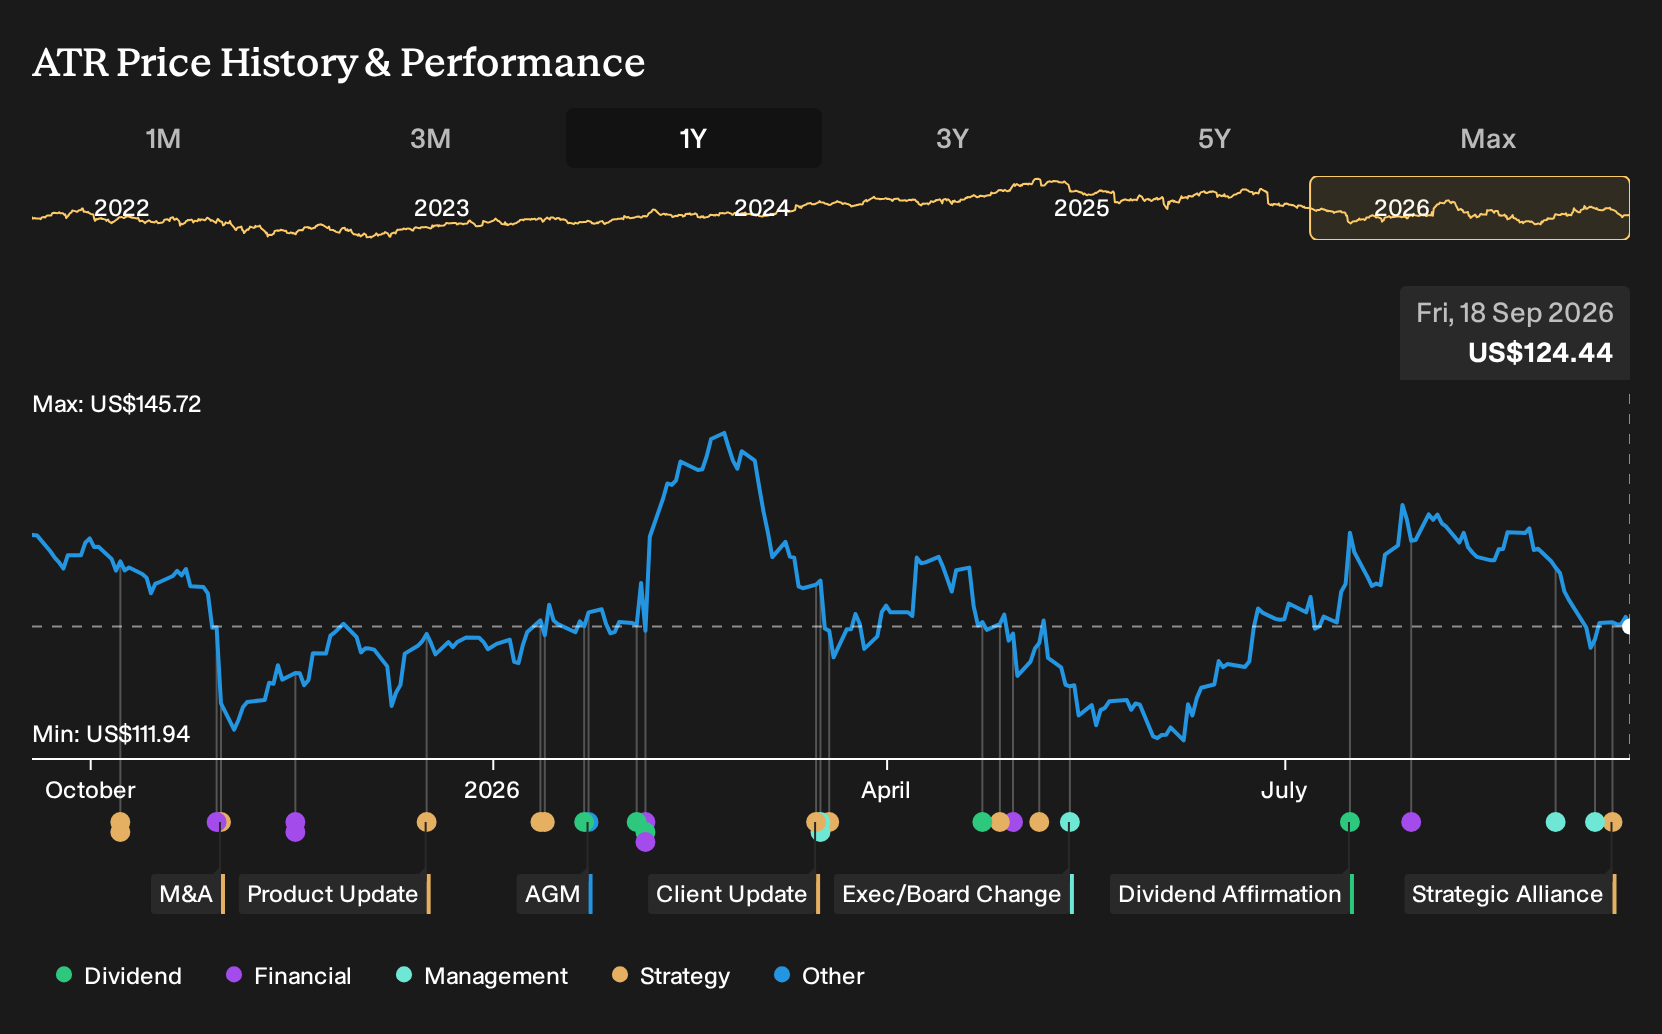
Exploring Other Perspectives
Some analysts focus less on AptarGroup’s nose to brain upside and more on the risk that core packaging demand softens over time. The lowest forecasts were already penciling in about US$4.6b revenue and US$460.6m earnings by 2029, before this MGH news; their more cautious story could shift if the platform gains traction.
Explore 3 other AptarGroup fair value estimates, including one that suggests it could be worth just $155.00!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AptarGroup research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AptarGroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AptarGroup's overall financial health at a glance.
Looking For More Investment Ideas Beyond AptarGroup?
If AptarGroup's nose to brain work with MGH has you thinking about where else specialized platforms might be taking shape, it can help to widen the lens and scan the wider market with a structured tool.
- For investors who care most about quality and valuation discipline, focus on companies that pair strong fundamentals with appealing pricing by reviewing 33 high quality undervalued stocks.
- If capital preservation and a smoother ride matter more than headlines, focus on businesses that screen well on stability metrics and financial resilience through the 30 resilient stocks with low risk scores.
- When you want to get ahead of the crowd, look at smaller companies with solid financial underpinnings that are not widely followed yet by checking out 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com