
Learn Why The Bull Case For Hudbay Minerals Stock Could Change Following Copper Supply Crunch
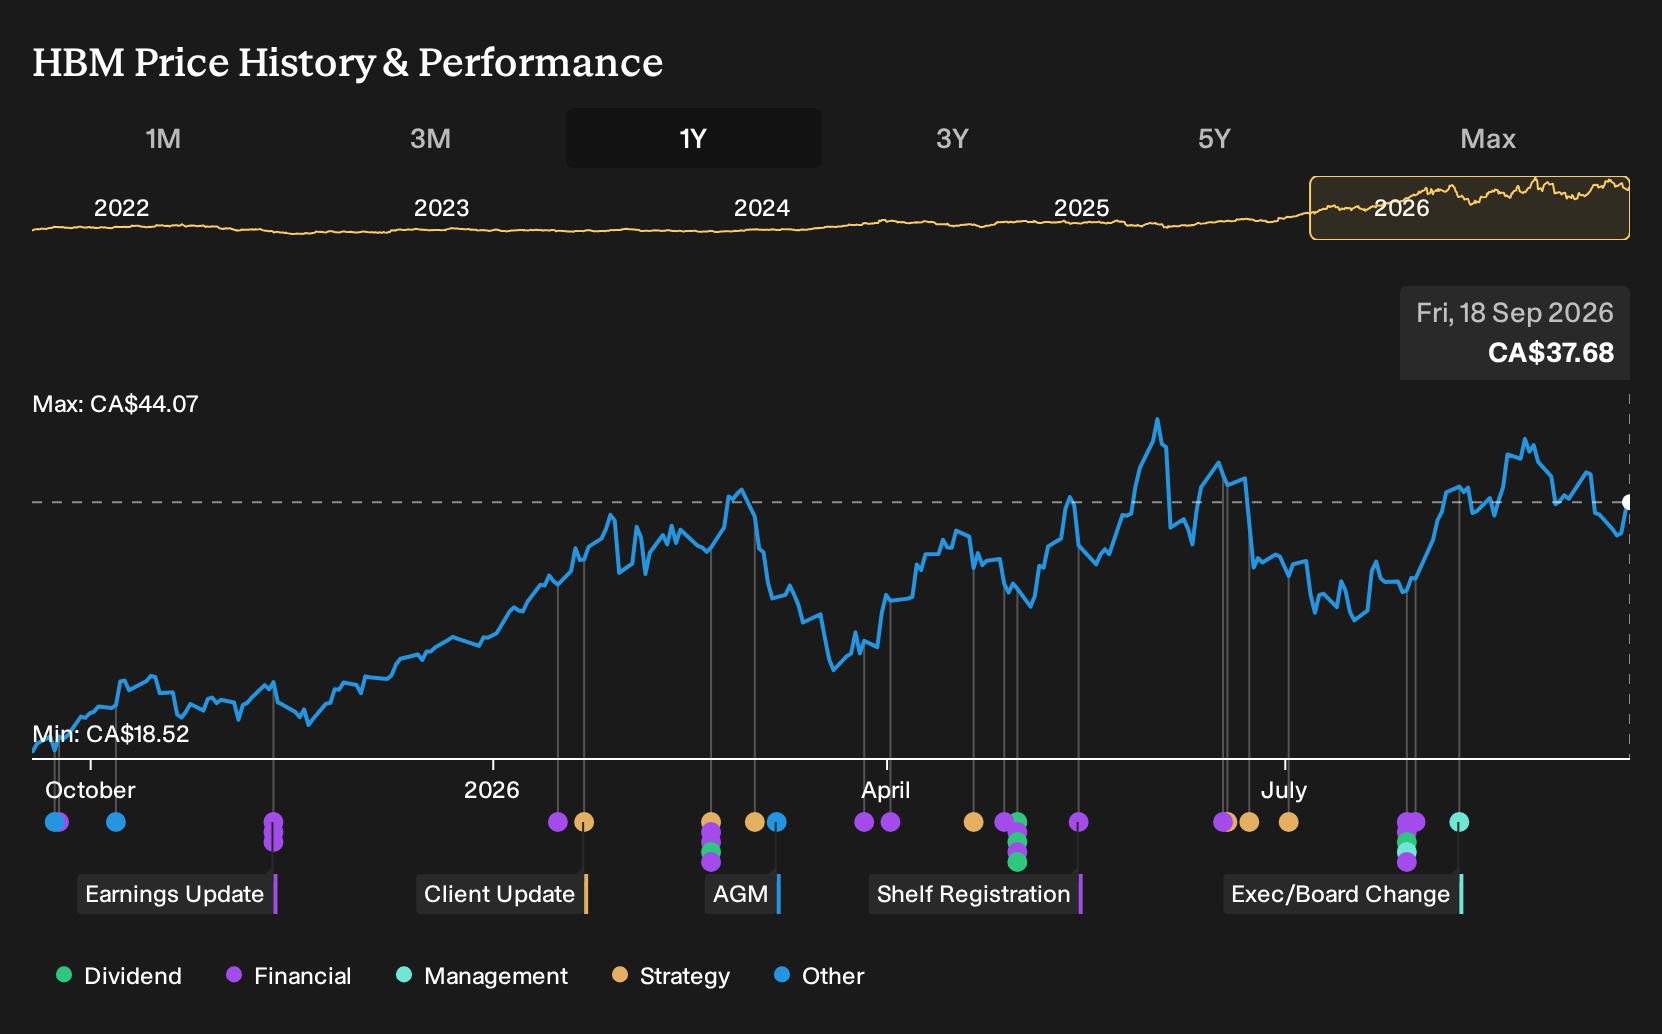
- Hudbay Minerals has attracted attention as copper markets tightened after Chile reported its weakest second quarter output in 19 years and global mine supply was projected to remain flat or decline, while analysts now forecast quarterly EPS of $0.36 compared with a very low base a year earlier.
- The combination of record copper pricing on the London Metal Exchange and expectations for a very large earnings jump highlights how sensitive Hudbay Minerals’ profitability is to supply driven shifts in the copper market and to the operational leverage embedded in its existing mines and growth projects.
- This article examines how Hudbay Minerals’ investment narrative is shaped by tight copper supply and expectations for a sharp earnings rebound.
Scan how other copper exposed miners are positioned for this supply squeeze and earnings reset by checking the hand picked 16 top copper producer stocks alongside Hudbay Minerals.
Hudbay Minerals Investment Narrative Recap
To own Hudbay Minerals, you need to believe the copper focused portfolio can turn tight supply into durable cash generation while managing big project risk. The sharp move in London Metal Exchange copper and the projected EPS of $0.36 focus attention on how efficiently existing mines run and how cleanly growth projects ramp from here.
The key near term catalyst is continued reliable production from British Columbia, Manitoba, and Peru, while Copper World advances on time and on budget. The biggest risk is still execution and cost inflation on those large, concentrated projects. Recent copper price strength does not remove permitting, cost overrun, or disruption risks.
The most relevant recent data point is the EPS projection of $0.36 for the coming quarter from a very low base a year ago. That expected change, alongside the all time high copper price, puts a spotlight on how Hudbay Minerals converts price into earnings, especially after a year with a large one off gain in its reported results.
For you, the question is whether that potential earnings reset is mainly price driven or also reflects underlying improvements in operations and costs. If deliveries stay on track, the Copper World joint venture with Mitsubishi and the existing copper footprint could act as meaningful earnings drivers, while any production hiccups or inflation in capital spending would quickly dilute that benefit.
Hudbay Minerals' current analyst narrative points to revenues of $3.4 billion and earnings of $813.1 million by 2029, based on forecasts that assume 11.3% yearly revenue growth and an earnings increase of about $134.9 million from $678.2 million today.
Uncover why Hudbay Minerals' fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Hudbay Minerals focuses on Copper World risk. The lowest analysts were working off much softer long term numbers, with revenue assumptions closer to $3.0b and earnings near $448.8 million by 2029. You can treat those bearish forecasts as a stress test and compare them with your own read of this copper shock.
Explore 4 other Hudbay Minerals fair value estimates, including one that suggests there could be as much as 82% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Hudbay Minerals research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hudbay Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hudbay Minerals' overall financial health at a glance.
Looking for more investment ideas beyond Hudbay Minerals?
Once you have a handle on Hudbay Minerals, it can help to widen the lens and compare it with other opportunities filtered by the type of profile you want in your portfolio.
- If you want mispriced quality at the top of your watchlist, start with a curated set of companies screened as 4 high quality undervalued stocks. These pair stronger fundamentals with appealing pricing.
- For investors who care most about resilience, consider companies identified as 8 resilient stocks with low risk scores, where business stability and lower risk scores take priority over headline excitement.
- When you are hunting for lesser known stories with solid underpinnings, scan the 9 high quality undiscovered gems. These highlight businesses with quality metrics but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com