
Did Ammonia Import Deal Just Shift Covestro (DB:1COV) Stock Narrative?
- Covestro, Fertiglobe and MB Energy signed a Memorandum of Understanding in September 2026 to assess collaboration on an ammonia import terminal in Hamburg and related supply logistics across Germany and Europe, including potential equity investment, offtake and transport infrastructure.
- The agreement positions Covestro to assess more secure and diversified access to ammonia feedstock and hydrogen supply. This directly links to production reliability, cost visibility and compliance with frameworks such as CBAM and low carbon hydrogen rules in its core European operations.
- We will now assess how Covestro's investment narrative could shift as it evaluates long term ammonia offtake through the planned Hamburg terminal.
Scan how Covestro’s ammonia move fits into a broader shift in industrial supply chains by weighing it against a curated list of solid balance sheet and fundamentals (197 results).
Covestro Investment Narrative Recap
To own Covestro, you need to believe the polymers business can turn modest revenue growth into healthier earnings despite a tough chemicals cycle. The Hamburg ammonia MoU sits in that story as an infrastructure option rather than a core earnings driver. It could help with feedstock visibility but does not change near term demand in construction, furniture or electronics.
The main near term swing factor is still whether pricing pressure and industry oversupply ease enough for margins to stabilise while the Dormagen asset ramps back. The biggest risk remains a mix of weak end markets, high capex, negative free cash flow and stretched net debt that restricts room for error.
With no fresh company announcements tied directly to this Hamburg project, the most relevant reference point remains Covestro’s earlier push into higher value coatings and adhesives through Pontacol and the HDI derivative assets. Those moves frame how management is trying to add more specialised earnings streams on top of bulk materials exposure.
Read the MoU through that same lens. Feedstock optionality for ammonia and hydrogen affects how reliably Covestro can run plants and plan costs, while the coatings and aliphatics projects shape where any volume growth actually lands in the portfolio. Execution, integration progress and balance sheet discipline still sit at the centre of the equity story.
What The Consensus Numbers Assume For Covestro
Covestro's analyst narrative points to €14.4b in revenue and €285.8m in earnings by 2029. This implies 3.6% yearly revenue growth and an earnings swing of about €930m from a loss of €644.0m today to the forecast profit.
Uncover how Covestro's fair value indicates a 3% potential upside to its current price that could narrow quickly.
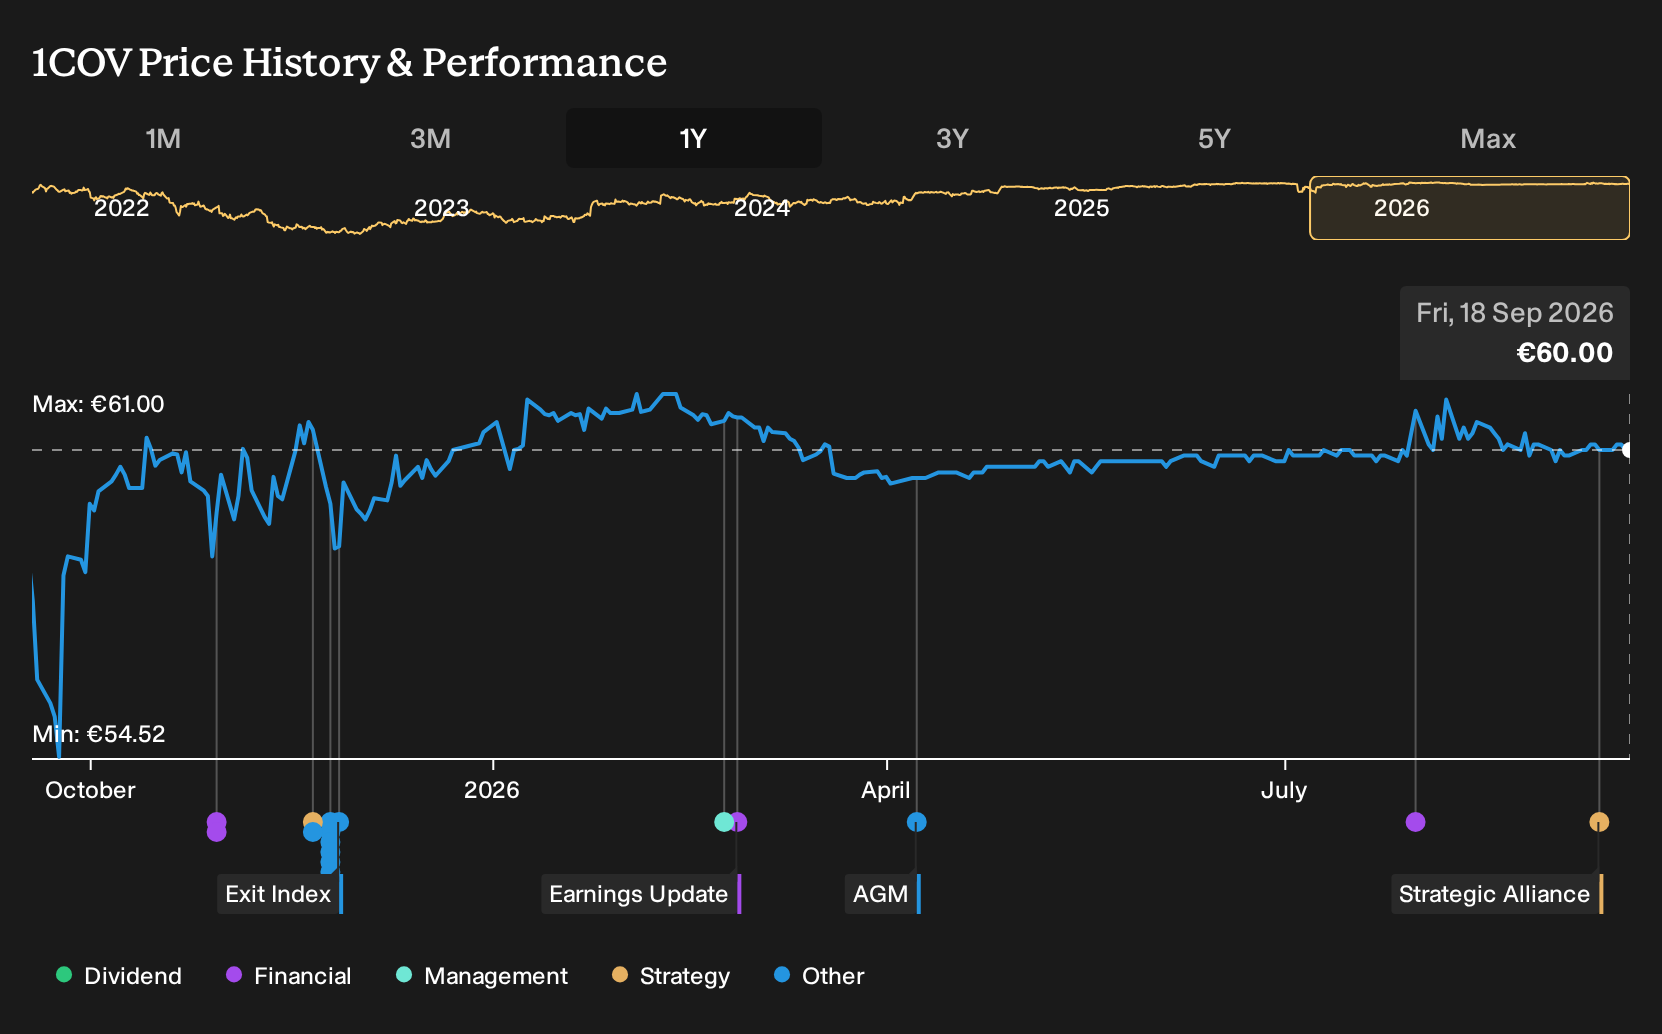
Exploring Other Perspectives
The Simply Wall St Community currently shows three Covestro fair value views, clustered between €62 and about €83 per share, so private investors already span a wide discount and premium. When you set that against risks such as persistent oversupply, Dormagen disruption and higher net debt, it serves as a reminder that opinions differ sharply. Explore those viewpoints before leaning on any single narrative.
Explore 2 other Covestro fair value estimates, including one that suggests it could be worth just €62.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Covestro research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Covestro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Covestro's overall financial health at a glance.
Looking for more Covestro-sized investment ideas?
If the Covestro story has you thinking about portfolio balance, use this moment to widen the lens and compare it with other companies that share some of the qualities you value most.
- For investors who want stability to do the heavy lifting, a 227 resilient stocks with low risk scores can help surface businesses where balance sheet strength and risk scores are front and center.
- If you are hunting for value with quality filters baked in, a curated 179 high quality undervalued stocks can point you toward companies that combine solid fundamentals with pricing that still looks reasonable.
- Those looking for income resilience can scan a 155 dividend fortresses to see which high yield payers also show staying power in their payout profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com