
Cleveland Cliffs (CLF) Stock May Be Undervalued Against Its Sales Base
Cleveland-Cliffs has carried investors through a mixed journey, with periods of gains punctuated by longer stretches of weaker performance. This puts fresh focus on what buyers today are paying for its sales. With the share price around US$12.50 at the last close, the key question is how that market value lines up against the revenue the business is generating.
- Over the past 5 years, the stock has delivered a return of about 39% in declines, which makes the current pricing of its sales a crucial question for anyone still holding or thinking about entering now.
- The group’s economics hinge heavily on how efficiently it converts steel and iron ore demand into revenue and cash. This can influence how much investors are prepared to pay for each dollar of sales in a cyclical industry.
- There is a second opinion on Cleveland-Cliffs worth weighing. See what analysts think Cleveland-Cliffs's shares could be worth.
The issue now is whether Cleveland-Cliffs’ current share price is adequately supported by its sales when judged against the Fair Ratio benchmark.
If you want more context around where Cleveland-Cliffs sits on the value-for-sales spectrum, a focused stock screen built around 33 high quality undervalued stocks is a useful next step in your research.
Is Cleveland-Cliffs Still Cheap on Sales?
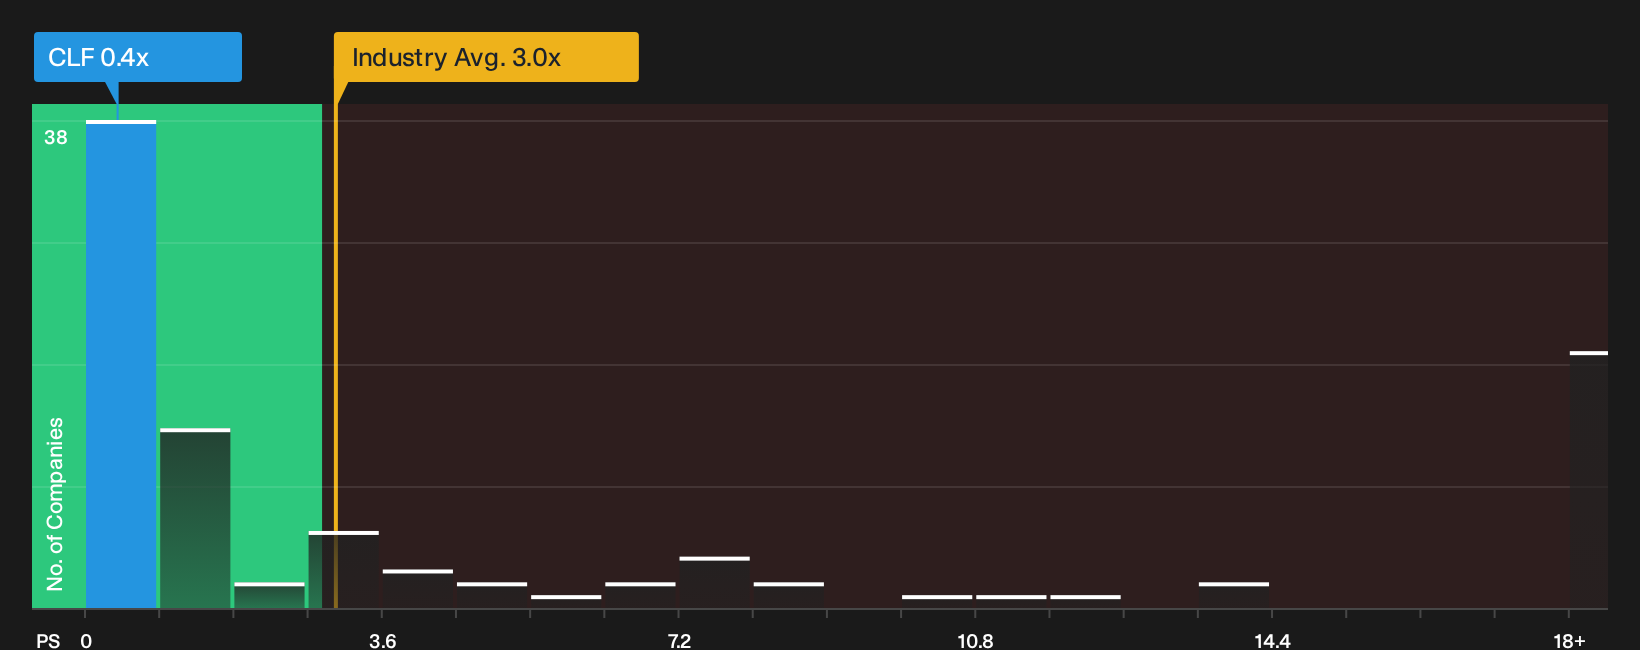
P/S fits Cleveland-Cliffs because investors tend to focus on how much they are paying for each dollar of revenue in a cyclical, commodity-style business where earnings can swing sharply. On this measure, the stock trades on a P/S of about 0.4x, while the broader Metals and Mining industry sits closer to 3.0x and the peer group average is around 1.6x.
The Fair Ratio model, which adjusts the valuation multiple you might expect for Cleveland-Cliffs based on its scale, margins, sector and risk profile, points to a higher P/S than the one implied by today’s share price. That puts the current P/S below the level suggested by those fundamentals and below both sector and peer benchmarks, so the market is valuing the company’s revenue stream at a discount. For anyone weighing whether that gap is justified by the business quality and balance sheet, this is a starting point rather than a conclusion. Explore the numbers behind Cleveland-Cliffs's P/S valuation.
The Cleveland-Cliffs Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Cleveland-Cliffs valuation puzzle leaves off. They spell out what mix of future growth, profitability and earnings expectations would need to play out for today’s share price to look materially higher or lower. Each scenario links its number to a clear view on how Cleveland-Cliffs' revenue trends, margin profile and risk factors might evolve over time, which you can revisit as fresh information arrives.
Community views on Cleveland-Cliffs split between those who see extra upside in the story and those who think expectations already capture most of it.
Bull case: 13% undervalued
"Cleveland-Cliffs is poised to benefit disproportionately from the accelerating reshoring of U.S. manufacturing and infrastructure renewal, with multi-year government investments and new trade rules set to create sustained…"
Discover why this Narrative puts Cleveland-Cliffs at 13% undervalued.
Bear case: roughly fairly valued
"The ongoing shift in the North American steel market towards electric arc furnace mini-mills and increased reliance on scrap-based steel threatens Cliffs' market share and profit margins in the long term…"
Explore why this Narrative puts Cleveland-Cliffs at roughly fairly valued.
The Cleveland-Cliffs share price is only one piece of the decision
Who steers Cleveland-Cliffs, how their pay packages are structured, and whether those incentives pull in the same direction as your capital can be just as important as any valuation metric. See who runs Cleveland-Cliffs and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com