
What Bunge Global (BG)'s Raised EPS Outlook Means For Shareholders
- Bunge Global raised its full-year 2026 adjusted EPS guidance to a range of $9.25 to $9.75 after stronger soybean and softseed processing results, while acknowledging softer grain merchandising and higher integration and financing costs.
- The company is ahead of plan on Viterra cost synergies, now targeting about $350 million. This highlights both execution progress and the importance of turning processing gains into steadier earnings and better cash conversion.
- We will now examine how Bunge Global's investment narrative is shaped by the higher EPS guidance tied to stronger processing performance.
Scan beyond Bunge Global and compare its setup with hand-picked agribusinesses and processors on the list of solid balance sheet and fundamentals (23 results) list that pair sturdier finances with earnings potential.
Bunge Global Investment Narrative Recap
To own Bunge Global, you need to believe the oilseed complex and Viterra combination can support steadier processing earnings despite softer merchandising and low gross margin pressure. The higher 2026 EPS guidance leans on that thesis. The short term swing factor is whether processing strength holds up while weaker refined oils and grain trading do not erode the improved outlook.
The biggest operational risk right now sits in execution. Integration of Viterra, heavier capex, and already thin margins leave little room if cash conversion stays weak or regulatory shifts hit biofuels. If those issues persist, the raised guidance and current valuation could look stretched against a backdrop of limited revenue growth expectations.
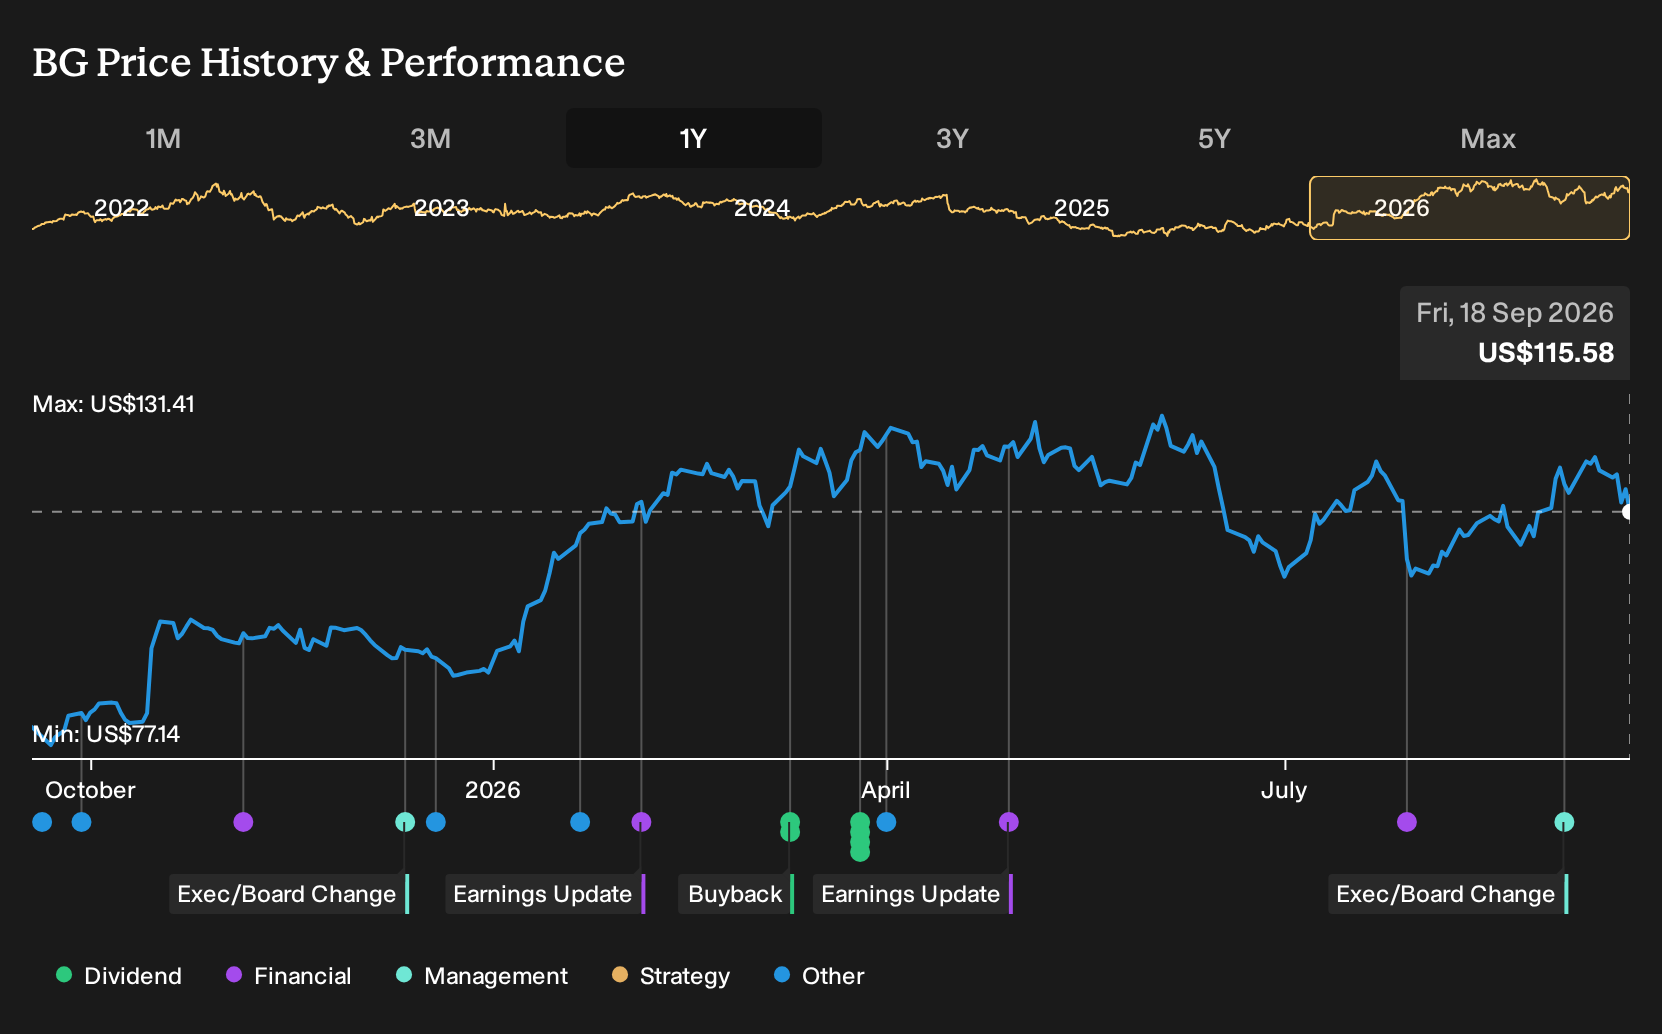
The most relevant recent development for this setup is the raised 2026 adjusted EPS guidance to US$9.25 to US$9.75, supported by stronger soybean and softseed processing. That upgrade arrived alongside softer views on Grain Merchandising and Milling and higher corporate, financing, and integration costs. This keeps the quality of earnings and cash generation front and center for you.
Heading into Morgan Stanley’s Laguna Conference on 15 September 2026, this mix gives management a clear talking point. The key questions are how much of the EPS uplift is structural, how dependable the roughly US$350m Viterra cost synergy target is, and whether the business can translate a better processing environment into stronger free cash flow despite debt coverage and margin concerns.
Bunge Global's narrative projects US$100.1b revenue and US$3.8b earnings by 2029. This projection assumes 7.5% yearly revenue growth and an earnings increase of about US$3.1b from US$686.0m today.
Uncover why Bunge Global's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Bunge Global, the biggest swing factor in the more optimistic narrative is not biofuel policy but the payoff from Viterra integration. The most bullish analysts were penciling in about US$97.5b of revenue and US$3.5b of earnings by 2029, before this guidance hike, so those views may evolve as new information becomes available.
Explore 3 other Bunge Global fair value estimates, including one that suggests as much as 240% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bunge Global research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bunge Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bunge Global's overall financial health at a glance.
Looking for more Bunge Global style investment ideas?
If you want to stress test your view on Bunge Global and build a wider watchlist around it, the Simply Wall St Screener can help you surface other businesses with traits that fit your approach.
- If balance sheet strength is non negotiable for you, start with a list of solid balance sheet and fundamentals (23 results). This couples financial resilience with room for earnings progress.
- If you are hunting for mispriced quality, scan through the 33 high quality undervalued stocks. These already show healthier fundamentals than their current pricing suggests.
- If lower volatility and durability matter most, focus on a 30 resilient stocks with low risk scores. This screens for businesses aiming for steadier risk profiles over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com