
Does Board Appointment Change The Bull Case For Innodata Stock (INOD)?
- Innodata has added Admiral Michael S. Rogers, former Director of the NSA and Commander of U.S. Cyber Command, to its Board of Directors, expanding the experience mix around cyber, intelligence, and AI safety.
- The appointment reinforces Innodata’s push into AI trust, safety, and Federal work, aligning governance with its focus on higher value, security critical AI services for government and large enterprises.
- We will now assess how Innodata’s investment narrative could shift as Admiral Rogers’ cyber expertise contributes to its Federal AI practice.
Scan how Innodata's AI safety push compares by checking peers in 89 AI infrastructure stocks that could also be positioned for security focused enterprise and Federal workloads.
Innodata Investment Narrative Recap
To own Innodata, you need to buy into a story where high quality AI data, safety and evaluation services can support sustained demand from large tech and enterprise clients, while newer Federal work gradually becomes meaningful. The near term swing factor still sits in execution on big accounts and the ability to keep projects recurring rather than one off.
On the risk side, investor focus stays on customer concentration and cost discipline, not this board change. Admiral Rogers’ appointment helps the Federal AI safety pitch but does not directly change the key near term questions around contract durability, pricing pressure as data work commoditises, or whether heavier investments will outpace incoming revenue.
The most relevant backdrop for this appointment is Innodata’s Federal practice, which was launched last Fall to apply its data engineering, model evaluation and AI safety work to government and defense missions. That unit sits in a segment where cyber credentials matter and where agencies are wrestling with how to deploy more capable AI systems while still proving they are safe.
For you as a shareholder, the link is operational. Stronger Federal relationships could complement existing tech and enterprise exposure, potentially smoothing some customer concentration risk if Innodata converts pilots into repeat work. The flip side is execution risk. Federal contracts can be lumpy, procurement cycles are long and any delay would hit a cost base that is already scaling ahead of confirmed demand.
What The New AI Safety Focus Means For Innodata’s Targets
Innodata's narrative projects US$618.6 million revenue and US$71.7 million earnings by 2029. This lines up with analyst assumptions of 29.7% yearly revenue growth and an earnings increase of about 82% from US$39.3 million today.
Uncover why Innodata's fair value indicates a 115% potential upside to its current price, which could narrow quickly.
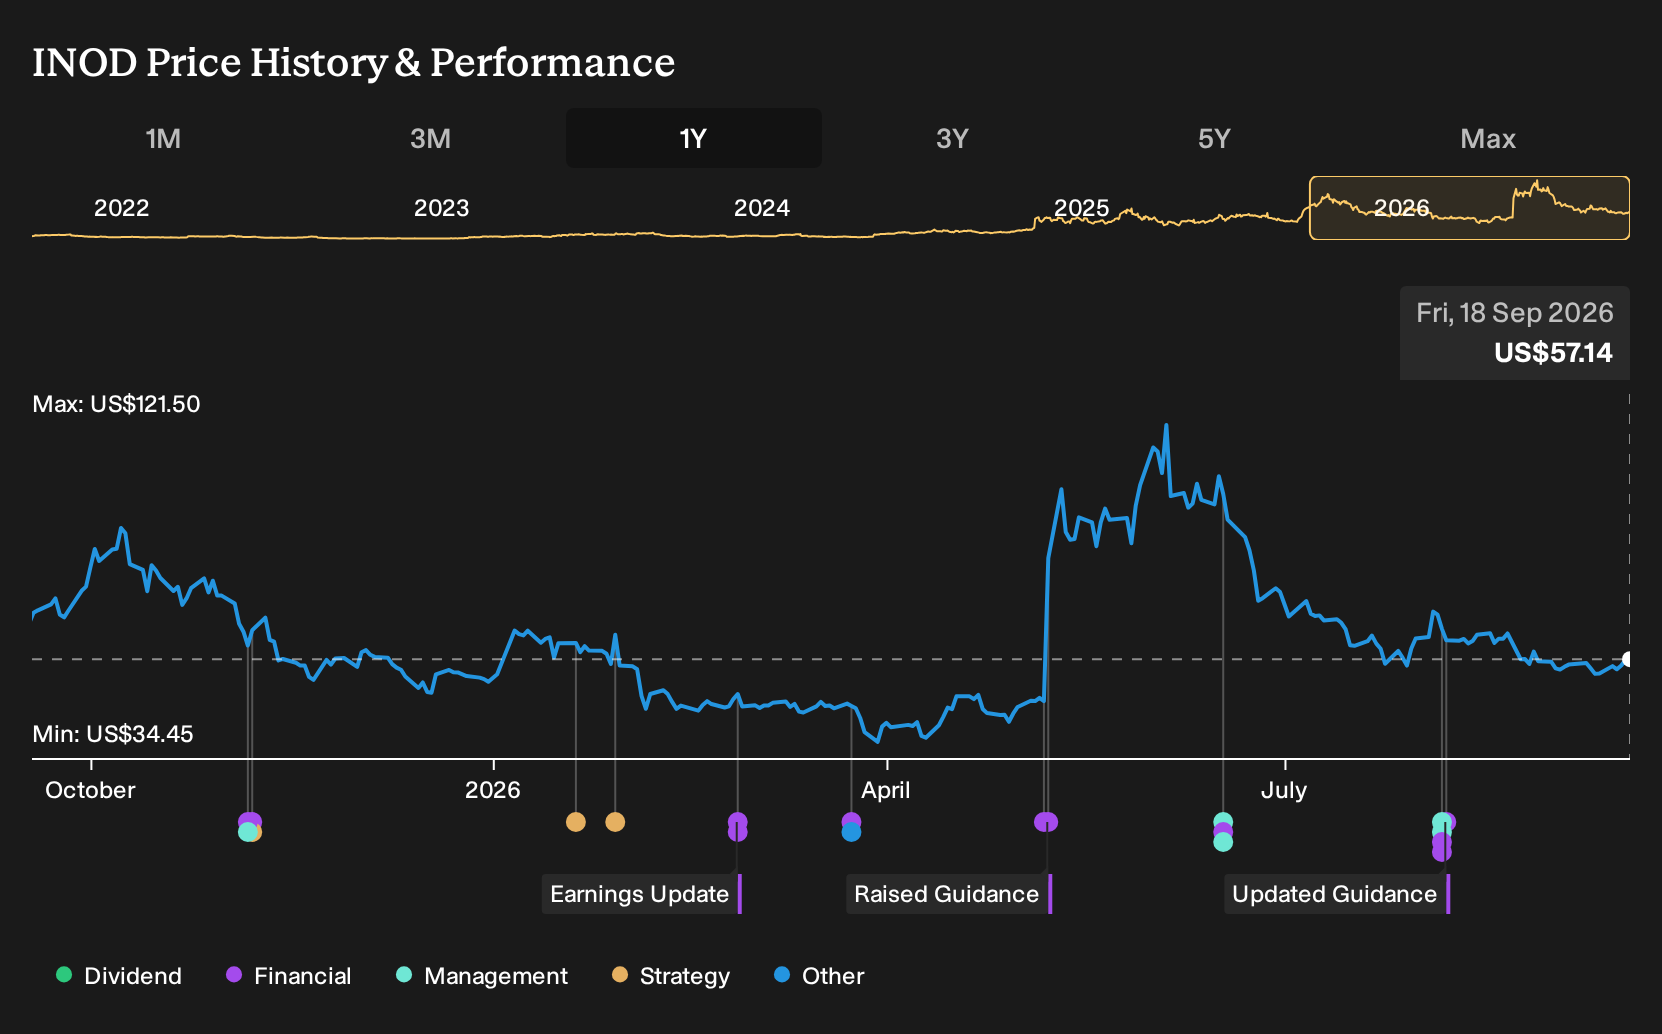
Exploring Other Perspectives
One alternative view puts customer concentration front and center for Innodata. The most cautious analysts were modeling revenue of about US$622.7 million and earnings of roughly US$58.1 million by 2029, before this board news. You can treat Admiral Rogers’ appointment as a fresh input and explore how those assumptions might shift.
Explore 6 other Innodata fair value estimates, including one that suggests as much as 59% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Innodata research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Innodata. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Innodata's overall financial health at a glance.
Looking for more Innodata inspired investment ideas?
If the Innodata story has you thinking about position sizing and diversification, it can help to line up a few other candidates that fit different risk and quality profiles. The Simply Wall St Screener is a way to find stocks that match the kind of balance sheet strength, value tilt, or income focus you want to pair with a position like this.
- For investors who want resilient businesses that aim to limit downside risk, consider a curated group of 30 resilient stocks with low risk scores that may help anchor a portfolio around stability.
- If value is the priority and you are hunting for solid fundamentals at what could be attractive prices, you can scan through 33 high quality undervalued stocks that might warrant a closer look on your watchlist.
- Income focused investors who care about cash returns today rather than only distant upside can review 6 dividend fortresses that target yields above 5% while still emphasizing staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com