
Alkami Technology (ALKT) In Focus After MANTL Wins As Undervalued View Holds
Alkami Technology (ALKT) is back in focus after fresh MANTL milestones, including Embers Credit Union going live with MANTL Loan Origination and in-branch account opening, which is reaching nearly 90,000 monthly applications nationwide.
Recent moves in Alkami Technology highlight that momentum has been choppy rather than one way. The 1 day share price return of 1.97% and 30.31% share price gain over 90 days sit against a year to date share price decline of 15.65% and a 1 year total shareholder return that is down 24.36%. This points to improving sentiment in the short run but a mixed experience for longer term holders.
Scan beyond Alkami Technology to see how other digital finance players are positioned with the curated list of solid balance sheet and fundamentals (23 results), which may be better prepared to handle choppy sentiment.
Alkami Technology looks like a capable digital banking partner, yet the share price has swung between sharp rallies and longer stretches of disappointment. So is that execution now available at an appealing valuation, or already fully paid for?
Most Popular Narrative: 12% Undervalued
With Alkami Technology last closing at $19.13 against a widely followed fair value of $21.67, the stock sits in territory that the prevailing narrative views as undervalued, hinging on whether its digital banking platform can keep turning client demand into durable recurring revenue.
Demand for platform integration and digital onboarding/account opening capabilities is accelerating among banks and credit unions as they compete for younger, digitally-native account holders. Alkami's strong cross-sell momentum (MANTL, data analytics, marketing modules) and seamless integration strategy position it to capitalize on this shift, likely driving sustained revenue growth and increasing average revenue per user.
See why 26 investors see Alkami Technology as 12% undervalued.
Result: Fair Value of $21.67 (UNDERVALUED)
Still, the Alkami Technology story can break if consolidation among community and regional banks shrinks its customer pool, or if digital banking platforms become heavily commoditized and pressure pricing power.
Find out about the key risks to this Alkami Technology narrative.
Another View on Alkami Technology Valuation
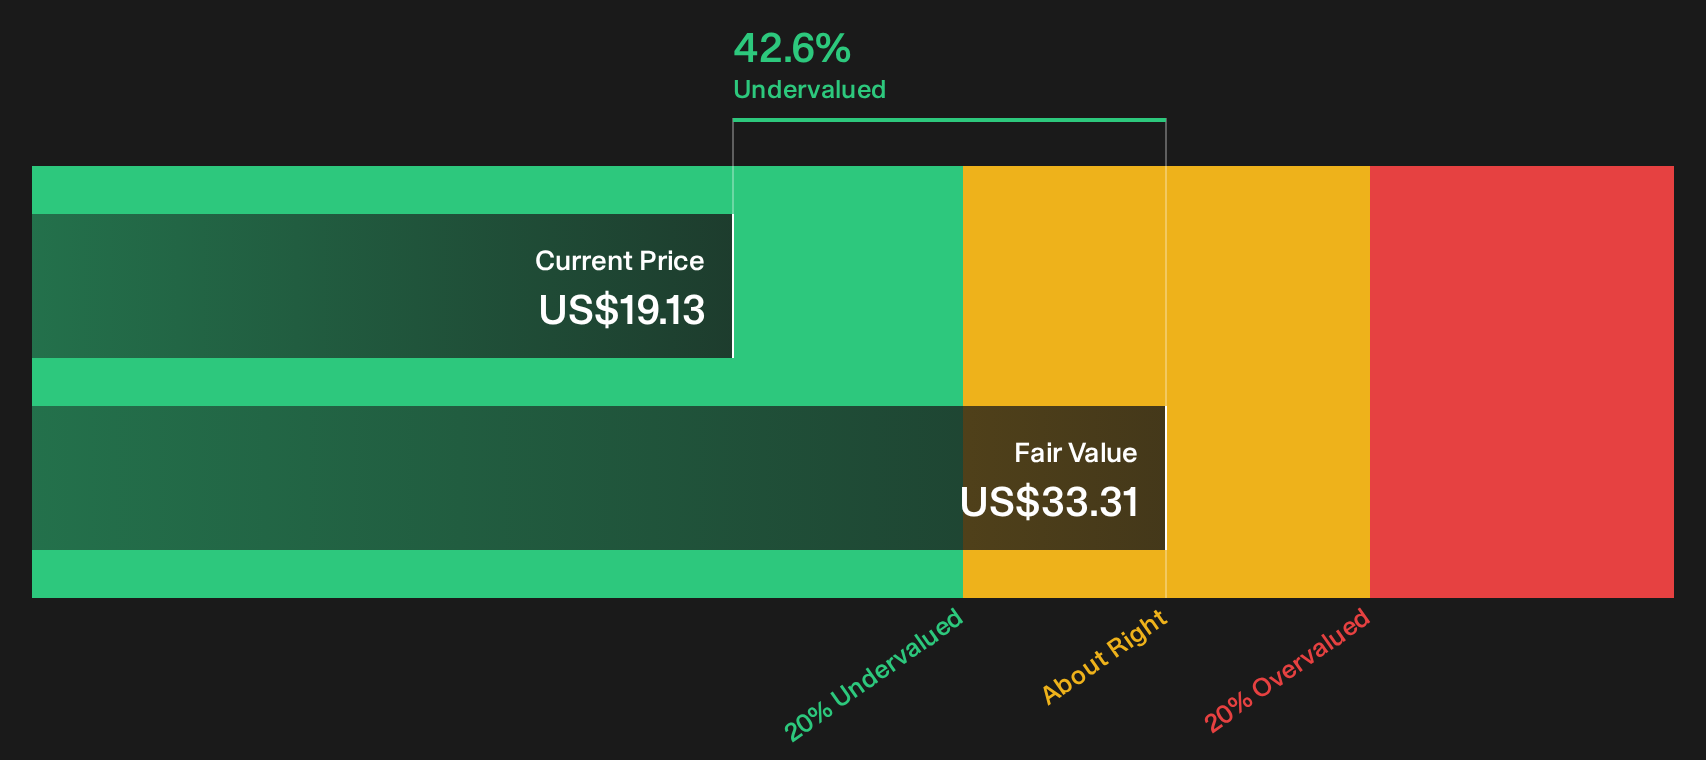
The first lens on Alkami Technology leans on analyst targets and narrative fair value, but the SWS DCF model presents an estimated future cash flow value of $33.31 compared with a recent price of $19.13, which suggests the shares screen as materially undervalued.
That is a big gap for you to weigh, so the key question is whether the underlying cash flow assumptions feel realistic or overly generous for where Alkami Technology is today.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the Alkami Technology story so far feels mixed, treat that as your prompt to look under the hood yourself and move quickly while sentiment is still resetting. To see what the current optimism is built on, review the 2 key rewards.
Looking for more investment ideas beyond Alkami Technology?
If Alkami Technology has your attention, do not stop there. Broaden your watchlist with fresh ideas that match your risk comfort and return goals.
- Target resilient balance sheets and steadier financial footing with the 30 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price by scanning 33 high quality undervalued stocks before others catch on.
- Spot potential early-stage opportunities with stronger fundamentals through the 8 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com