
How Raised Guidance Will Impact Nordson Stock Investors
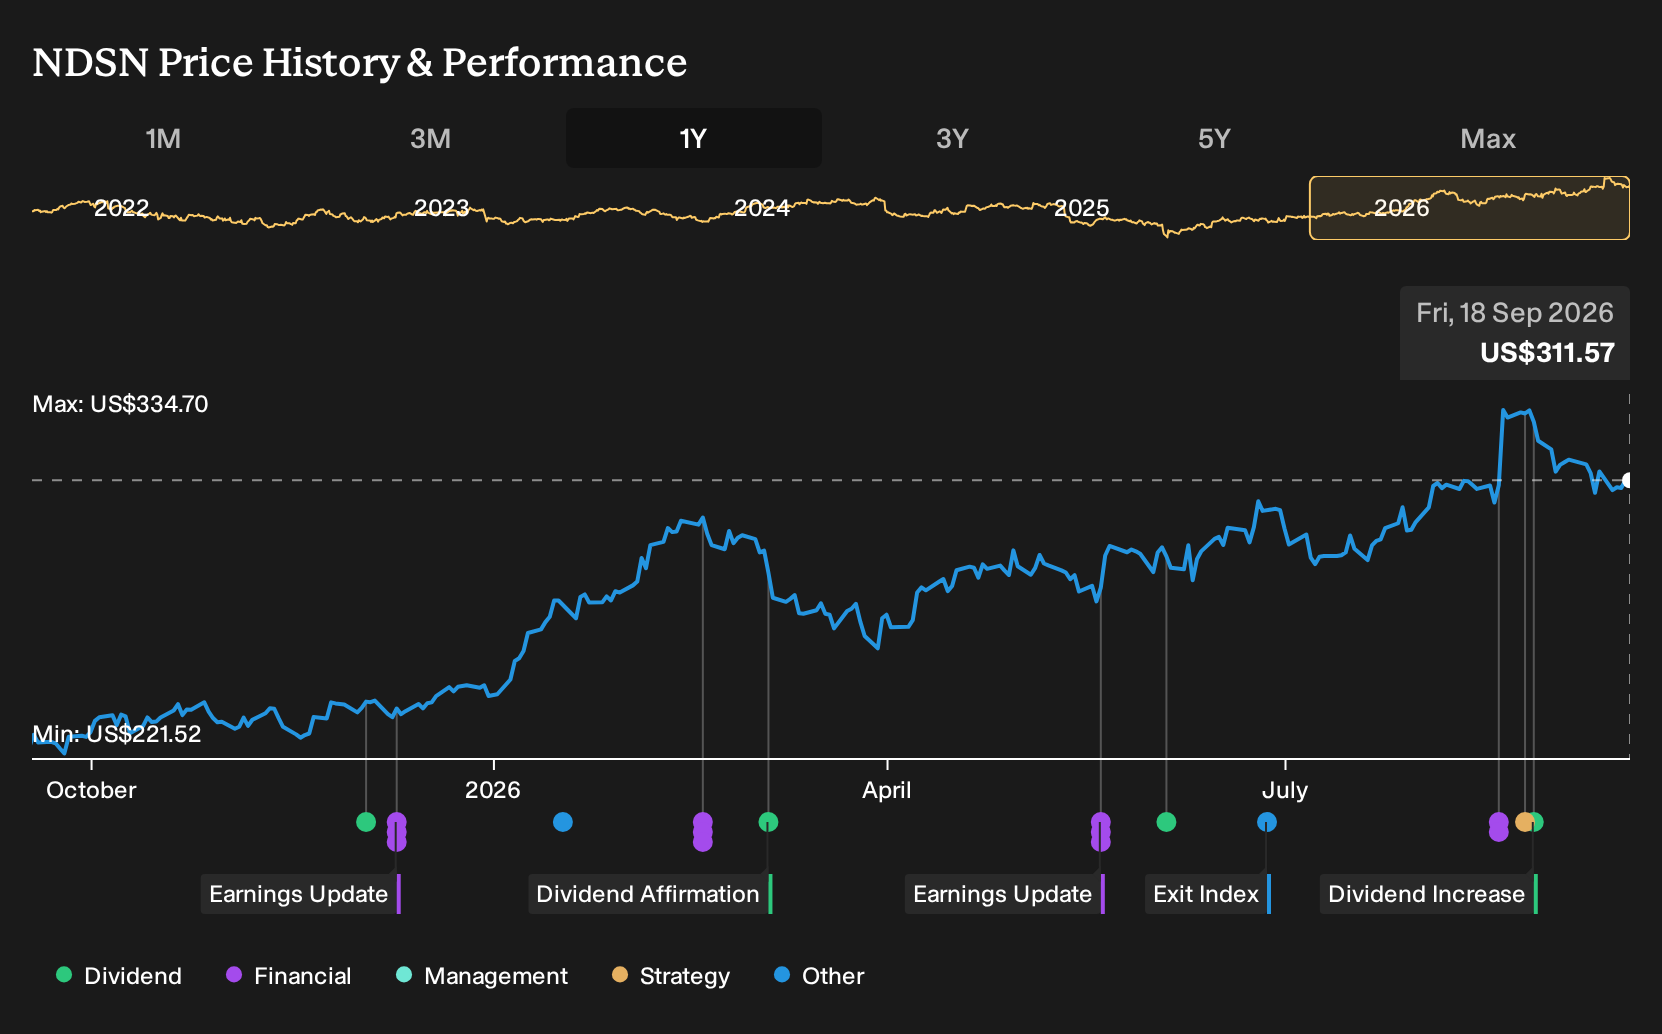
- Nordson reported strong fiscal 2026 third quarter results, with adjusted earnings and revenue above expectations and management lifting full year sales and adjusted earnings guidance.
- The update also highlighted broad organic growth across all segments, record sales levels, and capacity for further acquisitions, pointing to active execution on Nordson's long term growth agenda.
- We will explore how Nordson's raised full year guidance reshapes the existing investment narrative around recurring revenues and margin resilience.
Nordson Investment Narrative Recap
To own Nordson, you need to believe its mix of consumables, aftermarket parts, and highly engineered systems can keep demand relatively steady across cycles. The third quarter beat and higher full year guidance support that view by pointing to healthy order flow and solid execution across segments, even as some end markets remain mixed.
The key near term swing factor is whether strength in advanced technology and medical applications can offset any slower recovery in polymer processing and automotive related lines. Elevated spending in SG&A and R&D, plus reliance on acquisitions, still looks like the main operational risk if new products or deals do not convert into profitable growth.
Against this backdrop, the most relevant update is management lifting fiscal 2026 sales and adjusted earnings guidance after strong third quarter results. That move ties directly into the existing thesis that Nordson can pair recurring revenue streams with disciplined cost control to support margin resilience, even when customers hesitate on large capital projects.
The raised outlook also matters for the acquisition narrative. Management flagged capacity for further deals on top of prior moves like Atrion, so investors now have to watch two things at once. First, whether the core business can keep order momentum into the fourth quarter. Second, whether any future transactions avoid integration slips that could strain an already leveraged balance sheet.
Nordson's current earnings are reported at US$528.1 million, with analyst consensus pointing to earnings of US$726.7 million by 2029. This implies earnings growth of about US$198.6 million over the period, alongside forecast revenue of US$3.5b in the same year, assuming revenue expands at 6.9% annually until 2029.
Discover why Nordson's fair value is essentially aligned with its current price.
Exploring Other Perspectives
Lower ranked analysts focus on acquisition risk instead. They worry Atrion related costs could bite into Nordson margins, which is why their earlier models pointed to earnings of about US$555.2 million and US$774.9 million by 2029 on 5.1% annual revenue growth. That is a more cautious story, and it might shift after this latest update.
Explore another Nordson fair value estimate, including one that suggests as much as 5% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nordson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nordson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordson's overall financial health at a glance.
Looking for more Nordson sized investment ideas?
If Nordson has sharpened your focus on quality, recurring cash flows, and disciplined execution, it can help to scan a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, filter for businesses with strong fundamentals and pricing that appears reasonable using the 33 high quality undervalued stocks.
- If income is a priority, narrow in on companies with payouts that may be more resilient by checking the 6 dividend fortresses.
- For a focus on resilience and capital strength, zero in on businesses with robust balance sheets and solid financial profiles via the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com