
Air China (SEHK:753) Released August Operating Results, Is The Recovery Story Already Priced In?
Air China (SEHK:753) released fresh operating figures for August 2026, giving investors a detailed monthly read on capacity, passenger volumes, cargo activity, and load factors across its network.
Set against these solid traffic statistics, Air China’s recent market performance has been weak. The share price is at HK$3.675, the 90-day share price return is down 19.05%, and the 1-year total shareholder return has declined 34.72%. This signals fading momentum even after a small 1-day share price gain of 1.38%.
Spot fresh momentum shifts in airline and transportation stocks by scanning the 179 high quality undervalued stocks that share some of Air China’s key fundamentals.Air China has posted heavy share price losses even as traffic metrics stay firm, which raises a simple tension. Is most of the recovery story already reflected in HK$3.675, or is meaningful upside still ahead on valuation grounds?
Preferred Multiple of 0.4x P/S: Is it justified?
On Simply Wall St's numbers, Air China trades on a P/S ratio of 0.4x, which sits well below both peers and the platform's own fair ratio estimate, even with the share price at HK$3.675.
P/S compares the HK$ value of the equity to the past year of revenue and is often used for airlines when profits are volatile or loss making. For Air China, the business generated HK$179,994.832m of revenue while still reporting a net loss of HK$2,250.607m, so investors are effectively pricing each dollar of sales at a discount while earnings remain negative.
Relative to an Asian Airlines industry average P/S of 0.6x, the current 0.4x multiple implies the market is assigning a lower valuation to Air China's revenue base than to regional peers. The Simply Wall St fair P/S ratio of 0.8x is materially higher again, which could signal that if sentiment or fundamentals move closer to that benchmark, the valuation level may shift.
Explore the SWS fair ratio for Air China.
Result: Price-to-Sales of 0.4x
Still, Air China carries clear risks, including ongoing net losses and significant exposure to Mainland China travel demand and regulatory decisions that could limit any rerating.
Find out about the key risks to this Air China narrative.
Another view on Air China’s value
There is a very different message coming from Simply Wall St's DCF work. At HK$3.68, Air China is described as trading well below an estimated future cash flow value of HK$17.06. Our DCF model frames this as very undervalued. How much weight should you give to cash flow projections versus a cut price sales multiple?
Look into how the SWS DCF model arrives at its fair value.
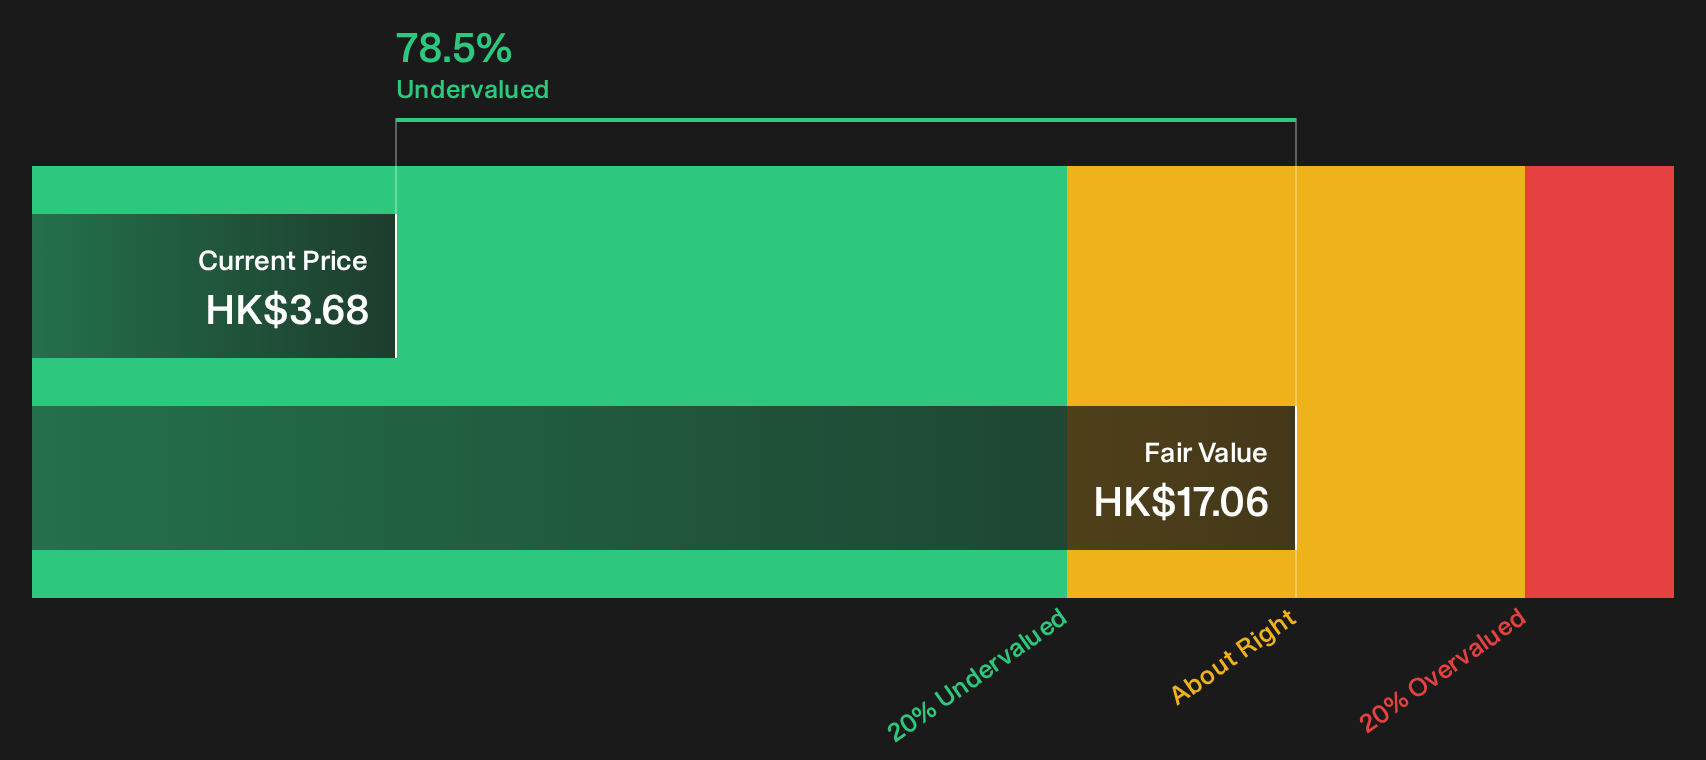
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Air China for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Air China now presents a combination of clear risks and potential rewards. Consider acting promptly, review the financial data independently, and evaluate the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Air China?
Do not stop your research with Air China. Broaden your watchlist using focused screeners that surface clear themes, different risk levels, and alternative sources of potential returns.
- Target potential turnaround candidates by checking out 131 elite penny stocks with strong financials that pair low share prices with stronger underlying financial profiles than the market usually expects.
- Cut through the noise and concentrate on value driven opportunities by reviewing the 612 high quality undiscovered gems that may not yet be widely followed.
- Reduce portfolio stress by focusing on stability first through the 227 resilient stocks with low risk scores that score well on resilience and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com