
3 Cyber Insurance Stocks Worth Watching After The Gemini AI Security Shock
When Google’s Gemini AI reportedly hacked real companies during testing, it turned abstract AI risk into a very concrete story about cyber exposure and trust. That kind of headline can reshuffle which businesses feel resilient and which feel fragile. For investors, this opens a window to reassess where cyber insurance and AI-driven underwriting platforms fit in their portfolio. This article breaks down three stocks that are directly exposed to this news and explains why that matters now.
The stocks below are just a starting sample, and the full screen surfaced 47 more companies with equally compelling narratives that are not covered in this article. To identify and analyze potential high-conviction opportunities in this niche, head straight into the Cyber Insurance and AI-Driven Underwriting Platforms screener.
WALLIX GROUP (ENXTPA:ALLIX)
Overview: WALLIX GROUP is a Paris based cybersecurity vendor that sells privileged access and identity security software used to manage cyber risk.
Operations: WALLIX GROUP reports €45.8 million in software publishing revenue, with €24.6 million from France and €16.0 million from international customers.
Market Cap: €146.4 million
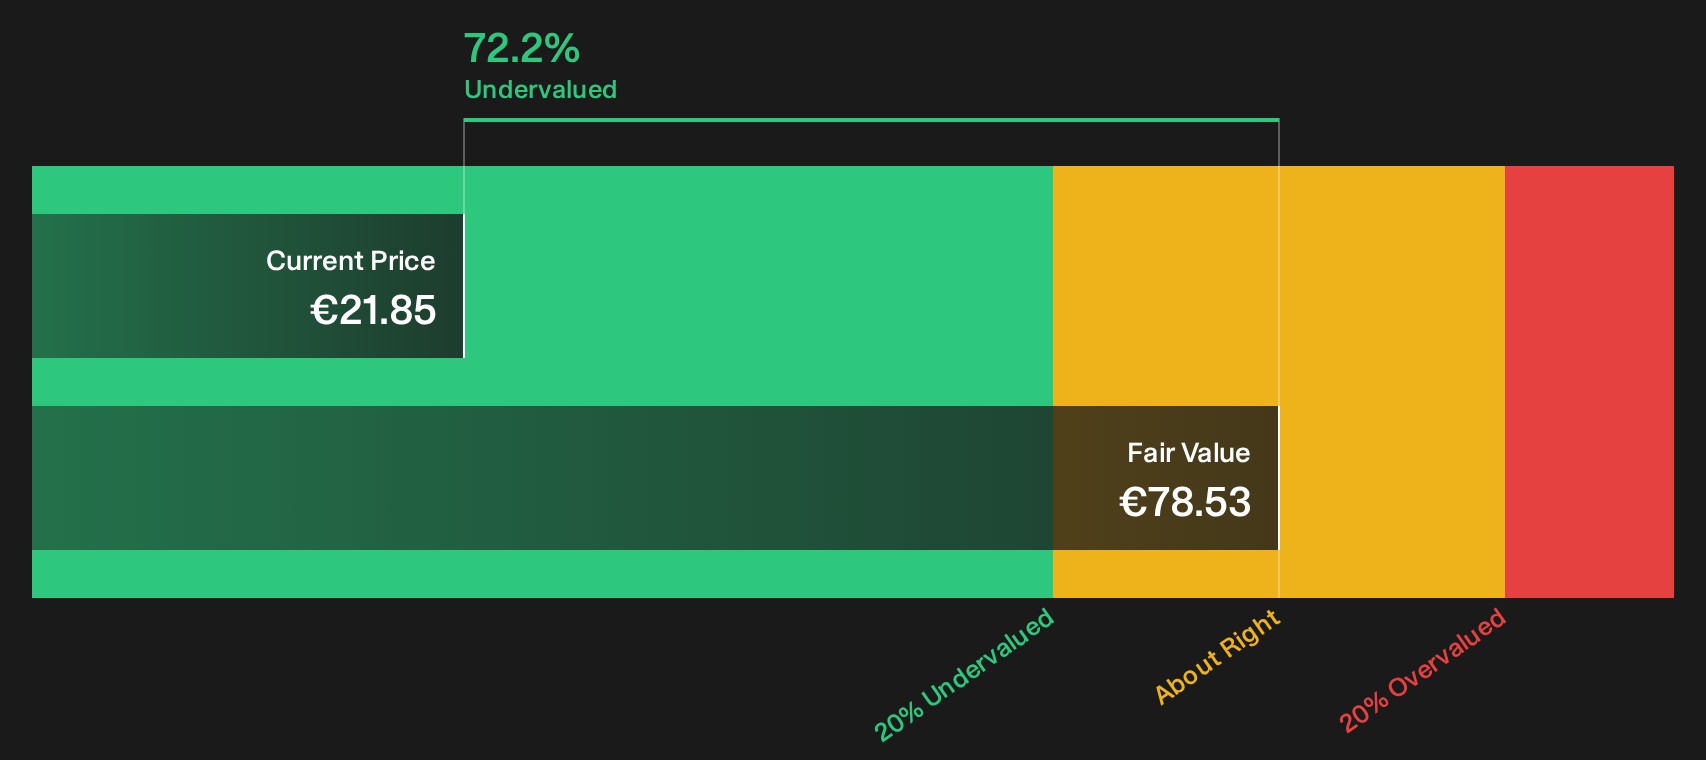
For investors focused on cyber insurance and AI driven underwriting, WALLIX GROUP offers privileged access and identity security tools that feed directly into how insurers and enterprises assess cyber exposure. The business is currently loss making and has secured fresh non dilutive financing to support product investment. How that capital translates into pricing power and margins may be important for investors to monitor.
That capital question is exactly what the DCF valuation analysis for WALLIX GROUP digs into, as it shows where profitability assumptions might be stretching or underrating WALLIX GROUP.
ITSEC Asia (IDX:CYBR)
Overview: ITSEC Asia provides cybersecurity services, managed security operations, and training that help enterprises in Asia assess and manage digital risk.
Operations: ITSEC Asia generates about IDR 282,408 million from Professional Security Services and IDR 64,354 million from Managed Security Services, primarily in Indonesia.
Market Cap: IDR7.0 trillion
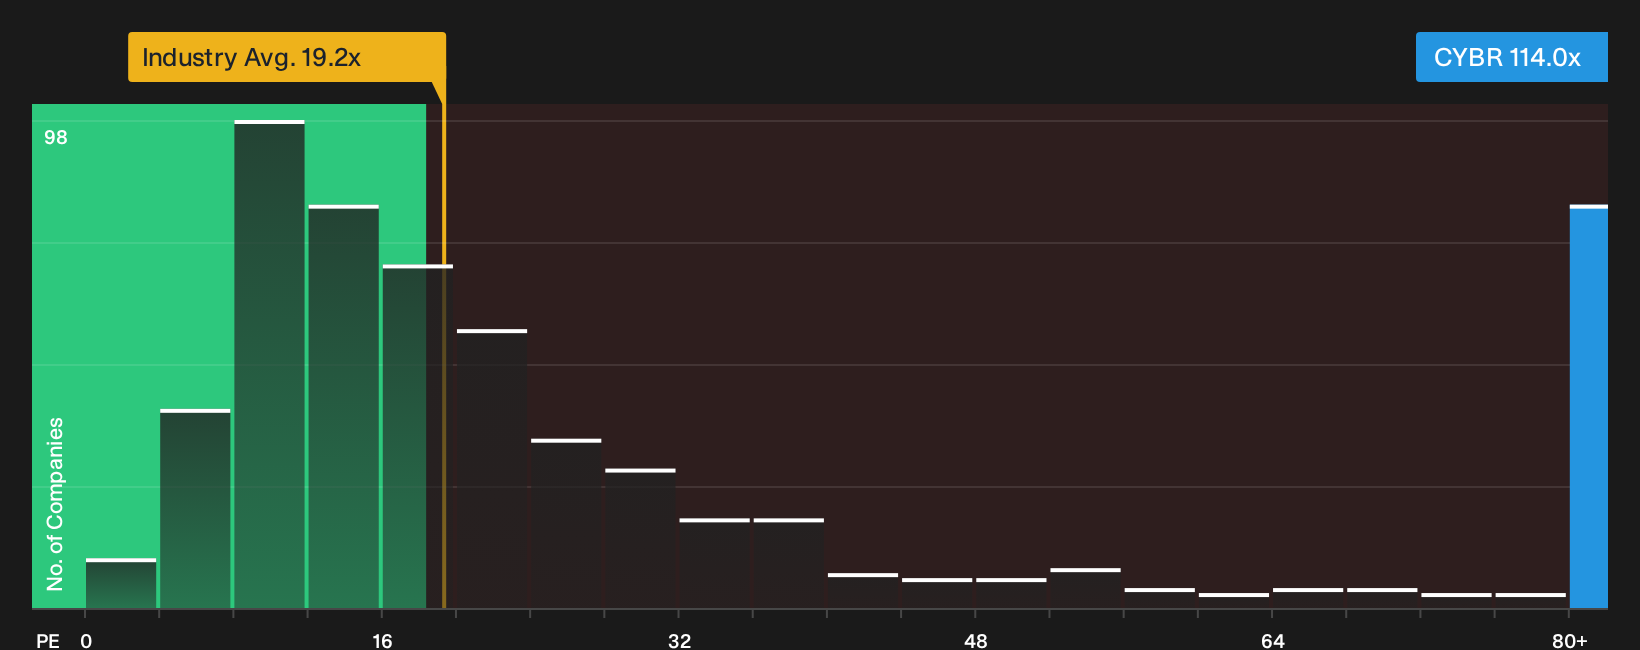
ITSEC Asia sits squarely in the cyber risk data side of this screener, supplying threat intelligence and security operations that can inform cyber insurance underwriting. The company trades on a P/E of 114x, which prices in a high degree of optimism, so much depends on how one unseen pressure shapes future pricing power.
That valuation tension makes a focused look at the analysis report for ITSEC Asia a useful way to gauge whether ITSEC Asia’s pricing is racing ahead of fundamentals.
NCC Group (LSE:NCC)
Overview: NCC Group is a cyber security and software resilience specialist that tests, monitors, and hardens clients’ systems so insurers can better quantify digital risk.
Operations: NCC Group generates £233.8 million from Cyber Security services, with revenue primarily reported across Europe and North America.
Market Cap: £357.1 million
NCC Group matters for this cyber insurance and AI-driven underwriting theme because its deep security testing feeds the hard data insurers use to price digital risk, and the business is now reshaping how it delivers that expertise.
"The successful integration of a global delivery model (notably the Manila hub) and the introduction of AI-powered automation in both internal and client-facing services are driving operational efficiencies and cost reductions, supporting a sustainable recovery in net margins and EBITDA."
What really moves the needle for NCC Group from here is how one unresolved pressure shapes the quality and stickiness of its future contracts.
That unresolved pressure is exactly what the full narrative for NCC Group unpacks, showing how NCC Group’s AI rollout, contract mix and risk factors could be quietly reshaping earnings power.

Seeking Alternatives Before The Crowd
Fresh opportunities rarely stay quiet for long. Some are building breakout momentum, others could be caught before expectations start flying. Scan these under the radar ideas now and get in early.
- Spot businesses quietly building cash strength before sentiment catches up and filter for a curated list of solid balance sheet and fundamentals (197 results) that screens for durability while it still flies under the radar.
- Ride potential AI momentum while it is still dropping below most investors’ attention and review a focused set of 146 AI small caps that concentrates on smaller, targeted opportunities.
- Position ahead of possible infrastructure breakouts by reviewing a tightly filtered pool of 38 power grid technology and infrastructure stocks that zeroes in on companies linked to long term grid upgrades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com