
Is American Electric Power Company (AEP) Fully Priced After Its Niagara Project Filing?
American Electric Power Company (AEP) drew fresh attention after scheduling investor meetings in September and submitting updated technical documentation for the Niagara Project to the Federal Energy Regulatory Commission, giving investors new regulatory and engagement signals to assess.
Recent trading has been softer, with the share price declining 4.97% over the past 30 days and 6.02% over 90 days, yet American Electric Power Company still shows a 3.62% year to date share price gain and a 15.56% 1 year total shareholder return. This indicates that longer term momentum has held up better than the short term tape as investors weigh fresh regulatory and investor relations updates around projects like Niagara.
Compare how American Electric Power Company stacks up on grid resilience and balance sheet strength by scanning our curated list of solid balance sheet and fundamentals (23 results) alongside AEP's latest regulatory moves.
After a choppy few months and fresh regulatory filings, the question for American Electric Power Company holders is simple. Does the current setup still skew the risk and reward toward new buyers, or has most of the upside already been claimed?
Most Popular Narrative: 6.2% Overvalued
Against a last close of $120, the prevailing narrative pegs American Electric Power Company at a fair value of $113, framing the current price as modestly ahead of that anchor and putting more weight on long term grid demand than on short term earnings noise.
The market is no longer valuing AEP on current cash flow alone; it is pricing in its role as the exclusive toll-keeper for the AI era. With 80% of its growth driven by hyperscalers with Tier-1 credit profiles, the risk of "stranded assets" or non-payment is described as being virtually eliminated.
See why 10 investors see American Electric Power Company as 6% overvalued.
Result: Fair Value of $113 (OVERVALUED)
Still, the American Electric Power Company narrative could be knocked off course if data center demand proves less durable than expected or if regulators slow project approvals.
Find out about the key risks to this American Electric Power Company narrative.
Another View On American Electric Power Company
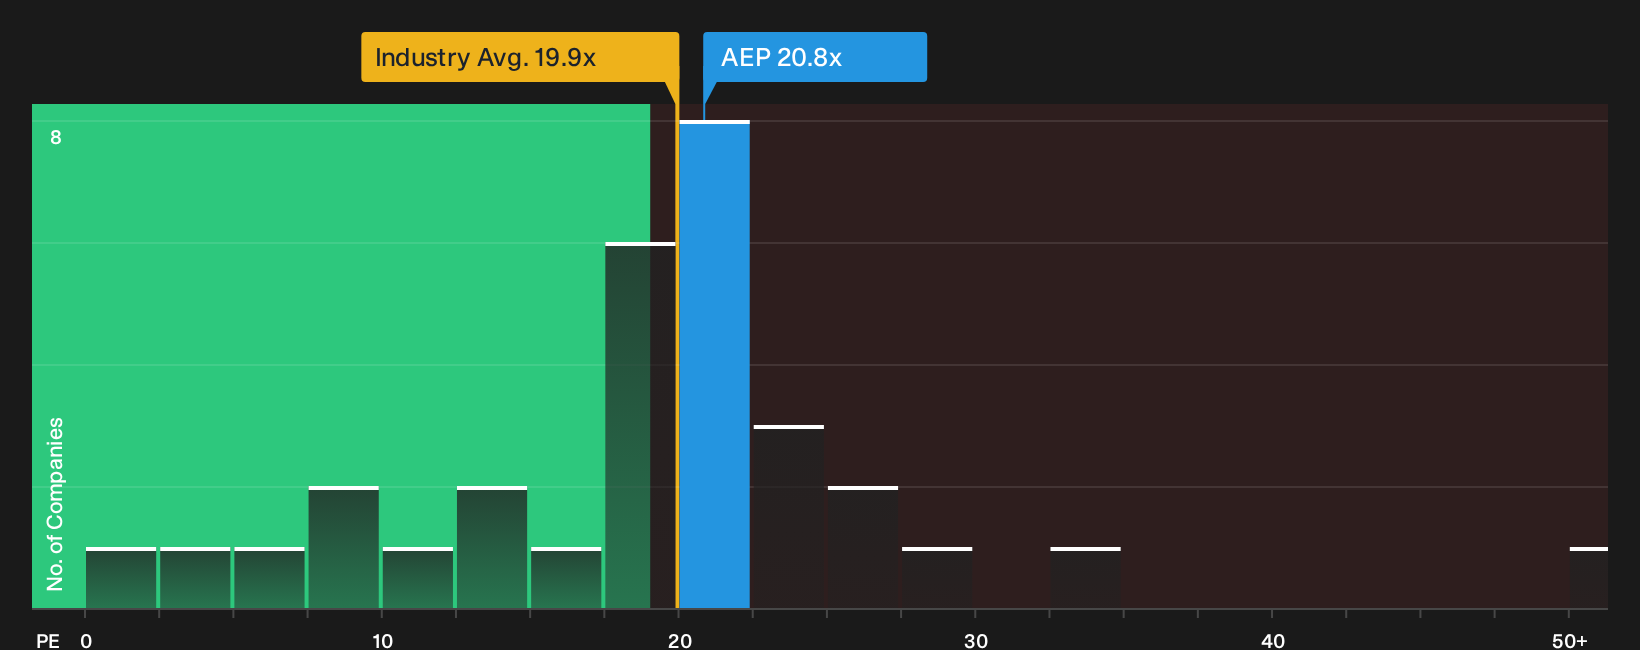
A different lens comes from the P/E ratio. American Electric Power Company trades at 20.8x earnings compared with a 19.9x industry average and a 20.4x peer mark, while the fair ratio is 24x. That gap suggests investors accept a premium today. The question is where the market may push the multiple next.
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
With mixed sentiment surrounding American Electric Power Company following recent valuation checks and project updates, it may be useful to review the numbers yourself before the narrative changes again. To consider both the potential opportunities and the key risks in one place, start with 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond American Electric Power Company?
If American Electric Power Company has sharpened your focus on risk and reward, broaden your watchlist now so you are not relying on a single thesis.
- Target potential mispricing by scanning companies that combine quality fundamentals with discounted valuations using the 33 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with robust payout profiles through the 6 dividend fortresses.
- Limit downside shocks by filtering for steadier performers using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com