
Do Executive Hires Change The Bull Case For Marex Group Stock (MRX)?
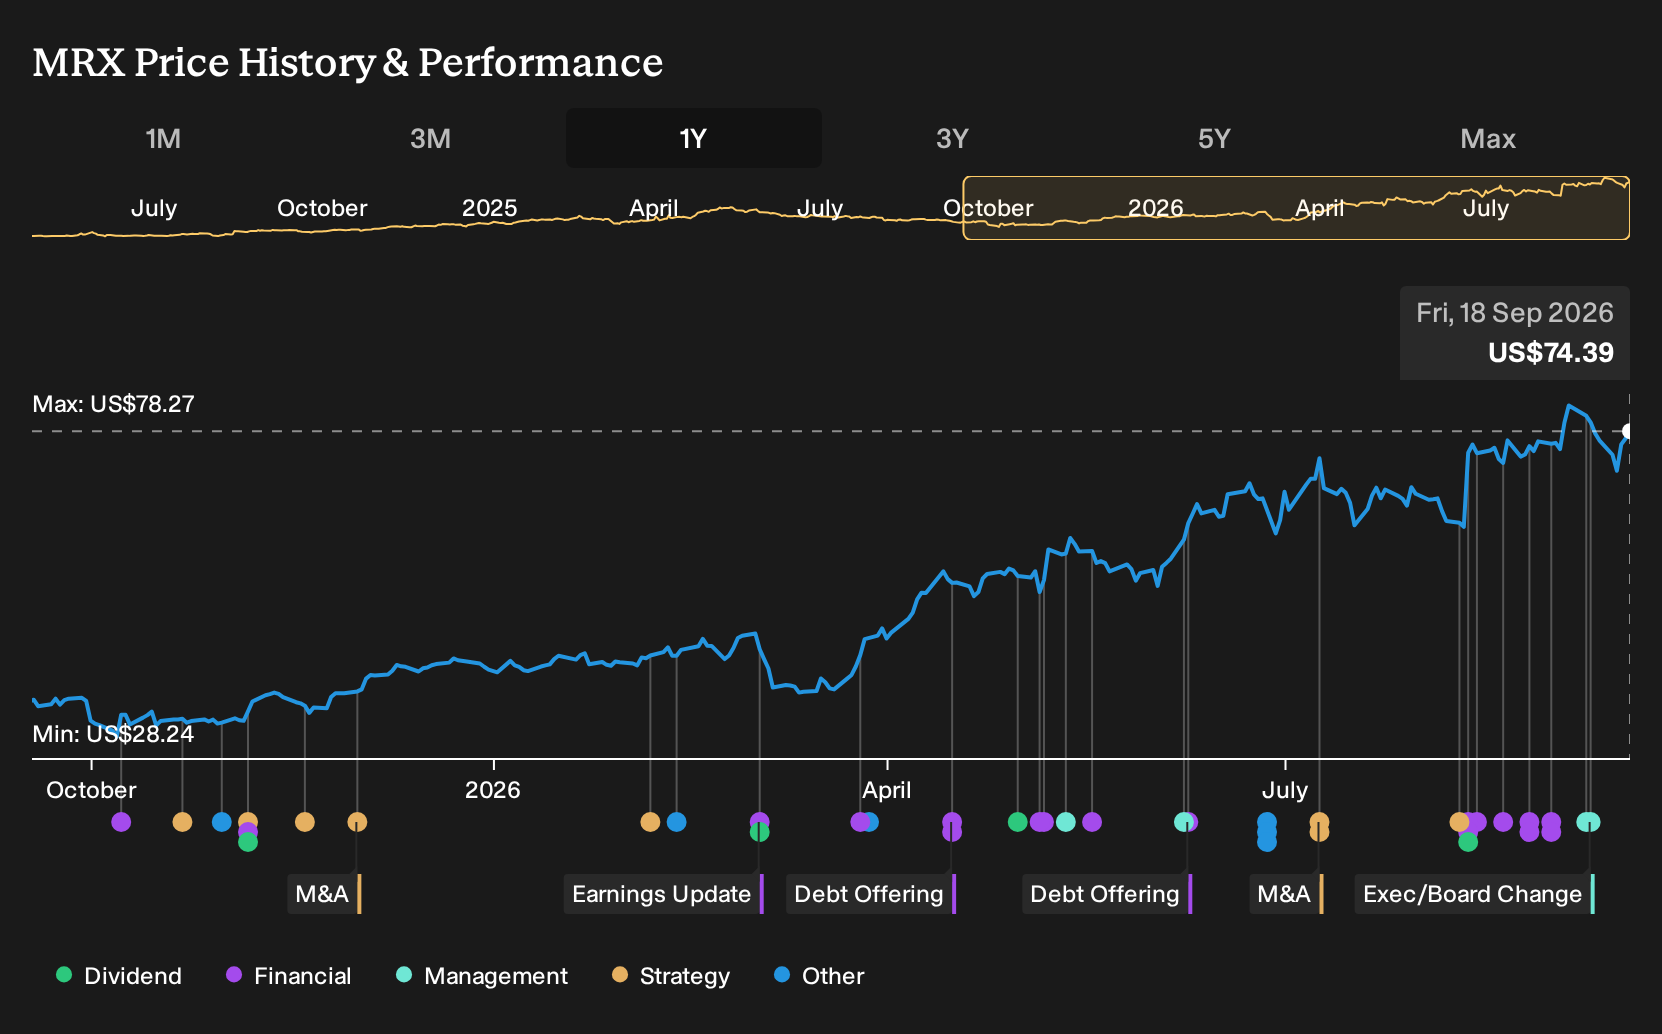
- Marex Group recently appointed Allison DiClemente as global head of capital introduction and Robert Cheeseman as head of prime services Asia, adding leadership depth to client coverage and regional execution.
- These hires concentrate seasoned executives on capital introduction and Asian prime services, areas that can influence client mix, funding access, and operating efficiency across Marex Group's broader platform.
- We will now examine how Marex Group's investment narrative could shift as a result of Allison DiClemente leading global capital introduction.
Marex Group Investment Narrative Recap
To own Marex Group, you need to believe the platform can keep turning a broad mix of clearing, agency, market making, and hedging services into resilient earnings, even as revenue is expected to decline 3.6% per year over the next 3 years. In the short term, the focus stays on execution in Prime Services and Agency & Execution, which are key to client activity and trading volumes.
The biggest near term risk is operational, not headline related. Debt is not well covered by operating cash flow, and the business still leans on acquisitions, so integration missteps or higher funding costs could bite. The DiClemente and Cheeseman hires help the story, but do not remove those core pressures.
The Allison DiClemente appointment matters most for the current catalysts around Prime Services and broader client flows at Marex Group. She is leading a 13 person capital introduction team that connects hedge funds with institutional investors across major markets, which directly touches the Prime Services and Agency & Execution growth thesis.
If that unit executes well, it can support higher transaction volumes and potentially steadier client balances, both central to the idea that earnings can keep growing even as revenue is expected to decline. Any weakness in capital introduction effectiveness, or slower client uptake around security based swaps and related products, would cut against that same catalyst set.
Marex Group's narrative projects US$2.9b revenue and US$634.3 million earnings by 2029, based on analyst assumptions that revenue will decrease by 5.8% per year and that earnings would need to rise by about US$258.5 million from US$375.8 million today to reach that forecast level.
Uncover why Marex Group's fair value indicates a 7% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You see a very different story if you focus on the alternate risk that market volatility cools off. The most pessimistic analysts were already baking in revenue of about US$2.7b and earnings of roughly US$508.6 million by 2029, well below the Marex Group consensus path, so fresh leadership news could eventually shift those expectations again.
Explore 4 other Marex Group fair value estimates, including one that suggests as much as 41% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Marex Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Marex Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marex Group's overall financial health at a glance.
Looking for more Marex Group investment ideas?
If Marex Group has sharpened your focus on balance sheets, funding risk, and earnings resilience, it can be helpful to widen the lens and compare it with other listed businesses that share some of those traits but with different risk profiles.
- If you want potential growth with a smaller starting size, scan for compact opportunities in the 8 elite penny stocks with strong financials that combine low share prices with stronger underlying fundamentals.
- For investors who care most about getting solid assets for a fair entry price, weigh Marex Group against a 33 high quality undervalued stocks that pair healthier balance sheets with supportive cash flows.
- If capital protection is your first filter, stress test your portfolio ideas against a 30 resilient stocks with low risk scores that screen for businesses with more resilient financial risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com