
Did Positive PH ILD Trial Data Just Shift Roivant Stock Investment Narrative?
- Roivant Sciences reported positive Phase 2 PHocus data for inhaled mosliciguat in PH-ILD, with clinically meaningful and statistically significant improvements in pulmonary vascular resistance, six-minute walk distance and NT-proBNP, and continued evaluation in a global Phase 3 PHrontier trial.
- The scale of pulmonary vascular resistance reduction reported for mosliciguat, alongside once-daily inhaled dosing and potential first-in-class positioning, highlights a differentiated asset within Roivant Sciences' respiratory and rare disease-focused pipeline.
- We now examine how Roivant Sciences' investment narrative could shift given the PHocus pulmonary vascular resistance reduction reported for mosliciguat in PH-ILD.
Roivant Sciences Investment Narrative Recap
To own Roivant Sciences, you need to believe the pipeline can translate strong clinical readouts into future products while the business is still loss making and heavily investing in R&D. The Phase 2 PHocus success with mosliciguat directly supports that pipeline thesis and keeps clinical execution front and center as the key near term driver.
The main short term catalyst now sits with clean execution and enrollment in the larger Phase 3 PHrontier study, as well as ongoing late stage programs like brepocitinib and IMVT 1402. The biggest risk remains trial setbacks or delays combined with high spending and legal overhangs that could stretch cash and push out any eventual profitability.
The PHocus data and the upcoming European Respiratory Society Congress presentation are closely linked. Roivant is putting the mosliciguat data in front of pulmonary specialists and peers, which can help stress test the findings and shape expectations for the PHrontier design and execution. That is very much an operating milestone, not just an investor relations event.
The related investor call and presence at Citi’s Biopharma Back to School Summit keep mosliciguat and the broader portfolio in focus as potential catalysts. For you as a shareholder, the question is whether Roivant can keep converting these detailed clinical datasets into a coherent development path while managing cash burn, legal disputes and competition across autoimmune and respiratory markets.
Roivant Sciences' current analyst narrative points to revenues of US$1.9b and earnings of US$334.7m by 2029. This outlook is built on a very large annual revenue growth rate of about 533%, with earnings expected to move from a loss of US$266.3m today to a gain of US$334.7m, an earnings swing of roughly US$601m.
Uncover why Roivant Sciences' fair value indicates a 5% potential upside to its current price that could narrow quickly.
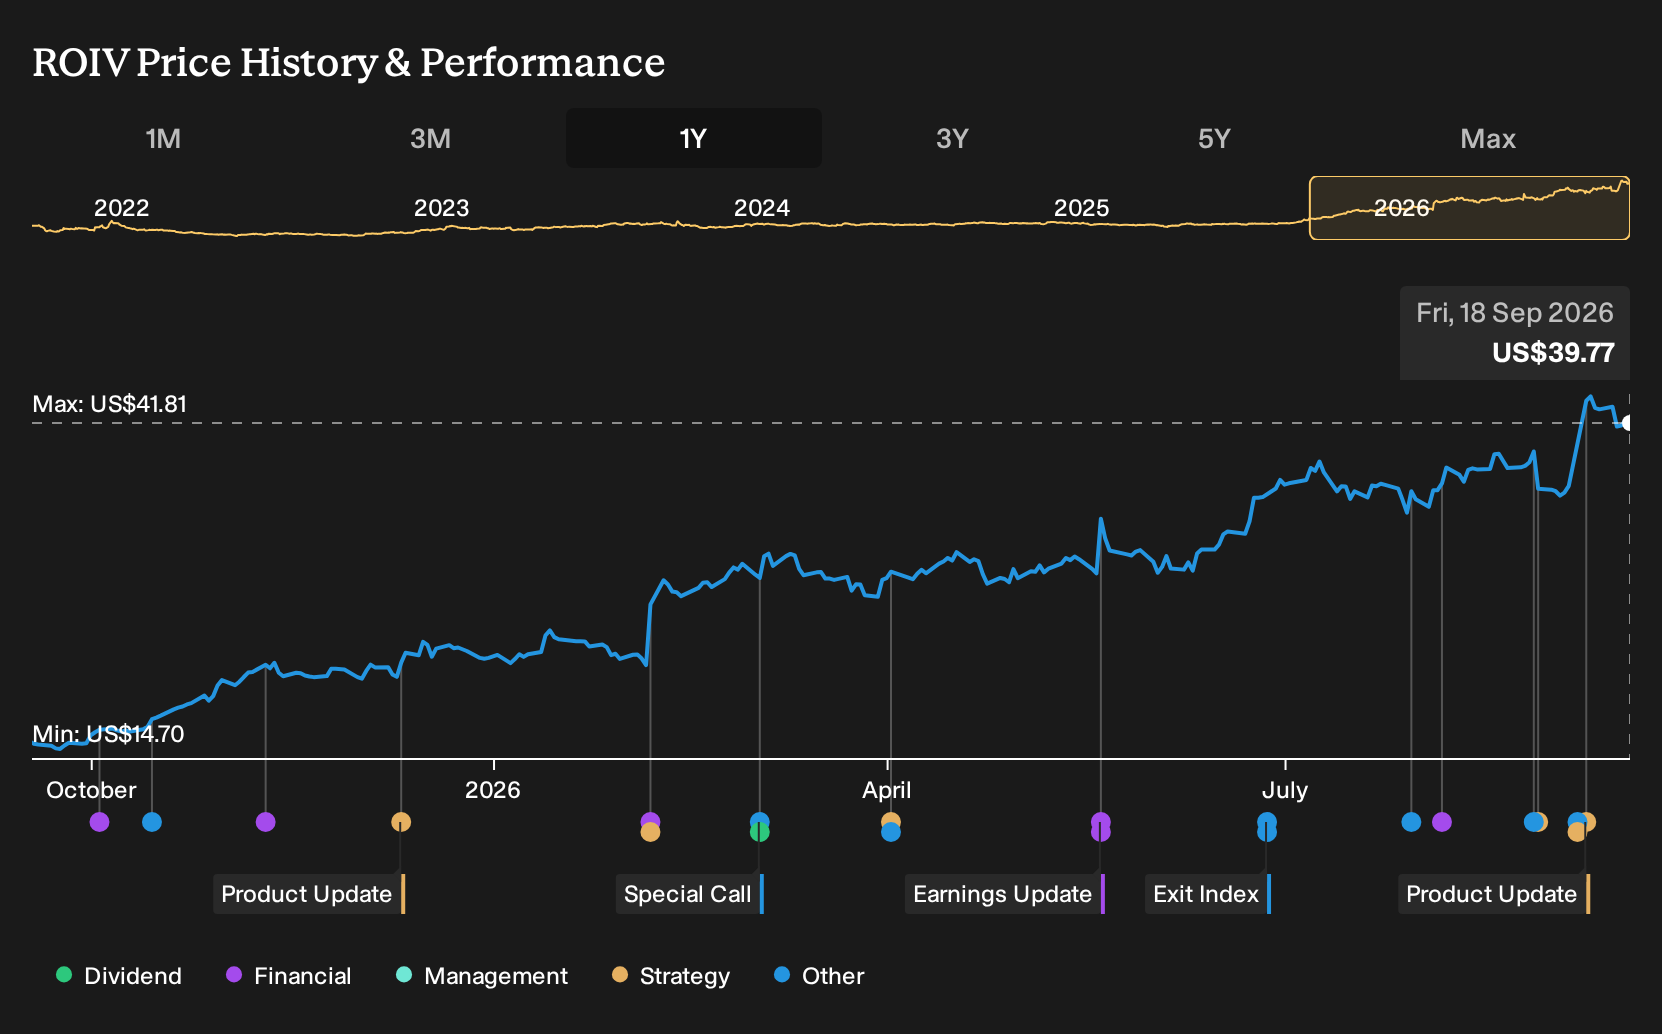
Exploring Other Perspectives
Some of the lowest Roivant Sciences forecasts leaned heavily on autoimmune execution risk rather than PH-ILD upside. Those analysts were only penciling in about US$1.2b of revenue and earnings of roughly US$220.7m by 2029, well below consensus. The new mosliciguat data could prompt them to reconsider that view, so it may be useful to compare several viewpoints before deciding what feels reasonable.
Explore 4 other Roivant Sciences fair value estimates, including one that suggests as much as 75% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Roivant Sciences research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Roivant Sciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Roivant Sciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Roivant Sciences?
Once you have a view on Roivant Sciences, it can help to widen the lens and compare it with other businesses that share similar financial qualities or risk profiles. A focused screener is a simple way to surface a short list of candidates that fit what you care about most.
- If capital preservation comes first for you, start with companies that pair resilient balance sheets with steady fundamentals through the 30 resilient stocks with low risk scores.
- If you are hunting for quality at a reasonable entry point, widen your watchlist to include companies trading below what their fundamentals might support via the 33 high quality undervalued stocks.
- If you prefer to back under-the-radar stories before they gain wider attention, filter for stronger fundamentals in smaller, less crowded ideas using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com