
Worthington Steel (WS) Expands Electrical Steel Footprint On A Narrative That Sees Value
Worthington Steel (WS) has moved into focus after committing capital to expand its electrical steel operations in Canada and Mexico, alongside an expected majority stake acquisition in European producer Sitem.
Recent trading tells a mixed story for Worthington Steel. The share price has slipped about 7% over the past month and roughly 18% over 90 days. Even so, the 1-year total shareholder return is still slightly positive at about 1%, suggesting longer term holders have seen modest gains even as short term momentum has cooled.
Scan how Worthington Steel compares with hand-picked metal and materials players by reviewing the list of solid balance sheet and fundamentals (23 results) that are also committing capital to long term capacity expansion.
Worthington Steel is committing fresh capital just as the share price has cooled, which puts you at a crossroads. Should you lean in at today’s level, or hold back and wait in the hope that valuation offers a cleaner entry later?
Most Popular Narrative: 12% Undervalued
Worthington Steel closed at $33.33 while the most followed narrative pegs fair value at $38.00. This frames the recent price weakness as a potential valuation gap rather than just poor sentiment.
Worthington Steel is poised to benefit from increased demand in the electrical steel market due to AI initiatives, more data centers, and an anticipated annual power demand growth of more than 6% over the next 15 years, which should lead to higher revenues.
Strategic investments and acquisitions, such as the expansion of electrical steel capabilities in Canada and Mexico and the expected closing on a 52% stake in the European company Sitem, are set to enhance market share and drive revenue growth.
See why 4 investors see Worthington Steel as 12% undervalued.
Result: Fair Value of $38 (UNDERVALUED)
Still, weak shipments in areas like automotive and construction, along with pressure from lower selling prices and higher SG&A, could easily upset the Worthington Steel narrative.
Find out about the key risks to this Worthington Steel narrative.
Another View on Worthington Steel Valuation
The fair value of $38 for Worthington Steel comes from a narrative and multiples based model, yet the SWS DCF model paints a very different picture. On that approach, the estimated future cash flow value is $11.44 per share, which frames WS as richly priced rather than 12% undervalued.
The gap between a $38 narrative fair value and an $11.44 DCF output raises a practical question for you: Which set of assumptions about growth, margins and capital intensity feels closer to how Worthington Steel might actually operate over time?
Look into how the SWS DCF model arrives at its fair value.
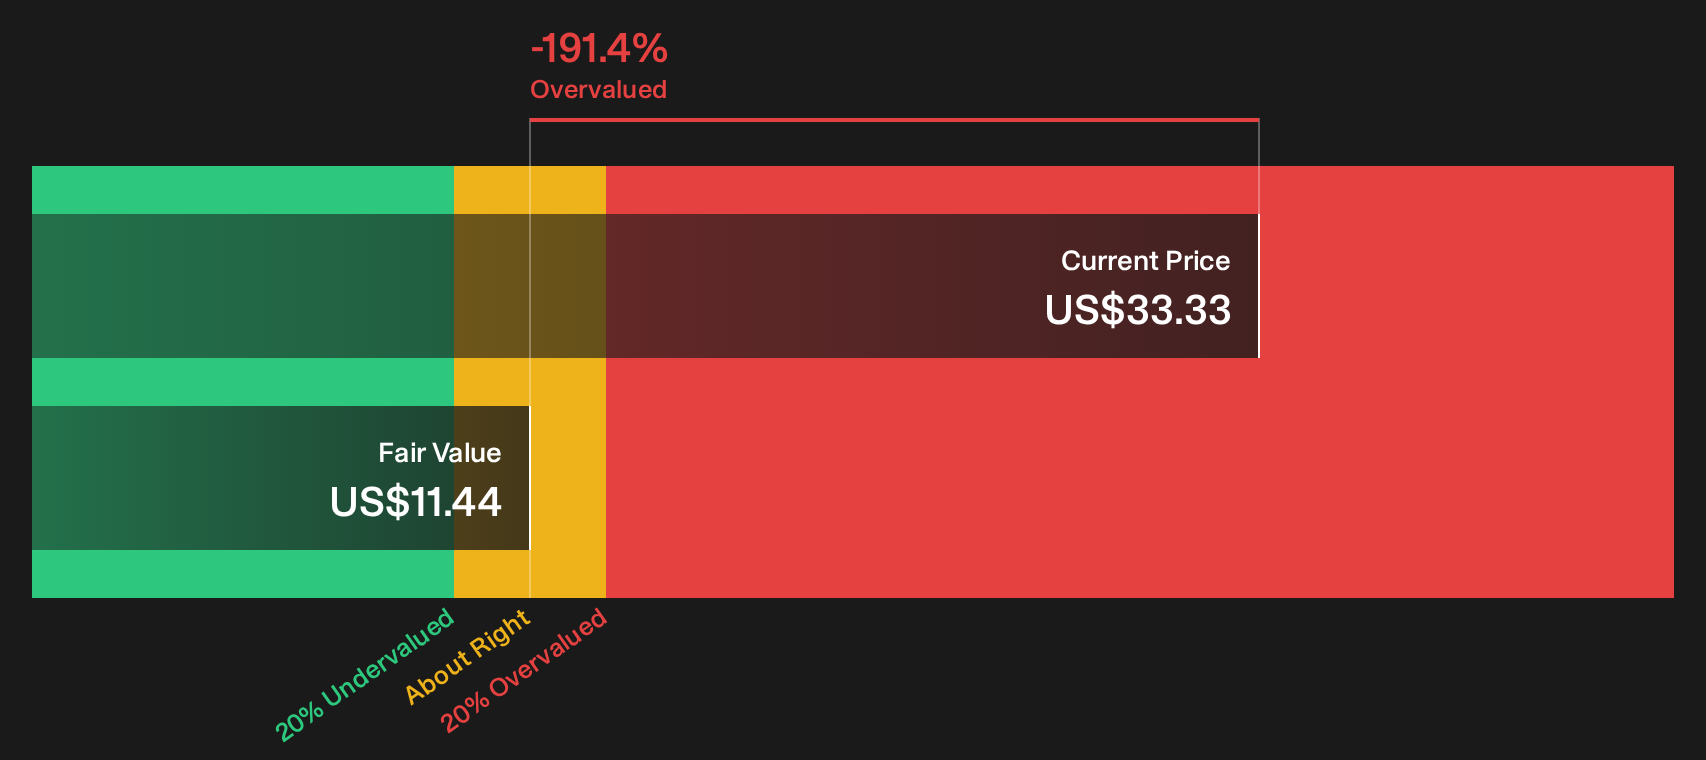
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Worthington Steel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Worthington Steel story feels finely balanced, consider moving quickly. Stress test the thesis against the data that matter most to you using the 4 important warning signs.
Looking for more Worthington Steel investment ideas?
Before you move on from Worthington Steel, give yourself an edge by scanning a few focused idea lists on Simply Wall St’s screener so you are not relying on a single stock story.
- Target potential mispricings by reviewing the 33 high quality undervalued stocks that combine quality fundamentals with what may be more attractive price tags.
- Prioritize resilience by scanning the 30 resilient stocks with low risk scores that may offer steadier profiles when you want to dial down portfolio volatility.
- Hunt for future leaders early by checking the 16 high quality undiscovered gems that receive less attention yet still show strong underlying business characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com